Medical device company LeMaitre Vascular (NASDAQ: LMAT) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 11.3% year on year to $67.97 million. On the other hand, next quarter’s revenue guidance of $70.9 million was less impressive, coming in 1.8% below analysts’ consensus estimates. Its GAAP profit of $0.65 per share was 5.3% below analysts’ consensus estimates.
For more on LeMaitre, read our full research report for free.
LeMaitre (LMAT) Q3 2026 highlights:
- Revenue $67.97 million vs S&P analysts’ consensus estimates of $67.39 million (11.3% year-on-year growth, 0.9% beat)
- EPS (GAAP) $0.65 vs analysts’ consensus estimates of $0.69 (5.3% miss)
- Adjusted EBITDA $20.5 million vs analysts’ consensus estimates of $20.66 million (30.2% margin, 0.8% miss)
- Revenue guidance $70.9 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $72.2 million
- GAAP EPS guidance $2.80 at the midpoint for the full year, missing analysts’ consensus estimates by 2.7%
- Operating margin 26%, down from 27.7% in the same quarter last year
- Free cash flow margin 28.9%, down from 43.4% in the same quarter last year
- Organic revenue rose 12% year on year (beat)
- Market capitalization $1.84 billion
Chairman/CEO George LeMaitre said, “We expect 2026 to be another year of healthy sales (+11%) and EPS growth (+18%). Biologics continue to drive sales due to Artegraft’s international launch and the continued growth of RestoreFlow Allografts. The acquired B. Braun products will strengthen our core vascular portfolio while leveraging our expanding 31-country sales force.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can post a good quarter or two, but many enduring ones grow for years. LeMaitre’s 12.1% annualized revenue growth over the last five years was solid. Its growth beat the average healthcare company and shows its offerings resonate with customers.
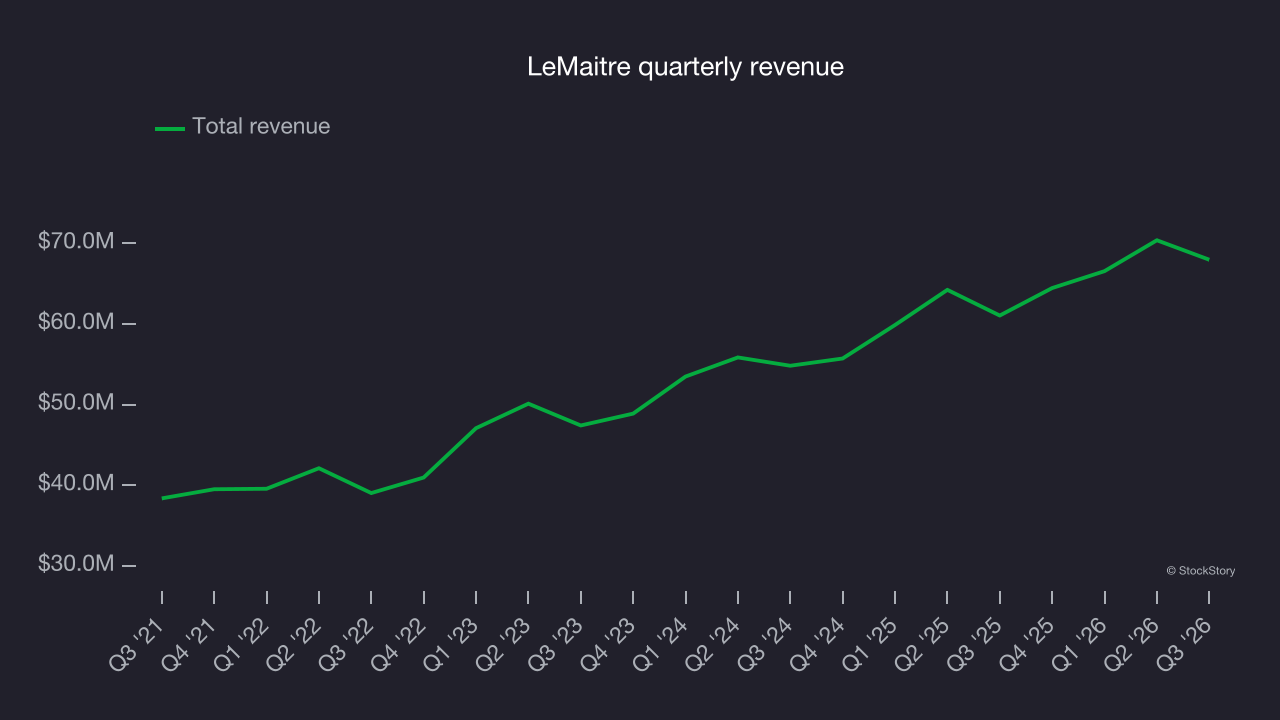
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. LeMaitre’s annualized revenue growth of 12.4% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 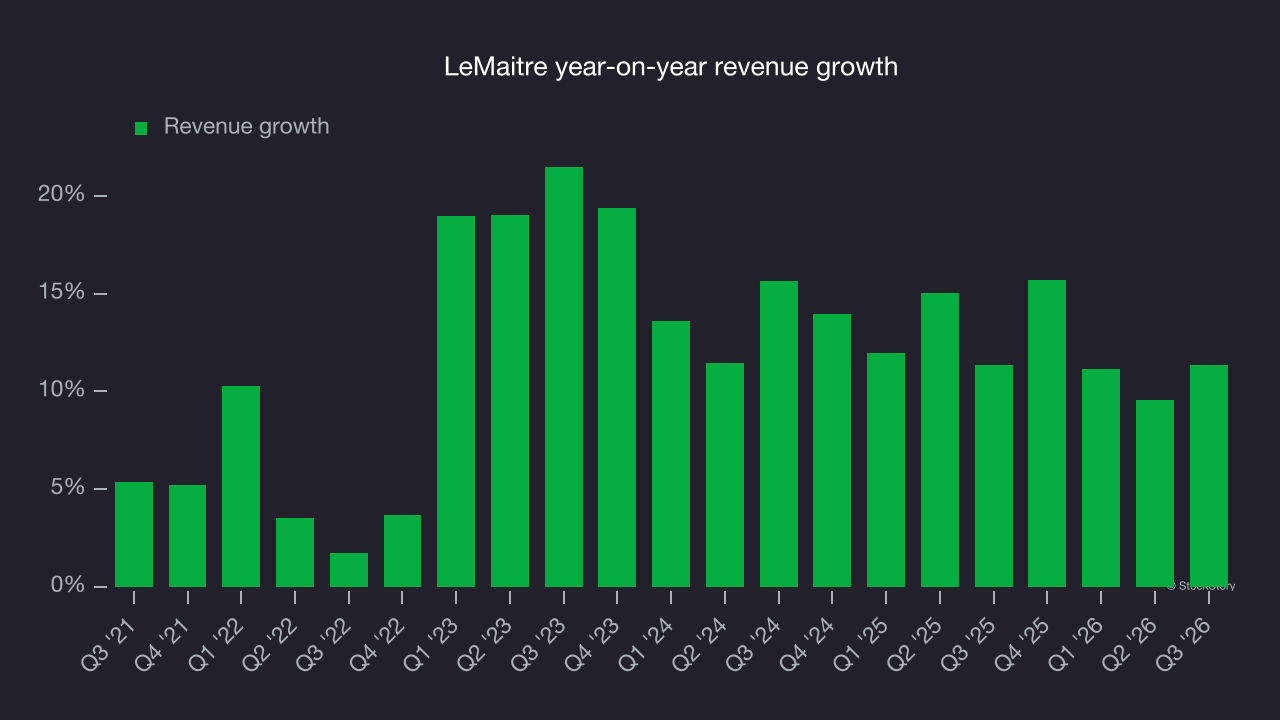
Organic revenue helps clarify the company’s growth dynamics by stripping out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, LeMaitre’s organic revenue averaged 12.6% year-on-year growth. This was in line with its two-year revenue growth, indicating that core operations, rather than acquisitions and divestitures, drove most of its results. 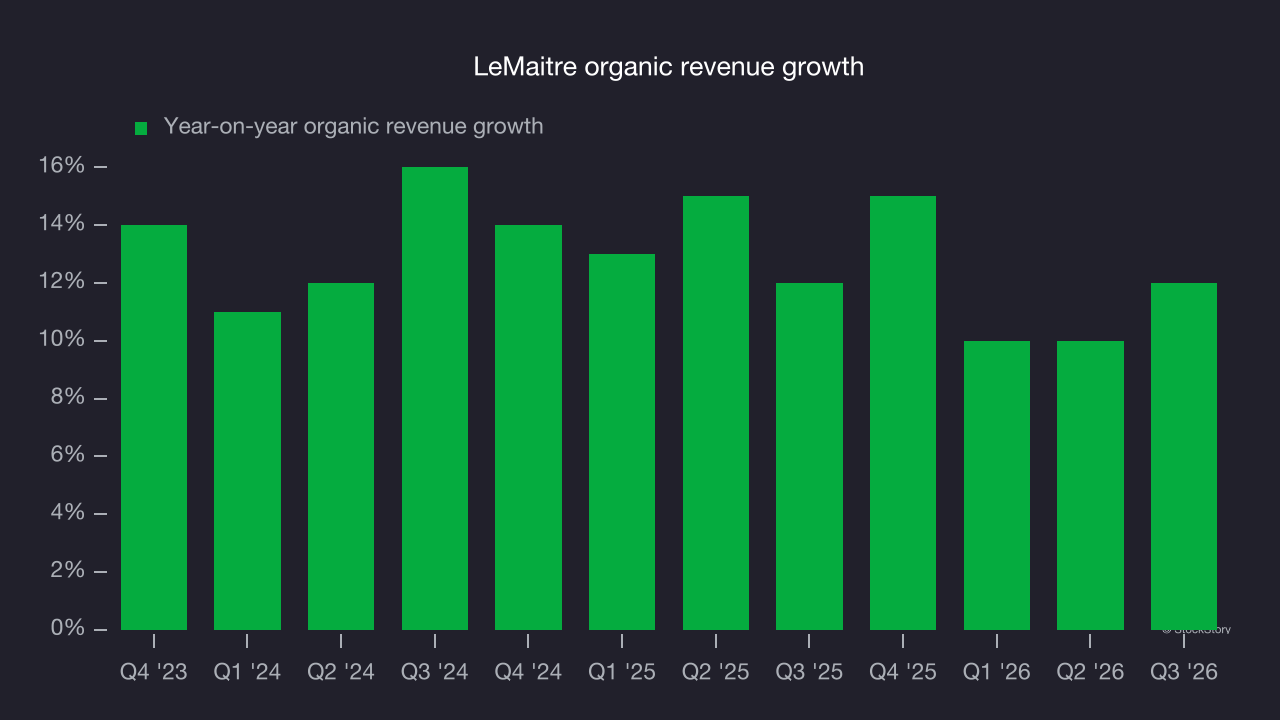
This quarter, LeMaitre reported year-on-year revenue growth of 11.3%, and its $67.97 million of revenue exceeded Wall Street’s consensus estimates by 0.9%. Company management is currently guiding for a 10% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 10.3% over the next 12 months, according to S&P, a slight deceleration versus the last two years. Despite the slowdown, this projection is healthy and indicates the market is forecasting success for its products and services.
Operating margin
LeMaitre has been an efficient company over the last five years. It was one of the more profitable businesses in the healthcare sector, with an average operating margin of 22.9%.
LeMaitre’s operating margin rose by 10.2 percentage points over the last five years, as its revenue growth provided operating leverage. More recently, the company’s trajectory has remained intact, as its margin has also increased by 4.4 percentage points on a two-year basis.
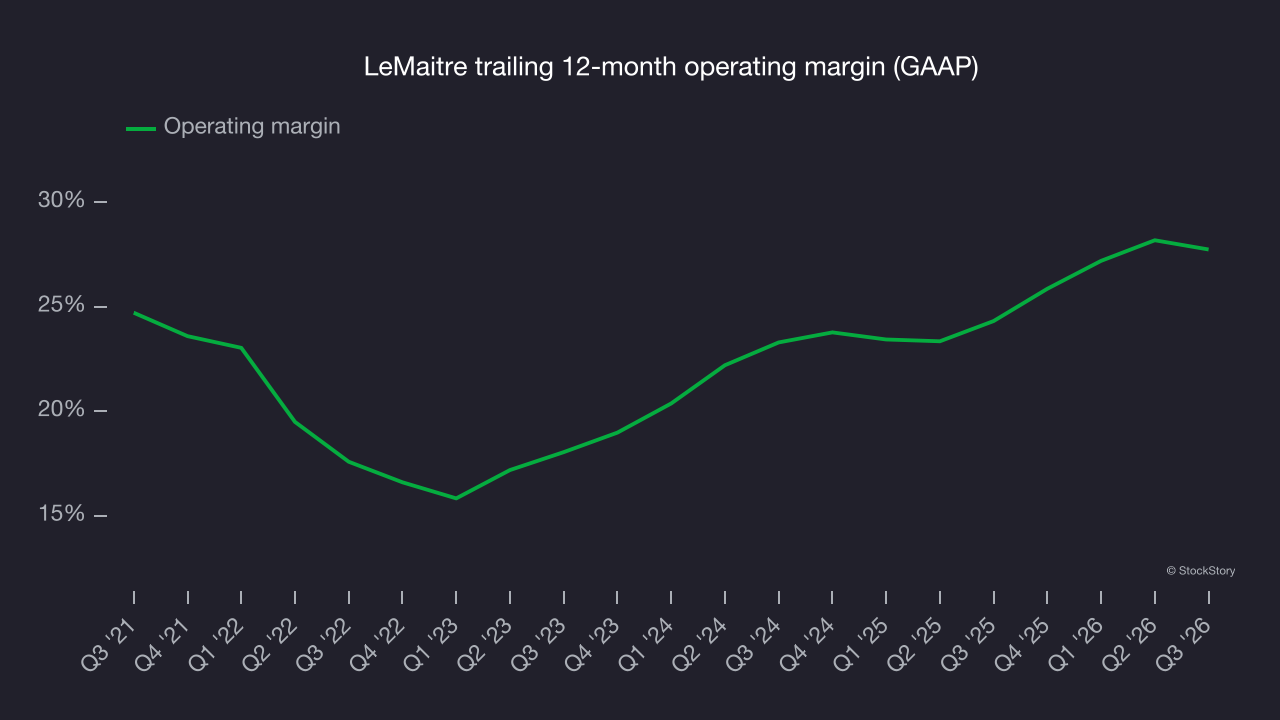
This quarter, LeMaitre generated an operating margin of 26%, down 1.7 percentage points year on year. This modest decline indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
LeMaitre’s EPS grew at a 15.8% compounded annual growth rate over the last five years, higher than its 12.1% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
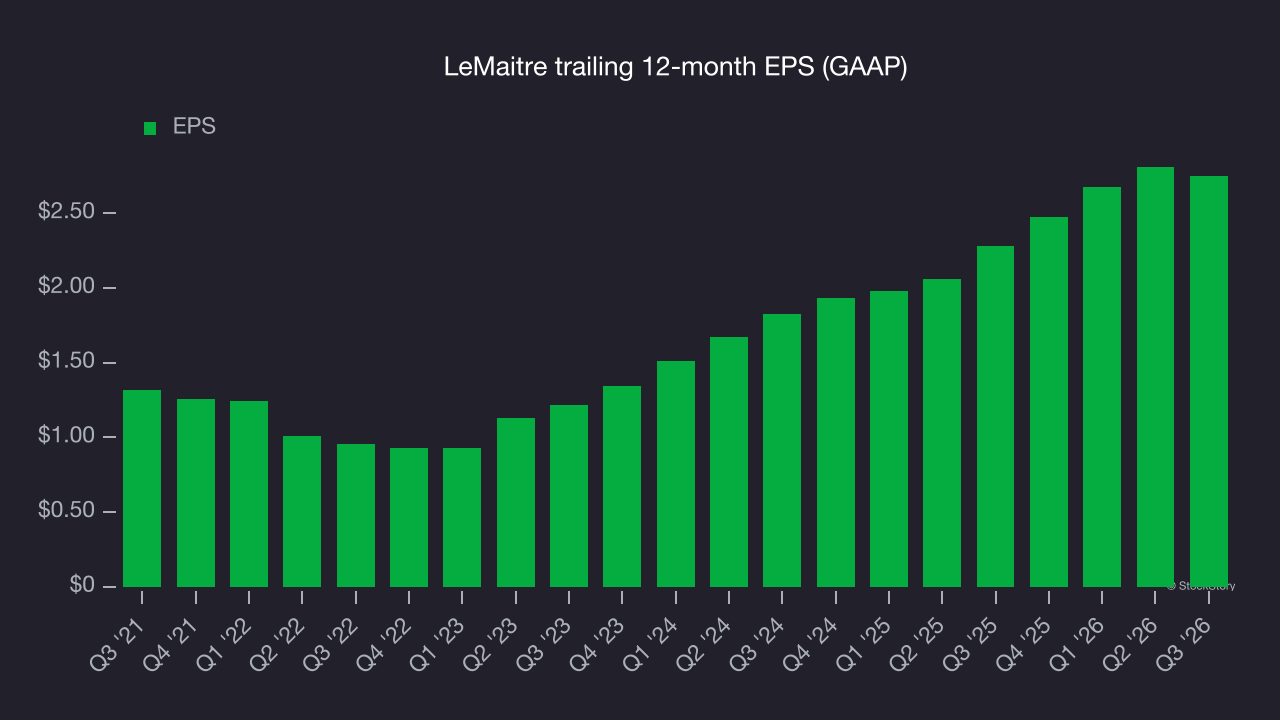
A closer look at LeMaitre’s quality of earnings helps explain its performance. As noted earlier, LeMaitre’s operating margin declined this quarter but expanded by 10.2 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, LeMaitre reported EPS of $0.65, down from $0.71 in the same quarter last year. This result missed analysts’ consensus estimates, but long-term EPS growth matters more than short-term movements. Over the next 12 months, Wall Street expects LeMaitre’s full-year EPS to grow 14.6% from $2.75 to $3.15, according to S&P.
Key takeaways from LeMaitre’s Q3 results
LeMaitre’s guidance fell short, with both its full-year EPS outlook and next-quarter revenue forecast missing Wall Street’s consensus estimates. Those shortfalls made this a weaker quarter despite narrow beats on organic revenue and total revenue. Shares plunged 11.9% to $77.39 immediately after the results.
LeMaitre’s earnings report left more to be desired. Assessing whether the stock offers an investment opportunity requires looking beyond this quarter. The latest results are only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. For more on LeMaitre, read our full research report here (it’s free).