Online insurance comparison site EverQuote (NASDAQ: EVER) will be reporting earnings this Monday after the bell. Here’s what you need to know.
EverQuote beat analysts’ revenue expectations last quarter, reporting revenues of $195.1 million, up 24.6% year on year. It was a strong quarter for the company, with an impressive beat of analysts’ EBITDA estimates.
Is EverQuote a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting EverQuote’s revenue to grow 16.5% year on year, slowing from the 20.3% increase it recorded in the same quarter last year.
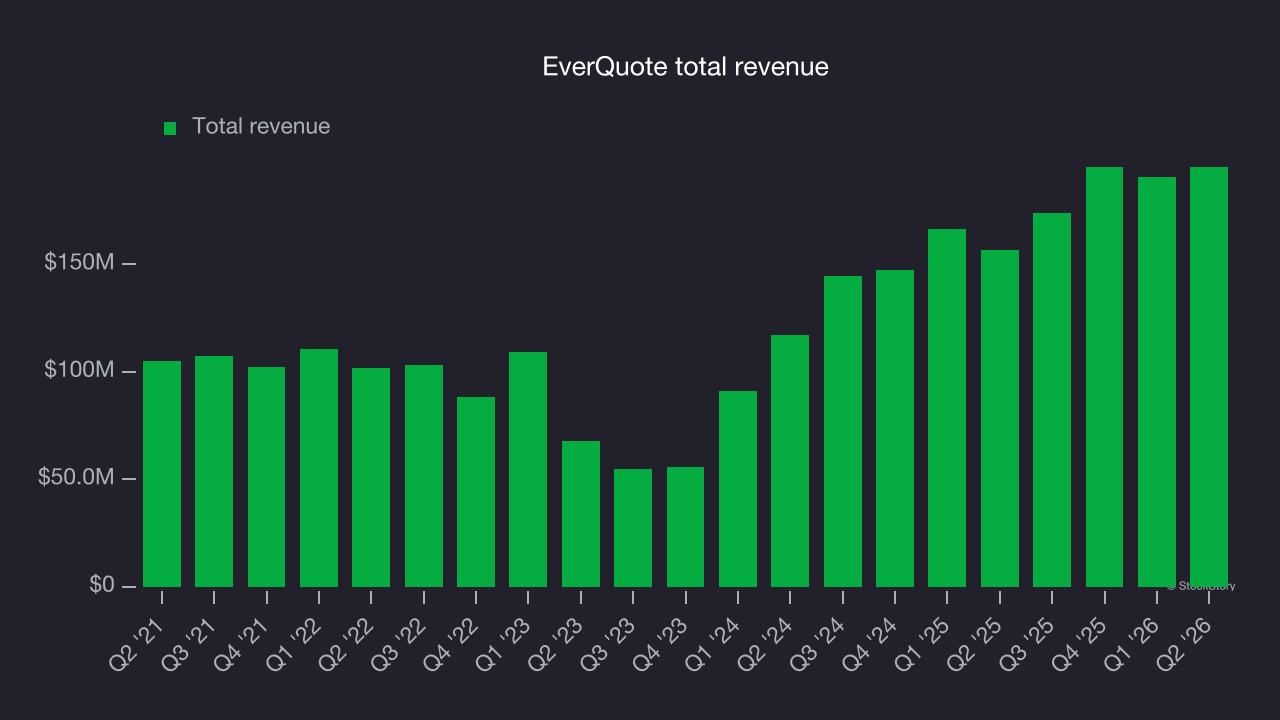
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. EverQuote rarely misses Wall Street’s revenue estimates.
Looking at EverQuote’s peers in the online marketplace segment, some have already reported their Q3 results, giving us a hint as to what we can expect. Etsy delivered year-on-year revenue growth of 10.9%, beating analysts’ expectations by 3.8%, and Instacart reported revenues up 16.6%, topping estimates by 2.1%. Etsy traded up 4.6% following the results while Instacart was down 3.4%.
Read our full analysis of Etsy’s results here and Instacart’s results here.
There has been positive sentiment among investors in the online marketplace segment, with share prices up 3.4% on average over the last month. EverQuote is up 25.8% during the same time and is heading into earnings with an average analyst price target of $29.50 (compared to the current share price of $24.53).
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.