Looking back on specialty finance stocks’ Q2 earnings, we examine this quarter’s best and worst performers, including Hercules Capital (NYSE: HTGC) and its peers.
Specialty finance companies provide targeted lending or financial services for specific industries or needs. They benefit from expertise in particular sectors, often reduced competition in specialized niches, and tailored underwriting that can yield higher margins. Challenges include concentration risk in specific industries, difficulty achieving scale efficiencies, and potential vulnerability during sector-specific downturns affecting their specialized markets.
The 9 specialty finance stocks we track reported a strong Q2. As a group, revenues missed analysts’ consensus estimates by 4.8%.
In light of this news, share prices of the companies have held steady. On average, they are relatively unchanged since the latest earnings results.
Hercules Capital (NYSE: HTGC)
Named after the mythological hero known for his strength, Hercules Capital (NYSE: HTGC) is a business development company that provides debt financing to venture capital-backed and growth-stage technology and life sciences companies.
Hercules Capital reported revenues of $149.1 million, up 8.5% year on year. This print exceeded analysts’ expectations by 1.7%. Overall, it was a satisfactory quarter for the company with a beat of analysts’ EPS estimates.
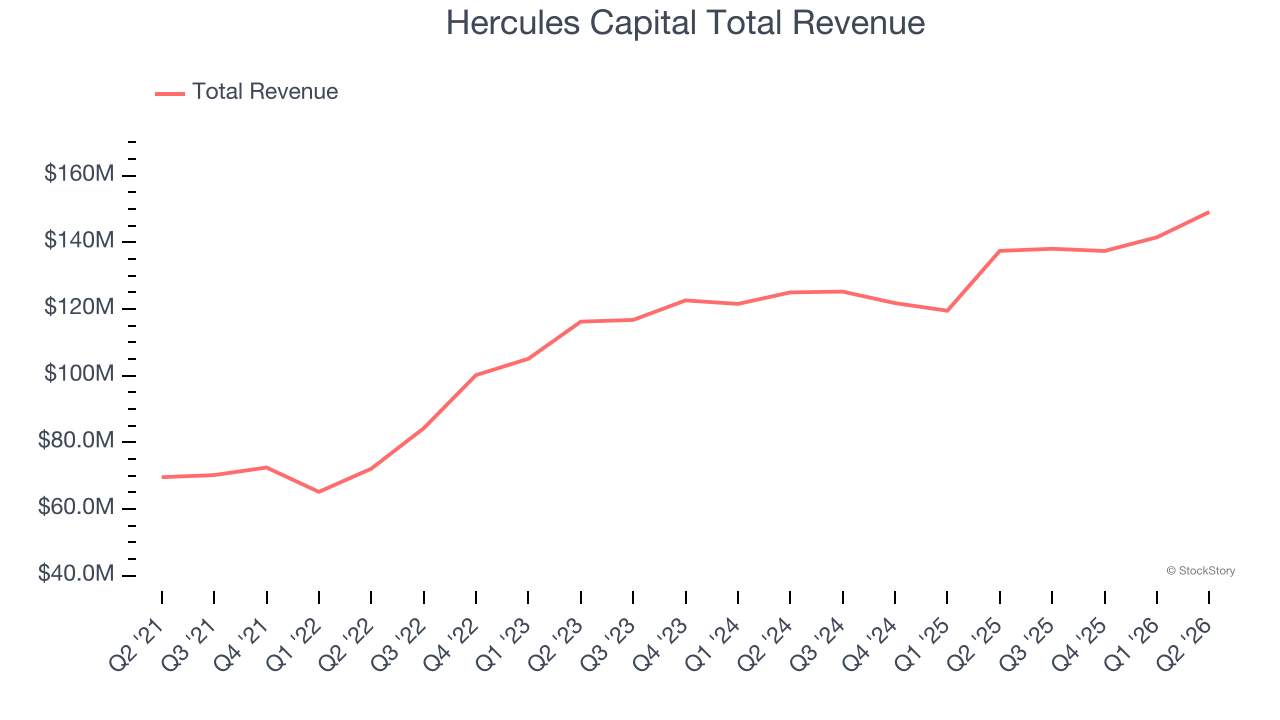
Interestingly, the stock is up 8.1% since reporting and currently trades at $17.23.
Is now the time to buy Hercules Capital? Access our full analysis of the earnings results here, it’s free.
Best Q2: Encore Capital Group (NASDAQ: ECPG)
Operating in the often misunderstood world of debt collection since 1999, Encore Capital Group (NASDAQ: ECPG) purchases portfolios of defaulted consumer debt at deep discounts and works with individuals to recover these obligations while helping them toward financial recovery.
Encore Capital Group reported revenues of $491.9 million, up 11.3% year on year, outperforming analysts’ expectations by 8.1%. The business had an exceptional quarter with a solid beat of analysts’ EBITDA estimates and a beat of analysts’ EPS estimates.
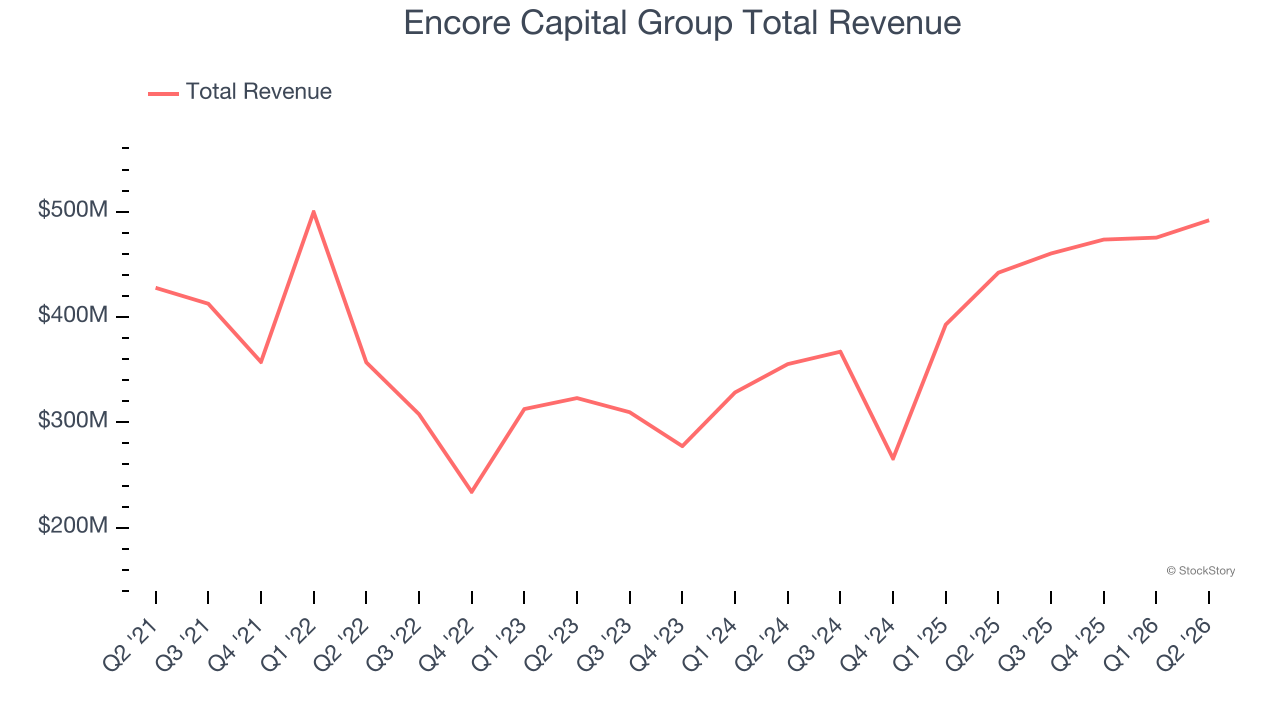
Encore Capital Group pulled off the biggest analyst estimate beat among its peers. The market seems happy with the results as the stock is up 10.6% since reporting. It currently trades at $102.50.
Is now the time to buy Encore Capital Group? Access our full analysis of the earnings results here, it’s free.
Slowest Q2: HA Sustainable Infrastructure Capital (NYSE: HASI)
With a proprietary "CarbonCount" metric that quantifies the environmental impact of each dollar invested, HA Sustainable Infrastructure Capital (NYSE: HASI) is an investment firm that finances and develops climate-positive infrastructure projects across renewable energy, energy efficiency, and ecological restoration.
HA Sustainable Infrastructure Capital reported revenues of $36.32 million, down 64.9% year on year, falling short of analysts’ expectations by 63.1%. It was a softer quarter as it posted a significant miss of analysts’ EBITDA estimates.
HA Sustainable Infrastructure Capital delivered the weakest performance against analyst estimates and slowest revenue growth of the whole group. As expected, the stock is down 3.6% since the results and currently trades at $36.88.
Read our full analysis of HA Sustainable Infrastructure Capital’s results here.
Sixth Street Specialty Lending (NYSE: TSLX)
Originally launched as TPG Specialty Lending before rebranding in 2020, Sixth Street Specialty Lending (NYSE: TSLX) is a business development company that provides customized financing solutions to middle-market companies across various industries.
Sixth Street Specialty Lending reported revenues of $97.84 million, down 14.9% year on year. This result topped analysts’ expectations by 3.3%. It was a strong quarter as it also recorded EPS in line with analysts’ estimates.
The stock is flat since reporting and currently trades at $17.85.
Read our full, actionable report on Sixth Street Specialty Lending here, it’s free.
Main Street Capital (NYSE: MAIN)
With a focus on building long-term partnerships rather than quick transactions, Main Street Capital (NYSE: MAIN) is a business development company that provides long-term debt and equity capital to lower middle market and middle market companies.
Main Street Capital reported revenues of $149.6 million, up 3.9% year on year. This number beat analysts’ expectations by 2.7%. Overall, it was a satisfactory quarter as it also put up EPS in line with analysts’ estimates.
The stock is down 1% since reporting and currently trades at $56.21.
Read our full, actionable report on Main Street Capital here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our 9 Best Market-Beating Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.