Over the past six months, Martin Marietta Materials’s stock price fell to $492.19. Shareholders have lost 14.8% of their capital, which is disappointing considering the S&P 500 has climbed by 16.4%. This might have investors contemplating their next move.
Is now the time to buy Martin Marietta Materials, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Martin Marietta Materials Not Exciting?
Even though the stock has become cheaper, we don’t have much confidence in Martin Marietta Materials. Here are three reasons we avoid MLM, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
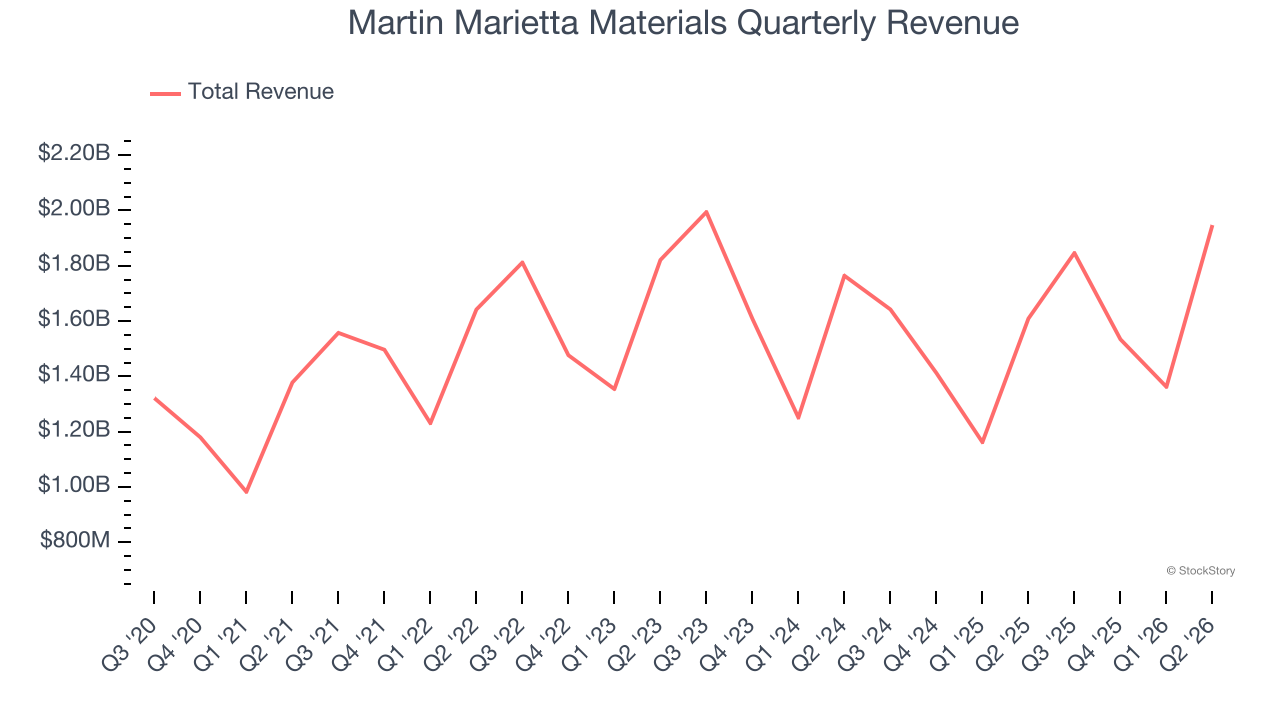
Reviewing a company’s long-term sales performance reveals insights into its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Regrettably, Martin Marietta Materials’s sales grew at a mediocre 6.6% compounded annual growth rate over the last five years. This fell short of our benchmark for the industrials sector.
2. EPS Growth Has Stalled Over the Last Two Years
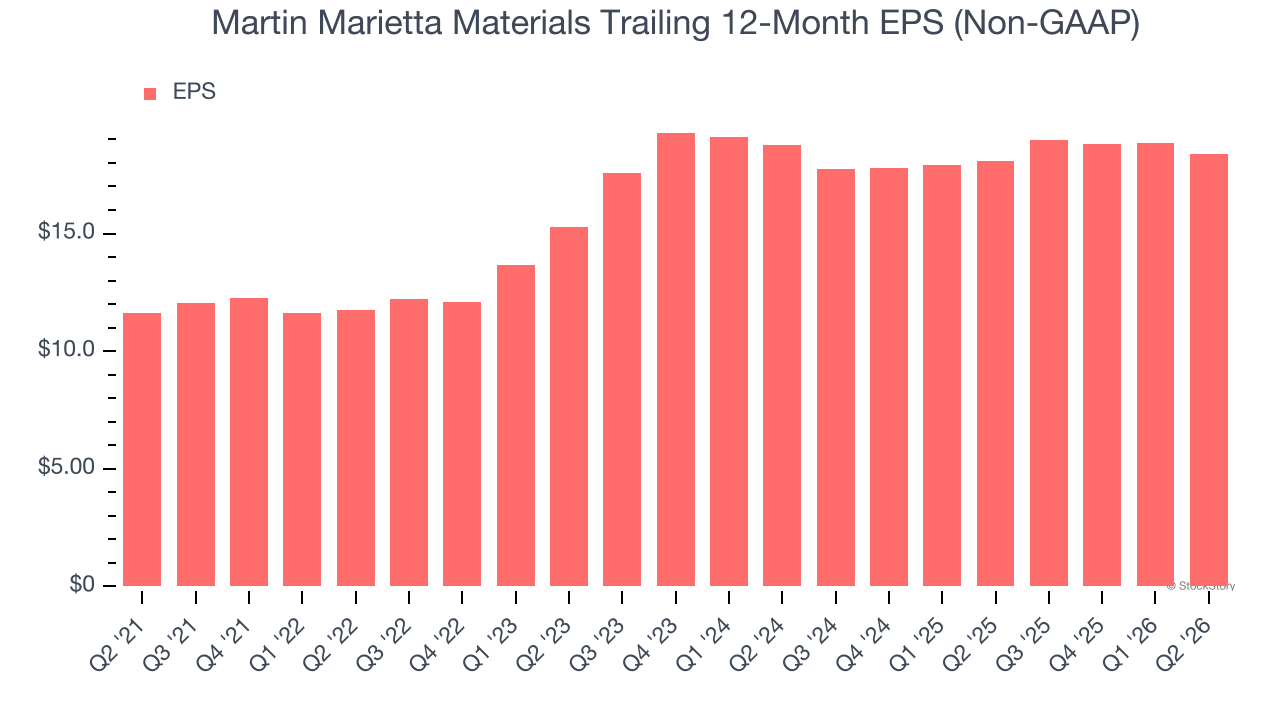
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
Martin Marietta Materials’s EPS was flat over the last two years, just like its revenue. This performance was underwhelming across the board.
3. Previous Growth Initiatives Haven’t Impressed
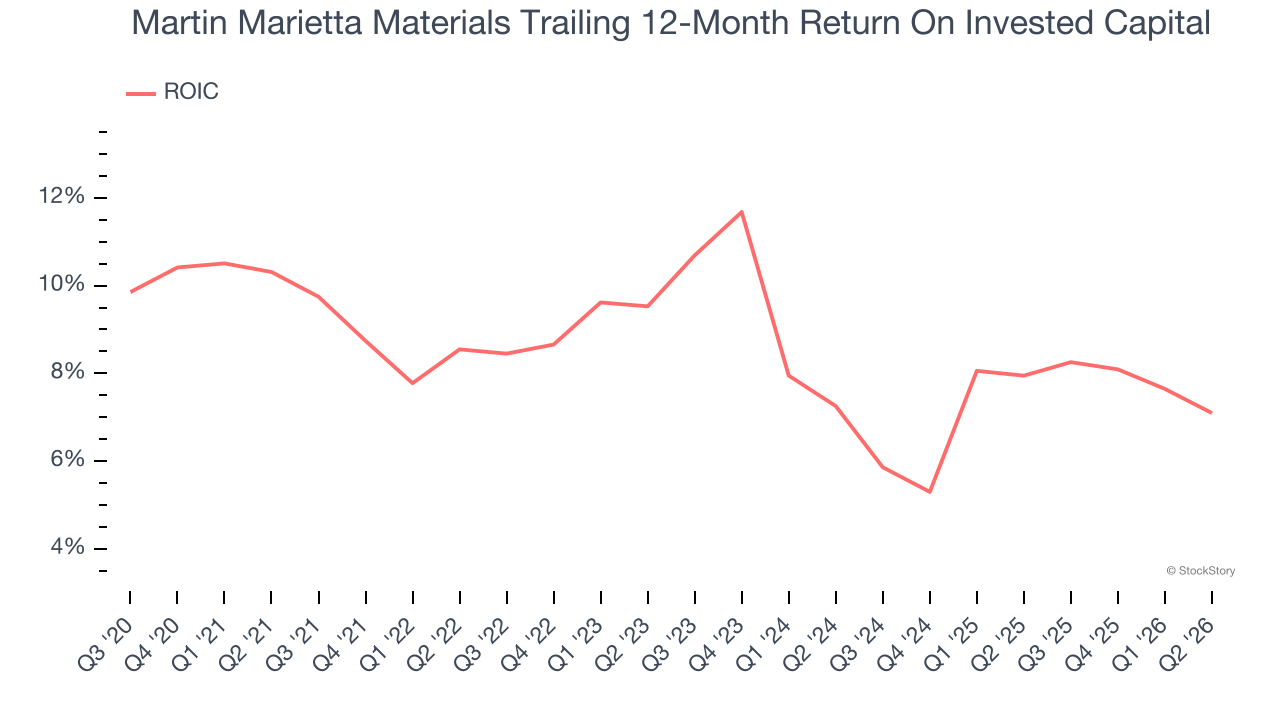
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Martin Marietta Materials historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 8.1%, somewhat low compared to the best industrials companies that consistently pump out 20%+.
Final Judgment
Martin Marietta Materials isn’t a terrible business, but it doesn’t pass our bar. Following the recent decline, the stock trades at 27.9× forward P/E (or $492.19 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - you can find more timely opportunities elsewhere. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.