Casella Waste Systems trades at $89.06 and has moved in lockstep with the market. Its shares have returned 14.2% over the last six months while the S&P 500 has gained 16.4%.
Is CWST a buy right now? Find out in our full research report, it’s free.
Why Does Casella Waste Systems Spark Debate?
Starting with the founder picking up garbage with a pickup truck he purchased using savings from high school, Casella (NASDAQ: CWST) offers waste management services for businesses, residents, and the government.
Two Positive Attributes:
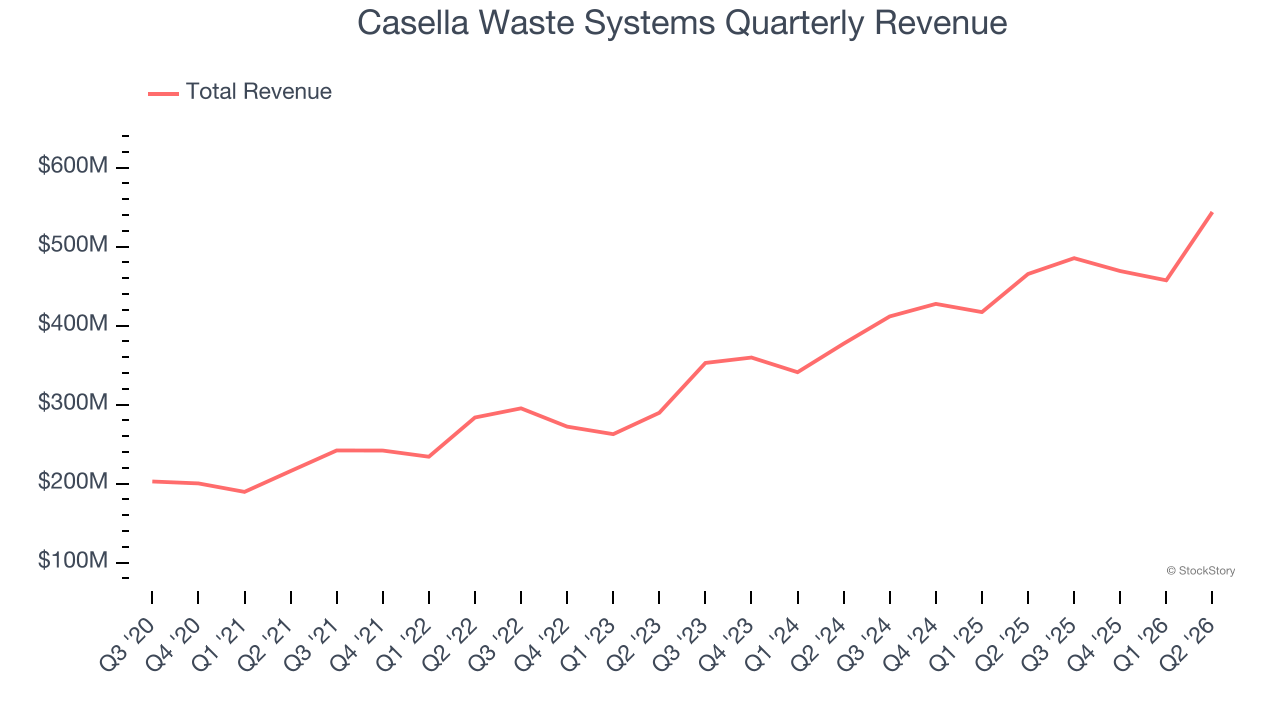
1. Skyrocketing Revenue Shows Strong Momentum
A company’s long-term sales performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Thankfully, Casella Waste Systems’s 19.3% annualized revenue growth over the last five years was incredible. Its growth beat the average industrials company and shows its offerings resonate with customers.
2. EPS Moving Up Steadily
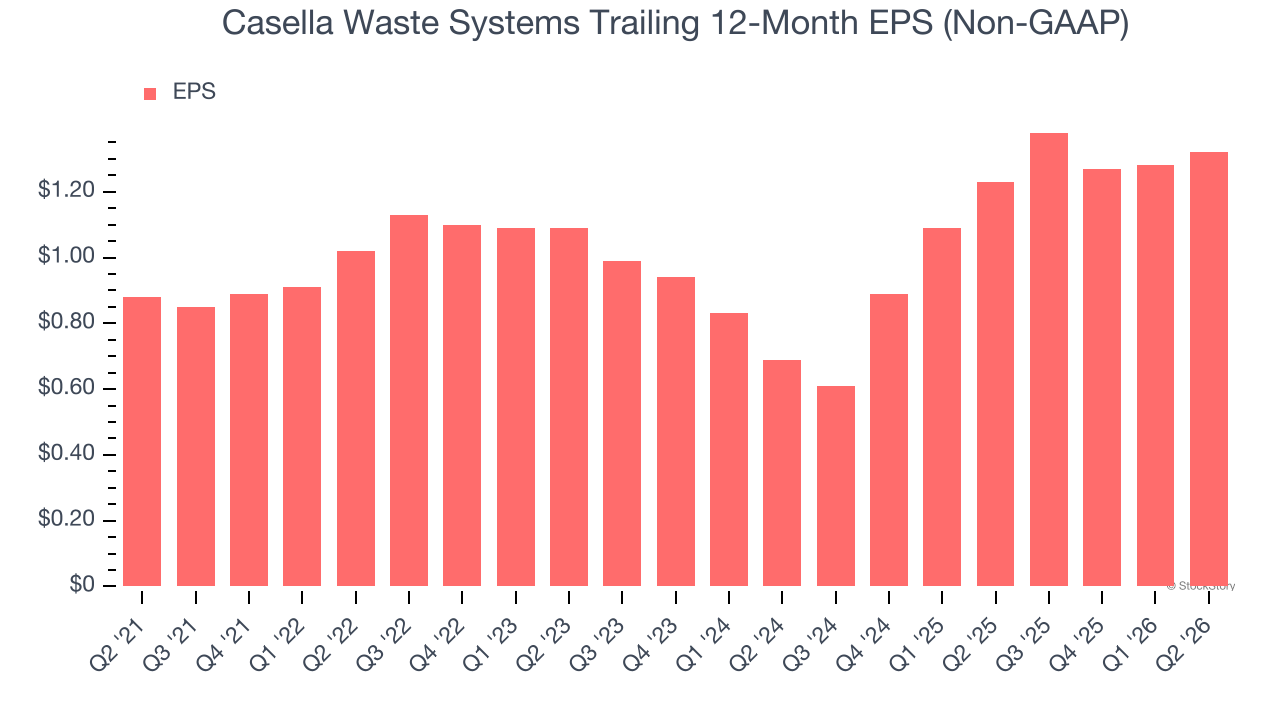
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Casella Waste Systems’s EPS grew at a decent 8.4% compounded annual growth rate over the last five years. This performance was better than most industrials businesses.
One Reason to Be Careful:
Shrinking Operating Margin
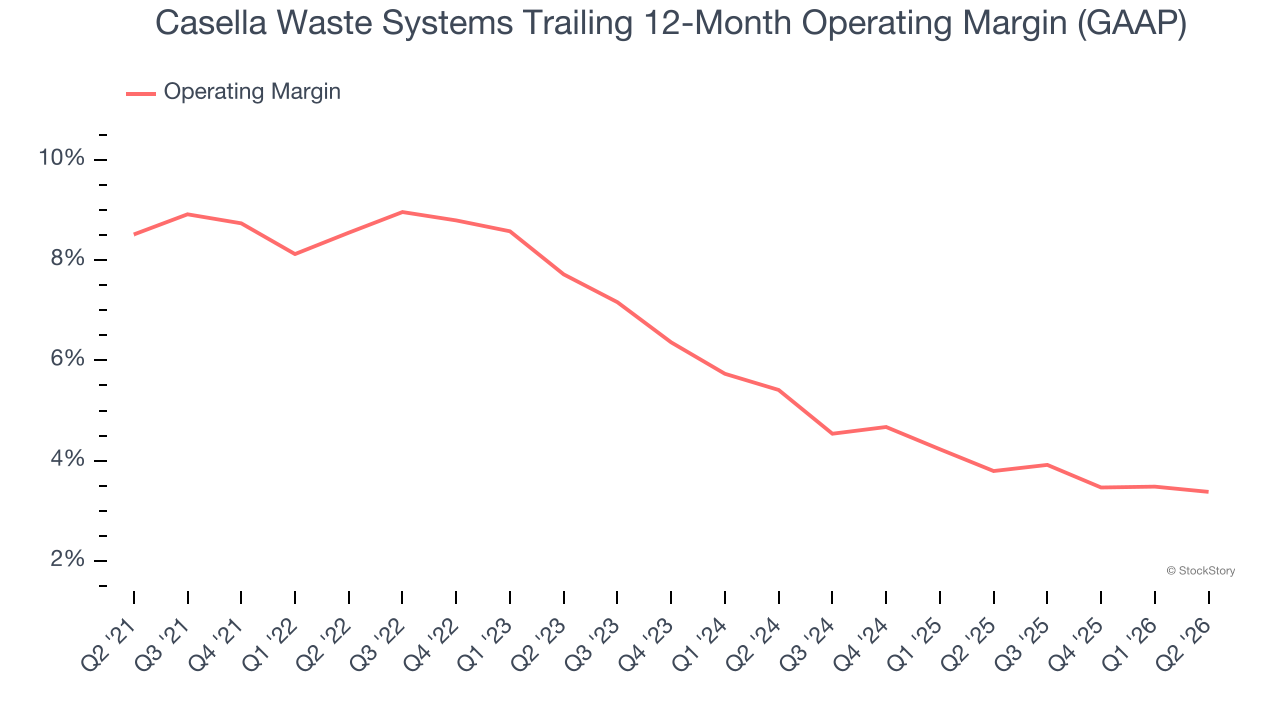
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Looking at the trend in its profitability, Casella Waste Systems’s operating margin decreased by 5.2 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Casella Waste Systems’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its operating margin for the trailing 12 months was 3.4%.
Final Judgment
Casella Waste Systems has huge potential even though it has some open questions. At $89.06 per share (or 71.3× forward P/E), is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Casella Waste Systems
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.