Since March 2026, Ulta has been in a holding pattern, posting a small return of 4.7% while floating around $540.44. The stock also fell short of the S&P 500’s 16.4% gain during that period.
Is now the time to buy ULTA? Or does the price properly account for its business quality and fundamentals? Find out in our full research report, it’s free.
Why Are We Positive on Ulta?
Offering high-end prestige brands as well as lower-priced, mass-market ones, Ulta Beauty (NASDAQ: ULTA) is an American retailer that sells makeup, skincare, haircare, and fragrance products.
1. Store Growth Signals an Offensive Strategy
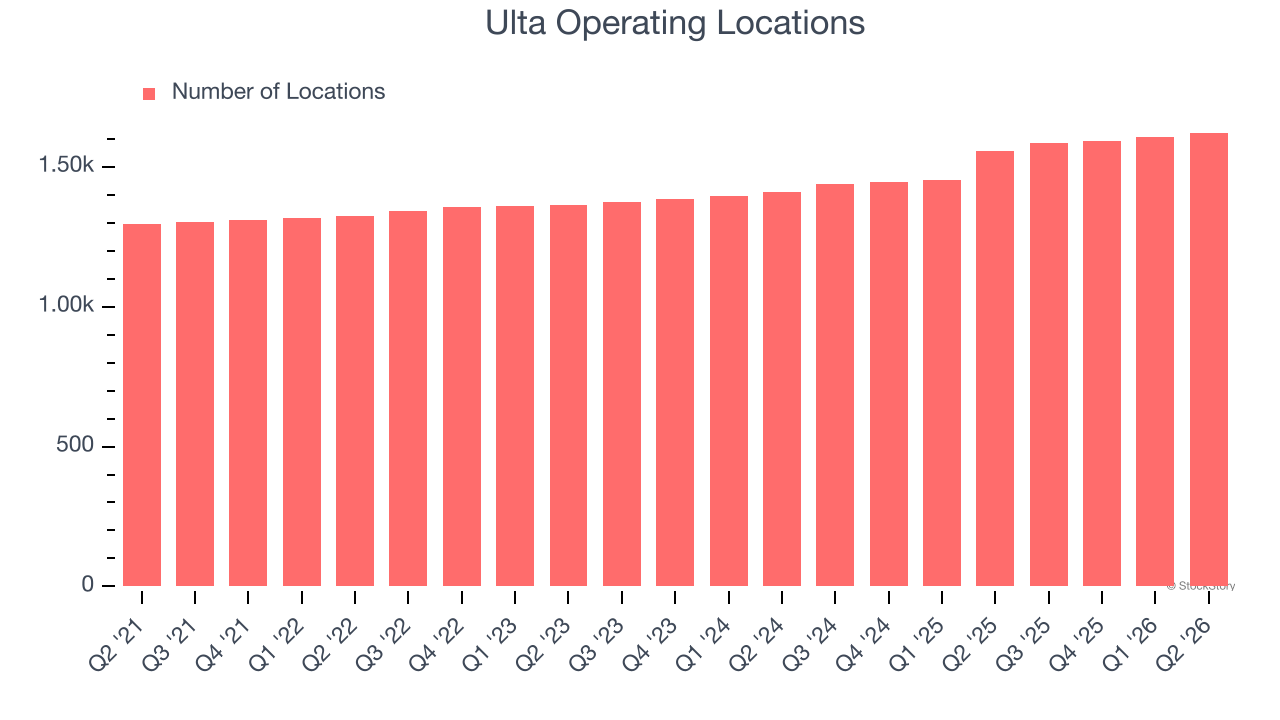
A retailer’s store count influences how much it can sell and how quickly revenue can grow.
Ulta sported 1,622 locations in the latest quarter. Over the last two years, it has opened new stores at a rapid clip by averaging 7.3% annual growth, among the fastest in the consumer retail sector. This gives it a chance to become a large, scaled business over time.
When a retailer opens new stores, it usually means it’s investing for growth because demand is greater than supply, especially in areas where consumers may not have a store within reasonable driving distance.
2. Surging Same-Store Sales Show Increasing Demand
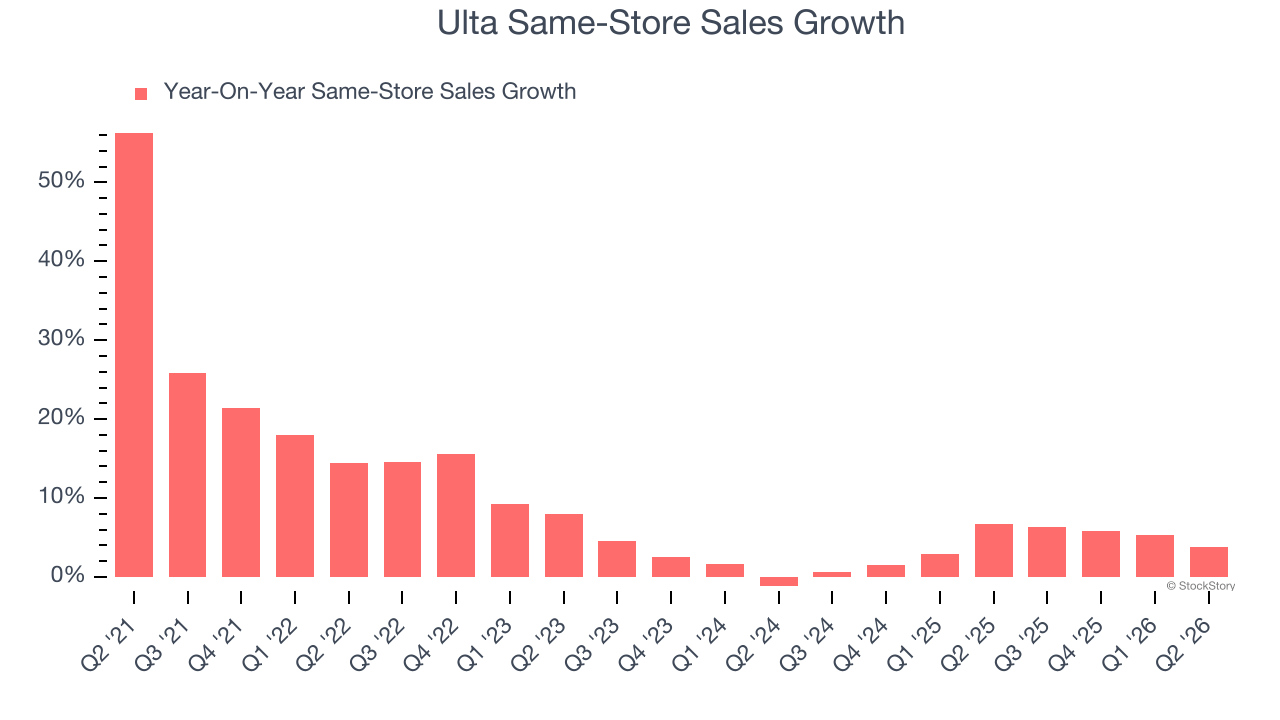
Same-store sales show the change in sales for a retailer’s e-commerce platform and brick-and-mortar shops that have existed for at least a year. This is a key performance indicator because it measures organic growth.
Ulta’s demand has been spectacular for a retailer over the last two years. On average, the company has increased its same-store sales by an impressive 4.1% per year.
3. Stellar ROIC Showcases Lucrative Growth Opportunities
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Ulta’s five-year average ROIC was 32%, placing it among the best consumer retail companies. This illustrates its management team’s ability to invest in highly profitable ventures and produce tangible results for shareholders.
Final Judgment
These are just a few reasons why we think Ulta is a great business. With its shares underperforming the market lately, the stock trades at 17.8× forward P/E (or $540.44 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.