Thermo Fisher’s 36.4% return over the past six months has outpaced the S&P 500 by 20.1%, and its stock price has climbed to $652.30 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Thermo Fisher, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Thermo Fisher Not Exciting?
We’re glad investors have benefited from the price increase, but we’re passing on Thermo Fisher for now. Here are three reasons why TMO doesn’t excite us, plus one stock we’d rather own.
1. Slow Organic Growth Suggests Waning Demand In Core Business
We can better understand Research Tools & Consumables companies by analyzing their organic revenue. This metric gives visibility into Thermo Fisher’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Thermo Fisher’s organic revenue averaged 2.4% year-on-year growth. This performance slightly lagged the sector and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 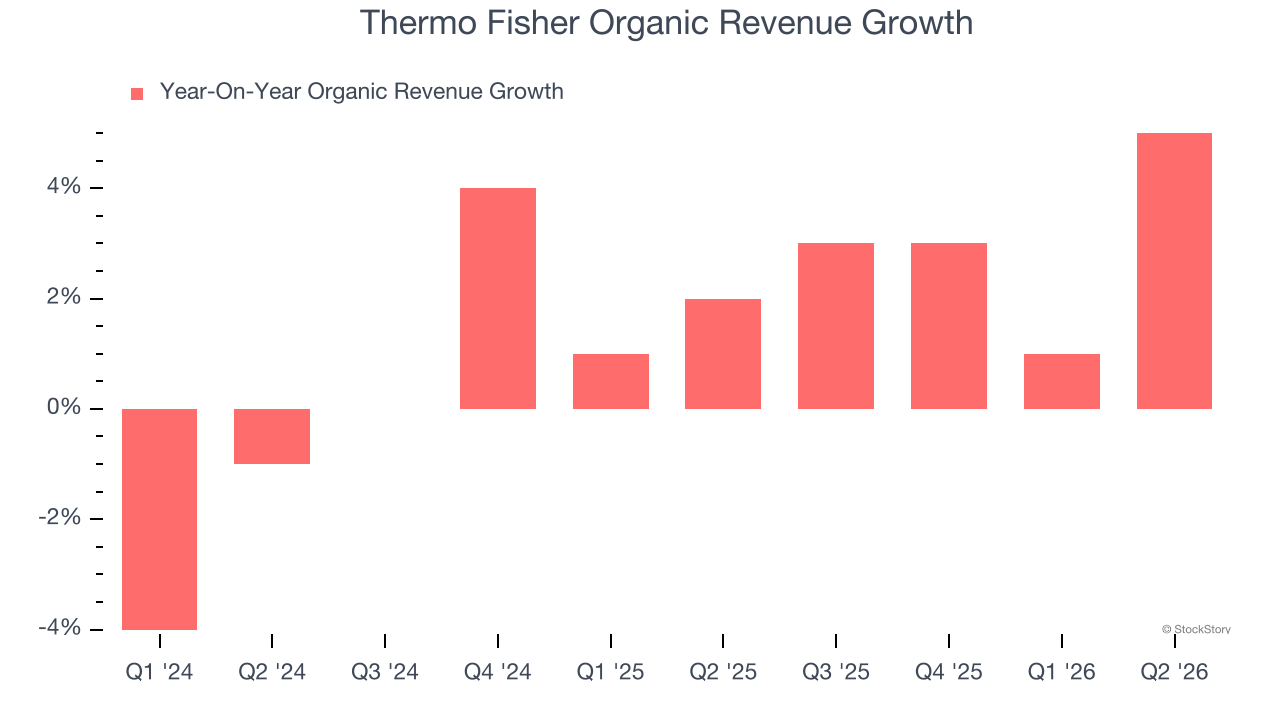
2. Shrinking Adjusted Operating Margin
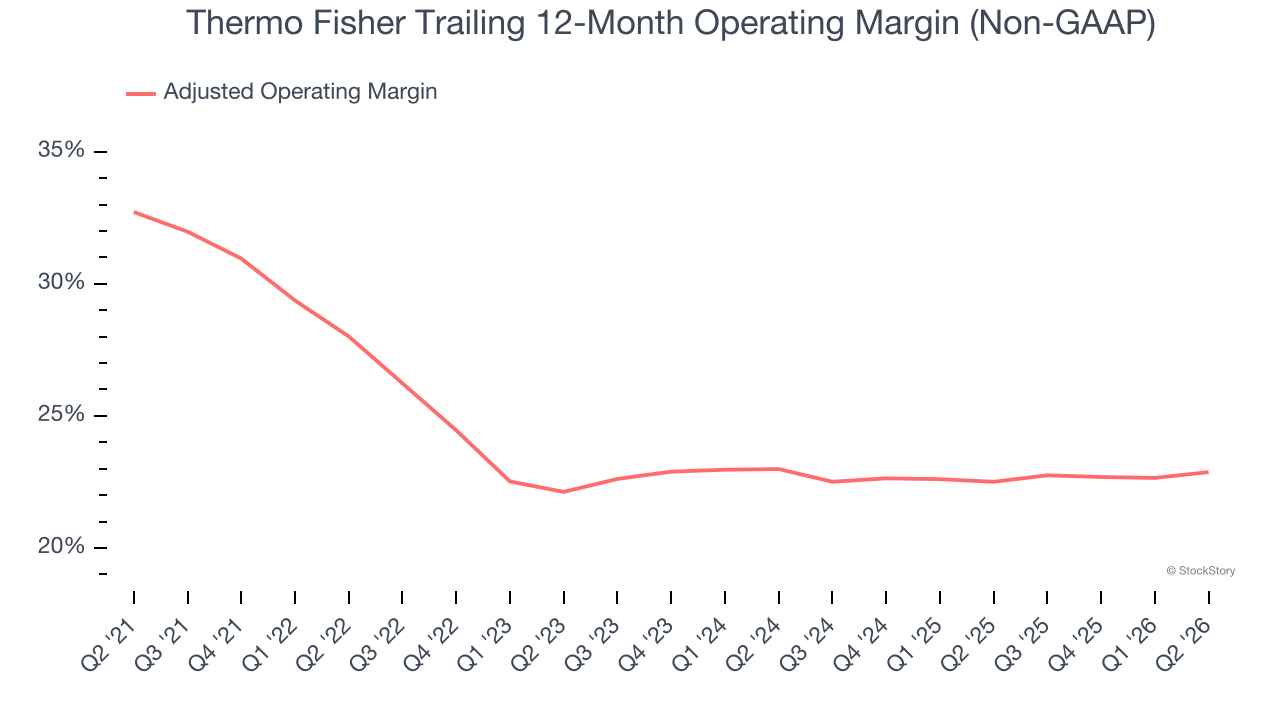
Adjusted operating margin is a key measure of profitability. Think of it as net income (the bottom line) excluding the impact of non-recurring expenses, taxes, and interest on debt - metrics less connected to business fundamentals.
Analyzing the trend in its profitability, Thermo Fisher’s adjusted operating margin decreased by 5.1 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its adjusted operating margin for the trailing 12 months was 22.9%.
3. EPS Trending Down
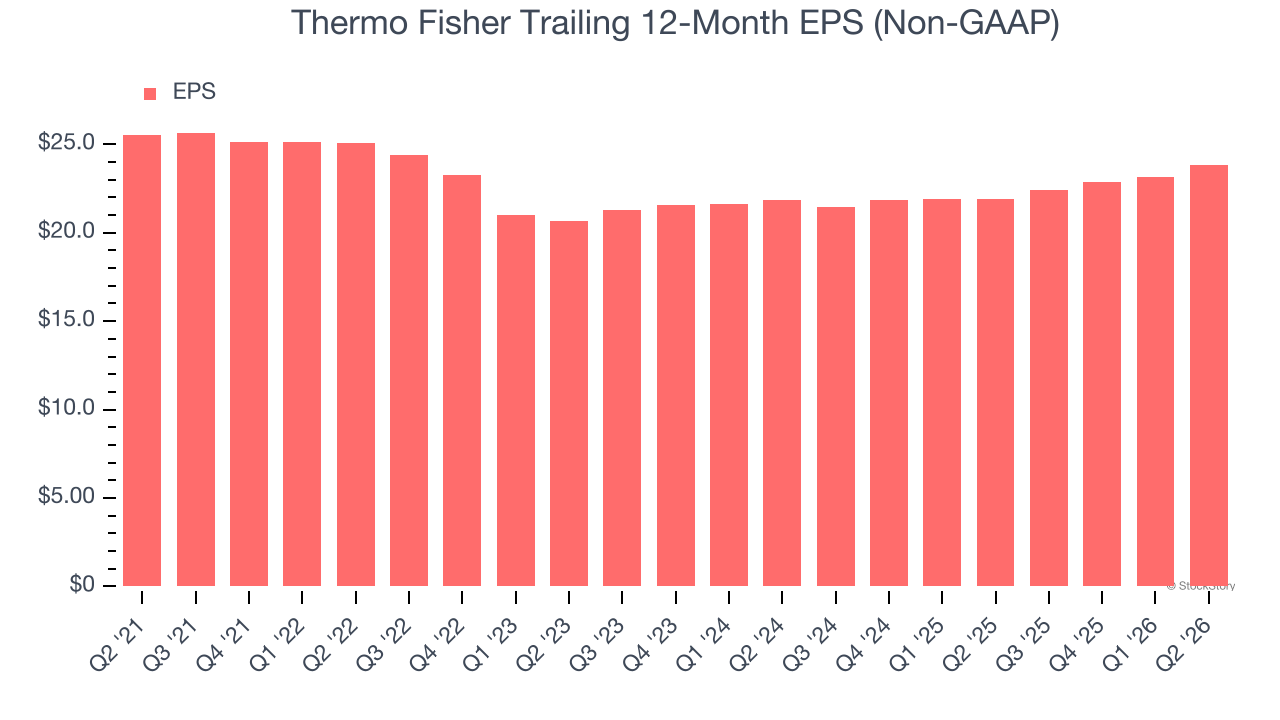
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for Thermo Fisher, its EPS declined by 1.4% annually over the last five years while its revenue grew by 3.9%. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
Thermo Fisher isn’t a terrible business, but it doesn’t pass our quality test. With its shares beating the market recently, the stock trades at 25.1× forward P/E (or $652.30 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are superior stocks to buy right now. We’d suggest looking at one of our top software and edge computing picks.
Stocks We Like More Than Thermo Fisher
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.