What a brutal six months it’s been for ProPetro. The stock has dropped 25.6% and now trades at $10.80, rattling many shareholders. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is there a buying opportunity in ProPetro, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think ProPetro Will Underperform?
Even with the cheaper entry price, we’re cautious about ProPetro. Here are three reasons why there are better opportunities than PUMP, plus one stock we’d rather own.
1. Fewer Distribution Channels Limit Its Ceiling
The scale of a company’s revenue base is an important lens through which to view the topline, as it signals whether a producer has gone from a vulnerable commodity taker into a durable operating platform. Larger producers generate revenue across many wells, pads, takeaway routes, and geographies rather than relying on a single field or drilling program.
ProPetro’s $1.16 billion of revenue in the last year is pretty small for the industry, suggesting the company is a subscale business in an industry where scale matters.
2. Low Gross Margin Reveals Weak Structural Profitability
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer (“rock” quality, takeaway, operating costs) or not.
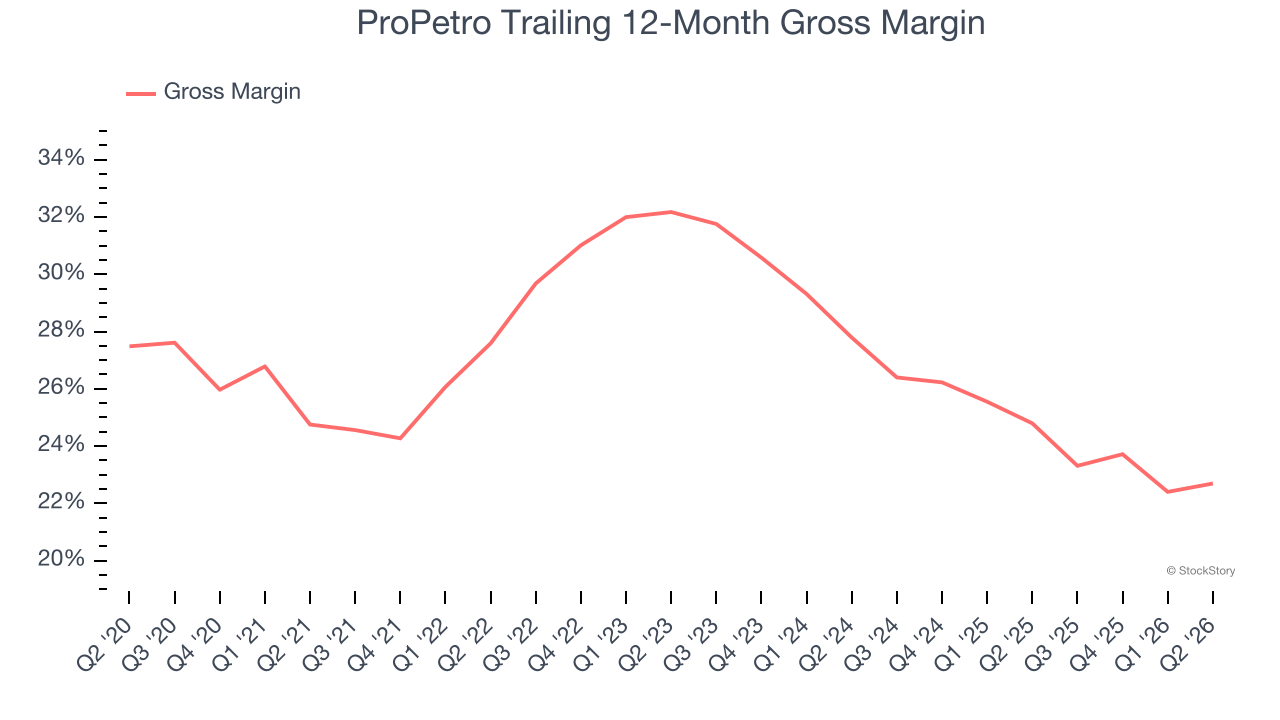
ProPetro, which averaged 27.3% gross margin over the last five years, exhibited bottom-tier unit economics in the sector. It means the company will struggle at higher commodity prices than peers with better gross margins.
3. Shrinking EBITDA Margin
Adjusted EBITDA margin is an important measure of profitability for the sector and accounts for the gross margins and operating costs mentioned previously. Unlike operating margin, it is not distorted by accounting conventions around reserves, drilling costs, and assumptions on commodity consumption from the well or basin. Adjusted EBITDA highlights the economic reality of how much cash the rock produces before the capital structure (debt service) and the drilling budget (capex) are considered.
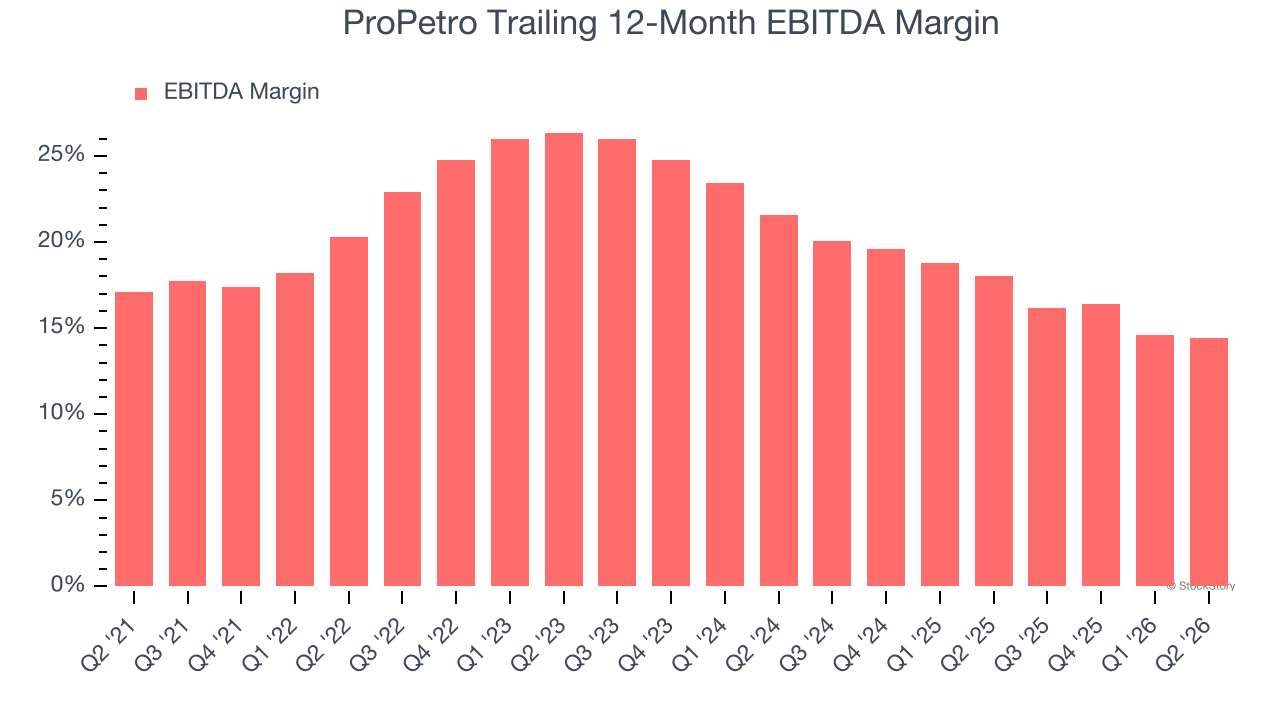
Analyzing the trend in its profitability, ProPetro’s EBITDA margin decreased by 5.9 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. ProPetro’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its EBITDA margin for the trailing 12 months was 14.4%.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of ProPetro, we’ll be cheering from the sidelines. After the recent drawdown, the stock trades at 58.5× forward P/E (or $10.80 per share). This multiple tells us a lot of good news is priced in - we think there are better stocks to buy right now. We’d suggest looking at a top digital advertising platform riding the creator economy.
Stocks We Would Buy Instead of ProPetro
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.