Over the last six months, Granite Ridge Resources’s shares have sunk to $4.91, producing a disappointing 8.7% loss - a stark contrast to the S&P 500’s 16.4% gain. This might have investors contemplating their next move.
Is now the time to buy Granite Ridge Resources, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Granite Ridge Resources Not Exciting?
Despite the more favorable entry price, we don’t have much confidence in Granite Ridge Resources. Here are three reasons why there are better opportunities than GRNT, plus one stock we’d rather own.
1. Fewer Distribution Channels Limit Its Ceiling
The size of the revenue base is a way to assess topline, and it tells an investor whether an Energy producer has crossed the line between being a more vulnerable commodity taker and a durable operating platform. Scaled businesses tend to produce and generate revenue from many wells, pads, takeaway routes, and geographies, not just a single field or drilling program.
Granite Ridge Resources’s $495.7 million of revenue in the last year is pretty small for the industry, suggesting the company hasn’t hit a level of diversification where investors can sleep easy at night.
2. Shrinking EBITDA Margin
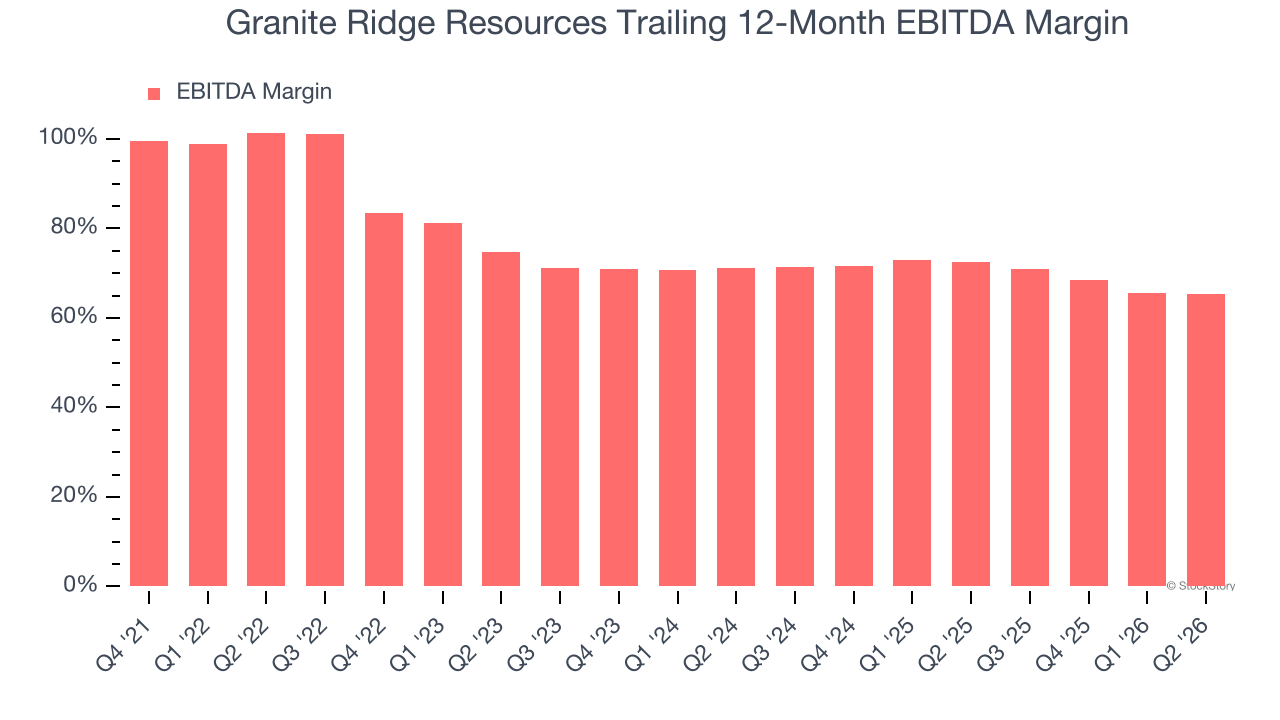
Adjusted EBITDA margin captures the true operating profitability of an energy producer by removing accounting noise around depletion and capitalized drilling costs. It reveals how much cash the asset base generates before capital structure and reinvestment requirements shape reported earnings.
Analyzing the trend in its profitability, Granite Ridge Resources’s EBITDA margin decreased by 36 percentage points over the last year. Even though its historical margin was healthy, shareholders will want to see Granite Ridge Resources become more profitable in the future. Its EBITDA margin for the trailing 12 months was 65.4%.
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
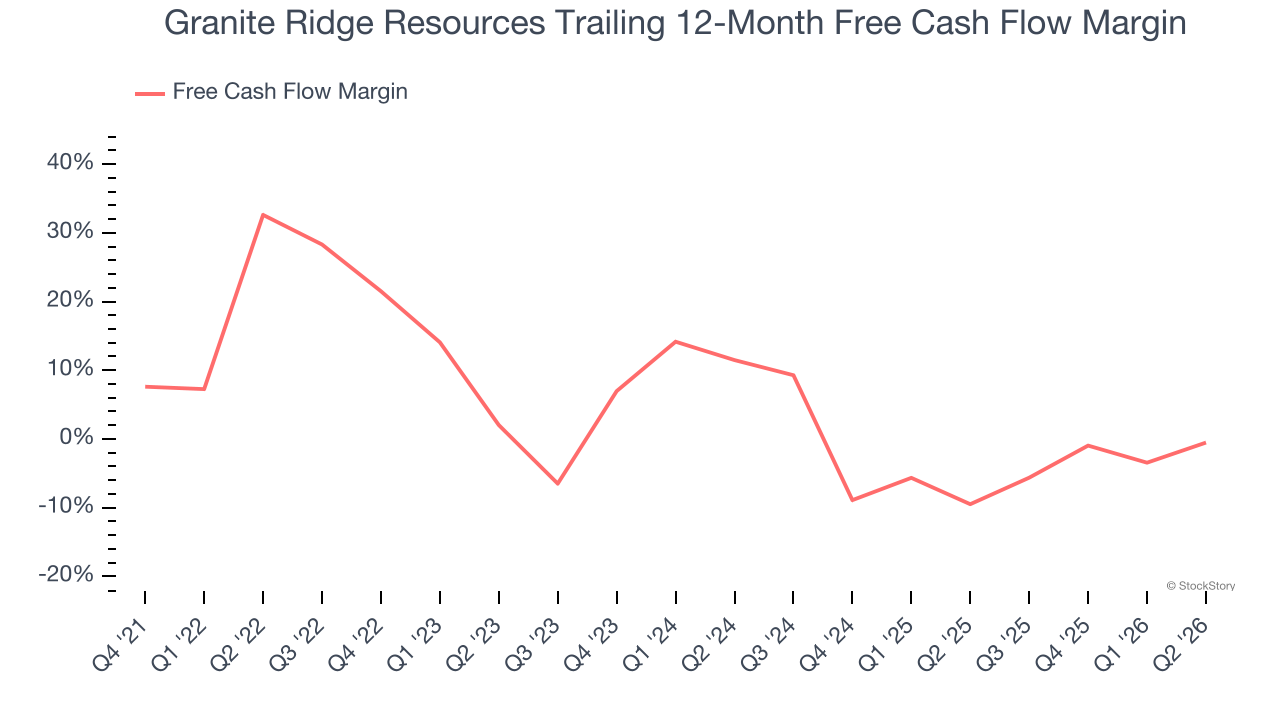
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Granite Ridge Resources has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 6.6%, below what we’d expect for an upstream and integrated energy business.
Final Judgment
Granite Ridge Resources isn’t a terrible business, but it doesn’t pass our bar. Following the recent decline, the stock trades at 8.3× forward P/E (or $4.91 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re pretty confident there are more exciting stocks to buy at the moment. We’d recommend looking at one of our top digital advertising picks.
Stocks We Would Buy Instead of Granite Ridge Resources
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.