Workiva has followed the market’s trajectory closely, rising in tandem with the S&P 500 over the past six months. The stock has climbed by 19.2% to $73.18 per share while the index has gained 16.4%.
Is now a good time to buy WK? Find out in our full research report, it’s free.
Why Do Investors Watch WK Stock?
Nicknamed "the Excel killer" by some finance professionals for its ability to eliminate spreadsheet chaos, Workiva (NYSE: WK) provides a cloud-based platform that enables organizations to streamline financial reporting, ESG, and compliance processes with connected data and automation.
Three Positive Attributes:
1. ARR Surges as Recurring Revenue Flows In
While reported revenue for a software company can include low-margin items like implementation fees, annual recurring revenue (ARR) is a sum of the next 12 months of contracted revenue purely from software subscriptions, or the high-margin, predictable revenue streams that make SaaS businesses so valuable.
Workiva’s ARR punched in at $945.2 million in Q2, and over the last four quarters, its year-on-year growth averaged 21.1%. This performance was impressive and shows that customers are willing to take multi-year bets on the company’s technology. Its growth also makes Workiva a more predictable business, a tailwind for its valuation as investors typically prefer businesses with recurring revenue. 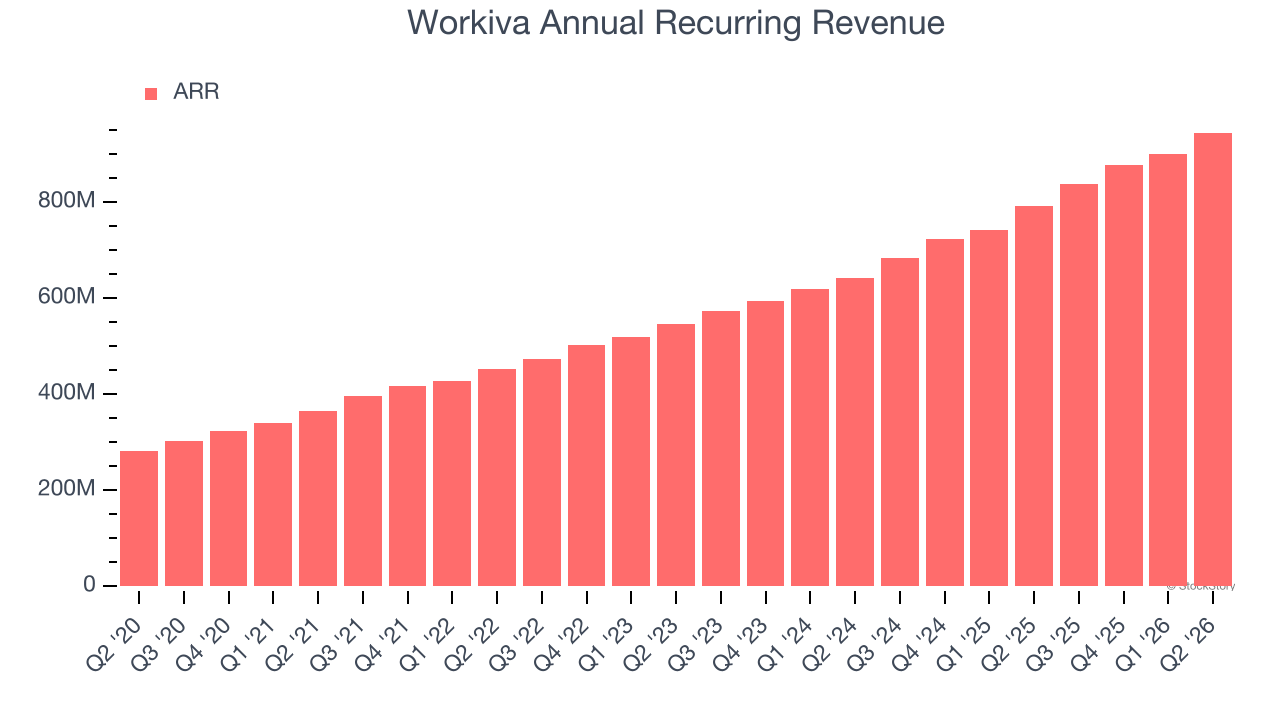
2. Elite Gross Margin Powers Best-In-Class Business Model
Software is eating the world. It’s one of our favorite business models because once you develop the product, it usually doesn’t cost much to provide it as an ongoing service. These minimal costs can include servers, licenses, and certain personnel.
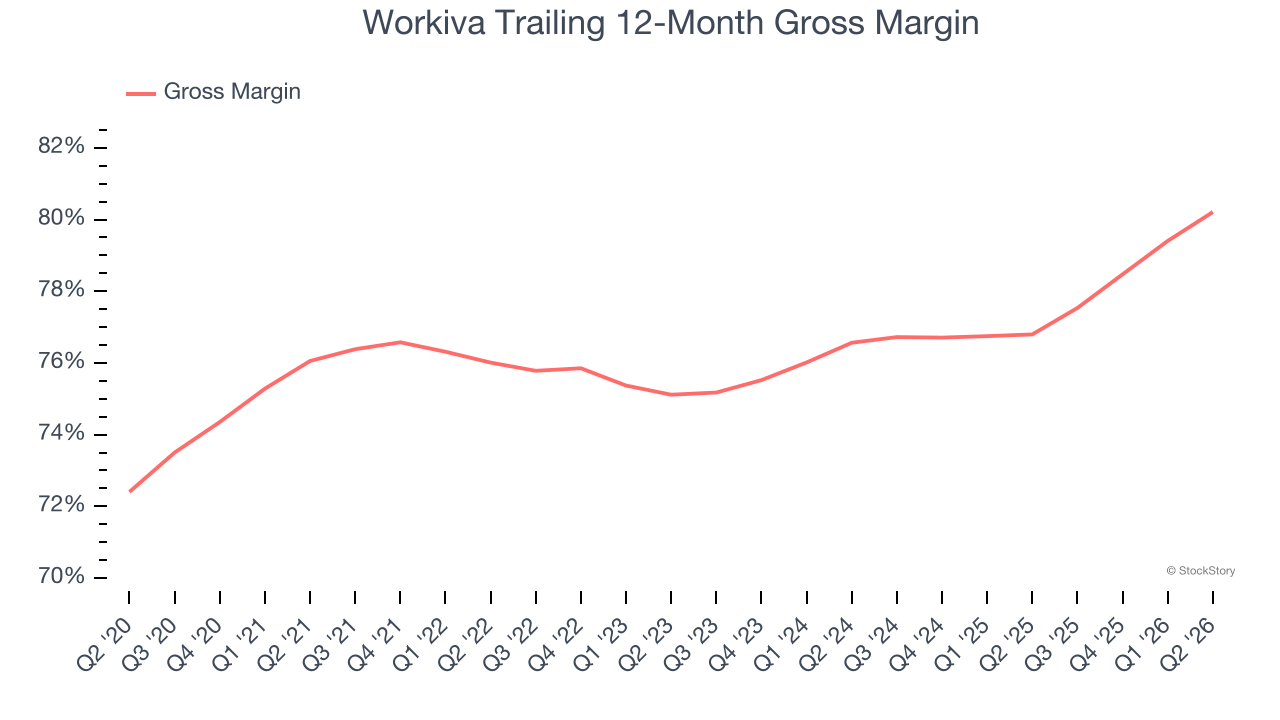
Workiva’s robust unit economics are better than the broader software industry, an output of its asset-lite business model and pricing power. They also enable the company to fund large investments in new products and sales during periods of rapid growth to achieve outsized profits at scale. As you can see below, it averaged an excellent 80.2% gross margin over the last year. That means Workiva only paid its providers $19.79 for every $100 in revenue.
The market not only cares about gross margin levels but also how they change over time because expansion creates firepower for profitability and free cash generation. Workiva has seen gross margins improve by 3.6 percentage points over the last 2 years, which is very good in the software space.
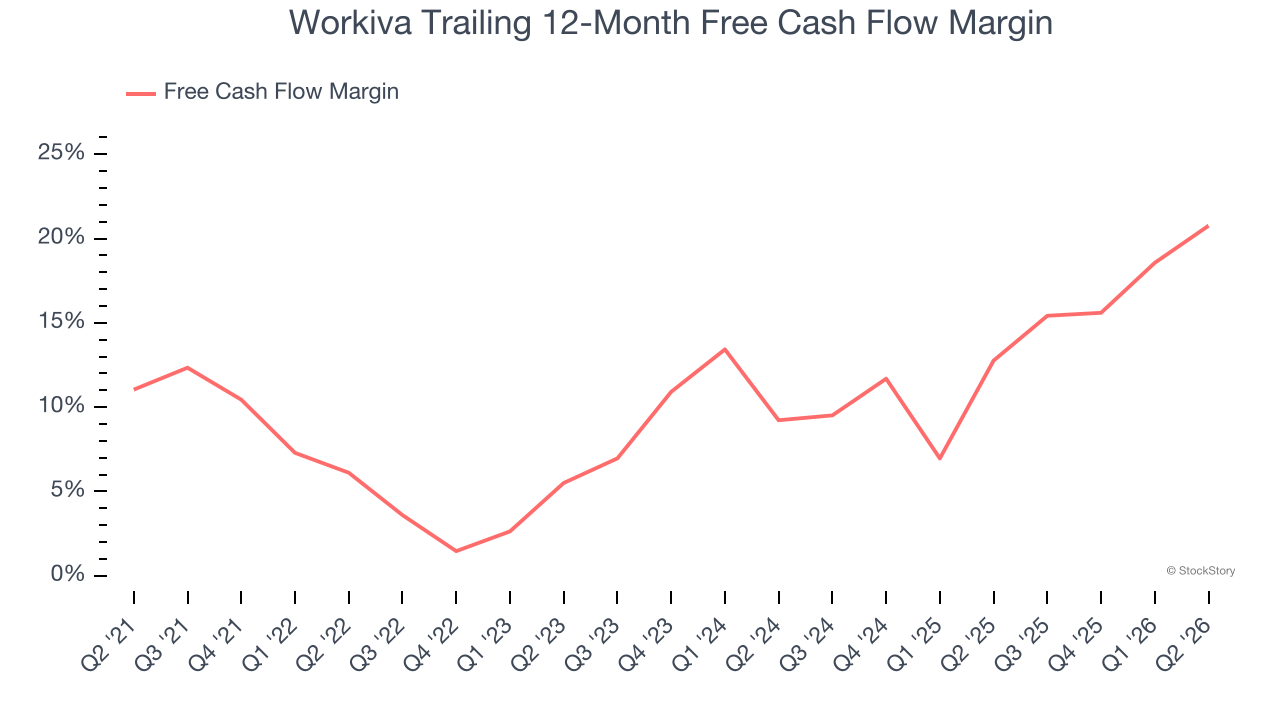
3. Impressive Free Cash Flow Margin Opens Growth Opportunities
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Workiva has shown impressive cash profitability, driven by its attractive business model and cost-effective customer acquisition strategy that give it the option to invest in new products and services rather than sales and marketing. The company’s free cash flow margin averaged 20.8% over the last year, better than the broader software sector.
Final Judgment
Workiva is an interesting business with potential. At $73.18 per share (or 3.7× forward price-to-sales), is now the right time to buy the stock? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Workiva
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.