Genco has had an impressive run over the past six months as its shares have beaten the S&P 500 by 9.4%. The stock now trades at $27.99, marking a 25.7% gain. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy Genco, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Genco Will Underperform?
We’re happy investors have made money, but we’re sitting this one out for now. Here are three reasons we avoid GNK, plus one stock we’d rather own.
1. Inability to Grow owned vessels Points to Weak Demand
Revenue growth can be broken down into changes in price and volume (for companies like Genco, our preferred volume metric is owned vessels). While both are important, the latter is the most critical to analyze because prices have a ceiling.
Over the last two years, Genco failed to grow its owned vessels, which came in at 43 in the latest quarter. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Genco might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 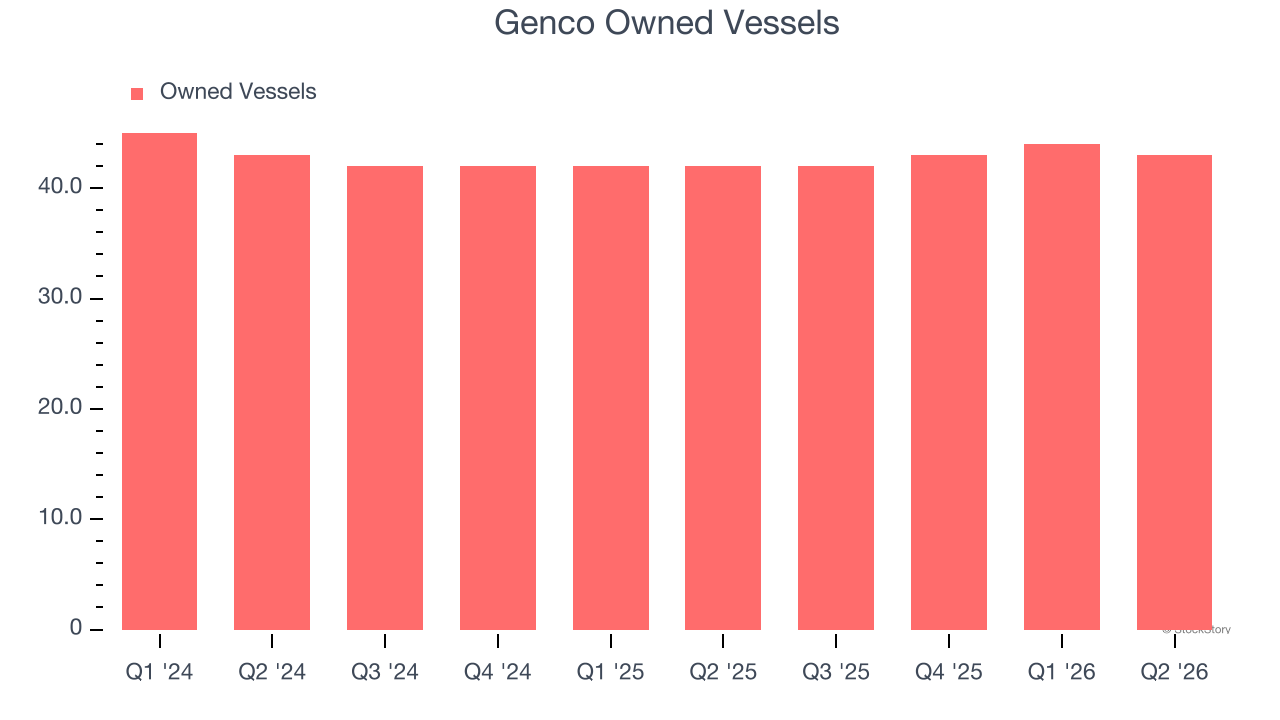
2. EPS Barely Growing
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
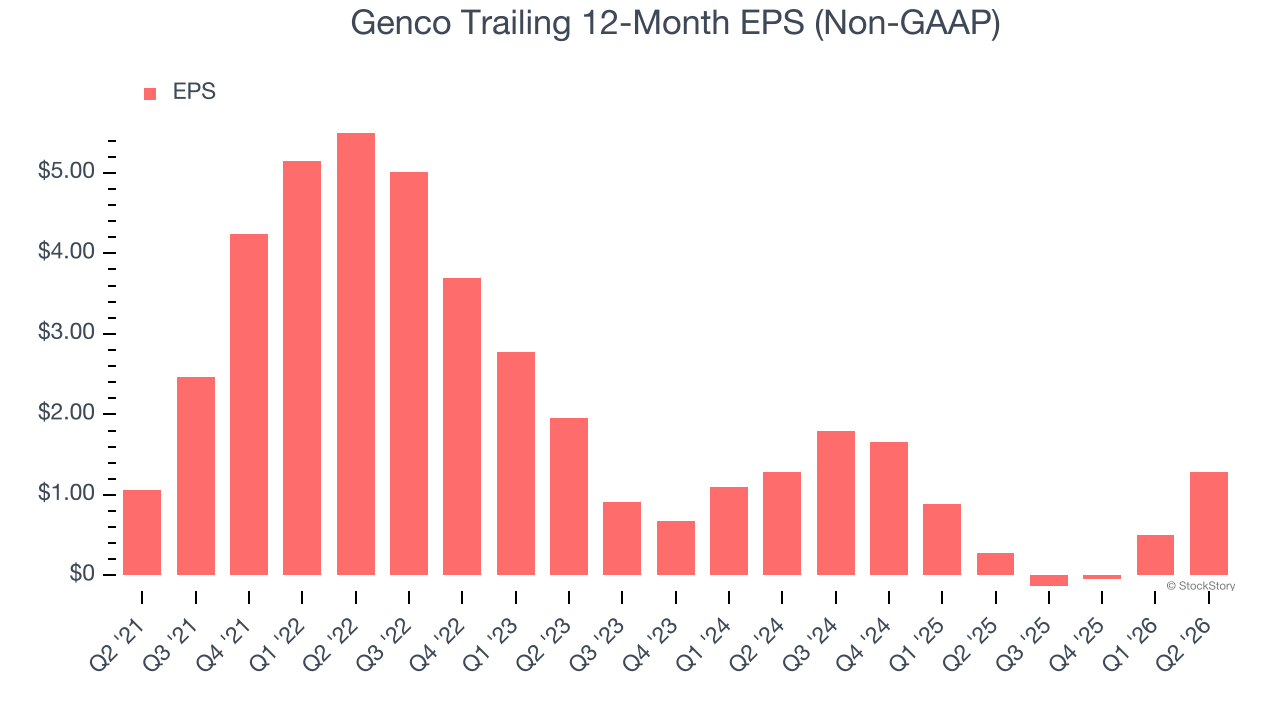
Genco’s unimpressive 4% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
3. Free Cash Flow Margin Dropping
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
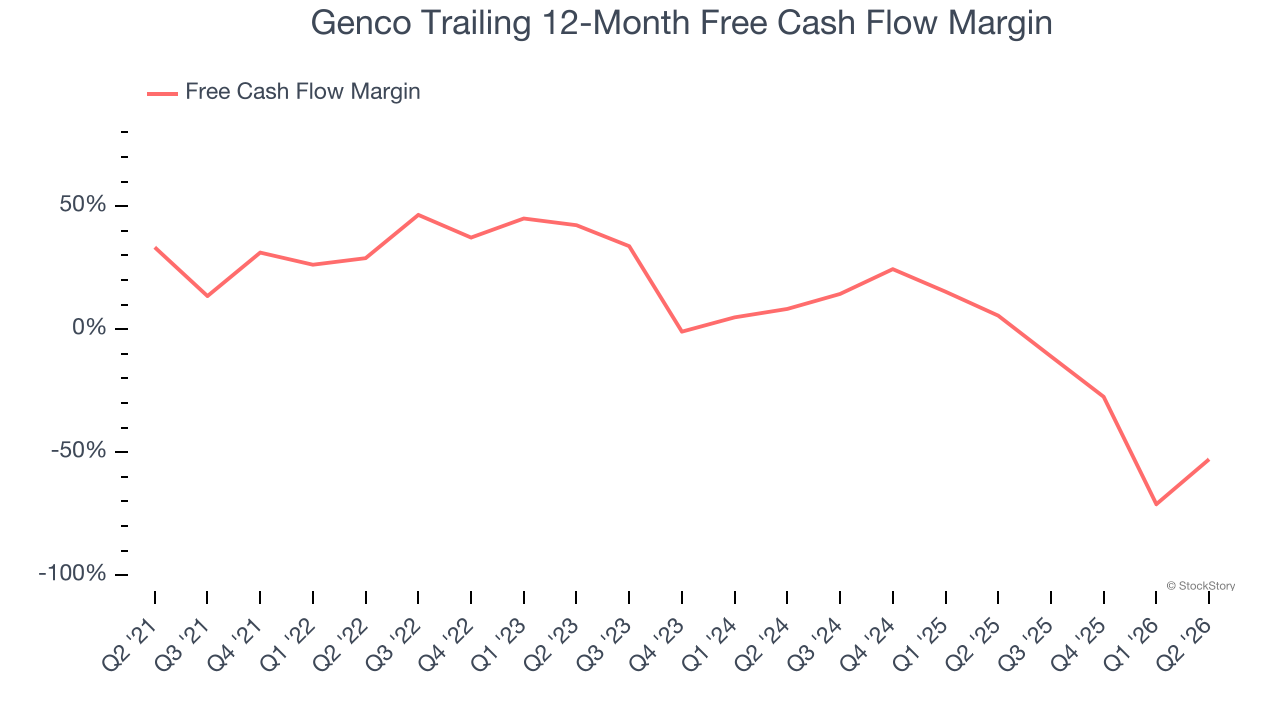
As you can see below, Genco’s margin dropped by 81.8 percentage points over the last five years. If its declines continue, it could signal increasing investment needs and capital intensity. Genco’s free cash flow margin for the trailing 12 months was negative 52.8%.
Final Judgment
We cheer for all companies making their customers lives easier, but in the case of Genco, we’ll be cheering from the sidelines. With its shares outperforming the market lately, the stock trades at 12.1× forward P/E (or $27.99 per share). This valuation multiple is fair, but we don’t have much confidence in the company. There are superior stocks to buy right now. We’d recommend looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.