1st Source’s 26.1% return over the past six months has outpaced the S&P 500 by 9.8%, and its stock price has climbed to $85.89 per share. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now still a good time to buy SRCE? Or are investors being too optimistic? Find out in our full research report, it’s free.
Why Does 1st Source Spark Debate?
Tracing its roots back to 1863 during the Civil War era, 1st Source Corporation (NASDAQ: SRCE) is a regional bank holding company that provides commercial, consumer, specialty finance, and wealth management services across Indiana, Michigan, and Florida.
Two Things to Like:
1. Increasing Net Interest Margin Juices Financials
The net interest margin (NIM) is a key profitability indicator that measures the difference between what a bank earns on its loans and what it pays on its deposits. This metric measures how efficiently it can generate income from its core lending activities.
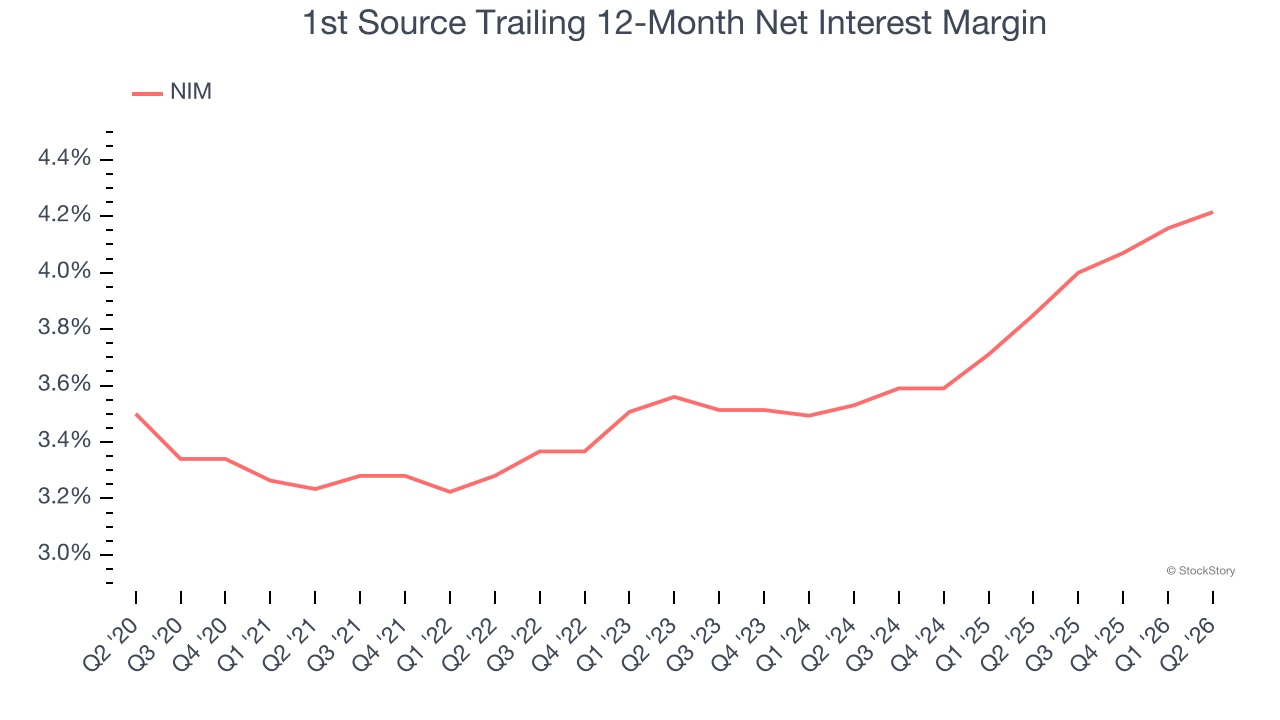
Over the past two years, 1st Source’s net interest margin averaged 4.1%, climbing by 68.5 basis points (100 basis points = 1 percentage point) over that period.
This expansion was a tailwind for its net interest income, and while prevailing interest rates matter the most for industry net interest margins, banks that consistently increase this figure generally boast higher-earning loan books (all else equal such as the risk of those loans) or provide differentiated services that give them the ability to charge higher rates (pricing power).
2. Growing TBVPS Reflects Strong Asset Base
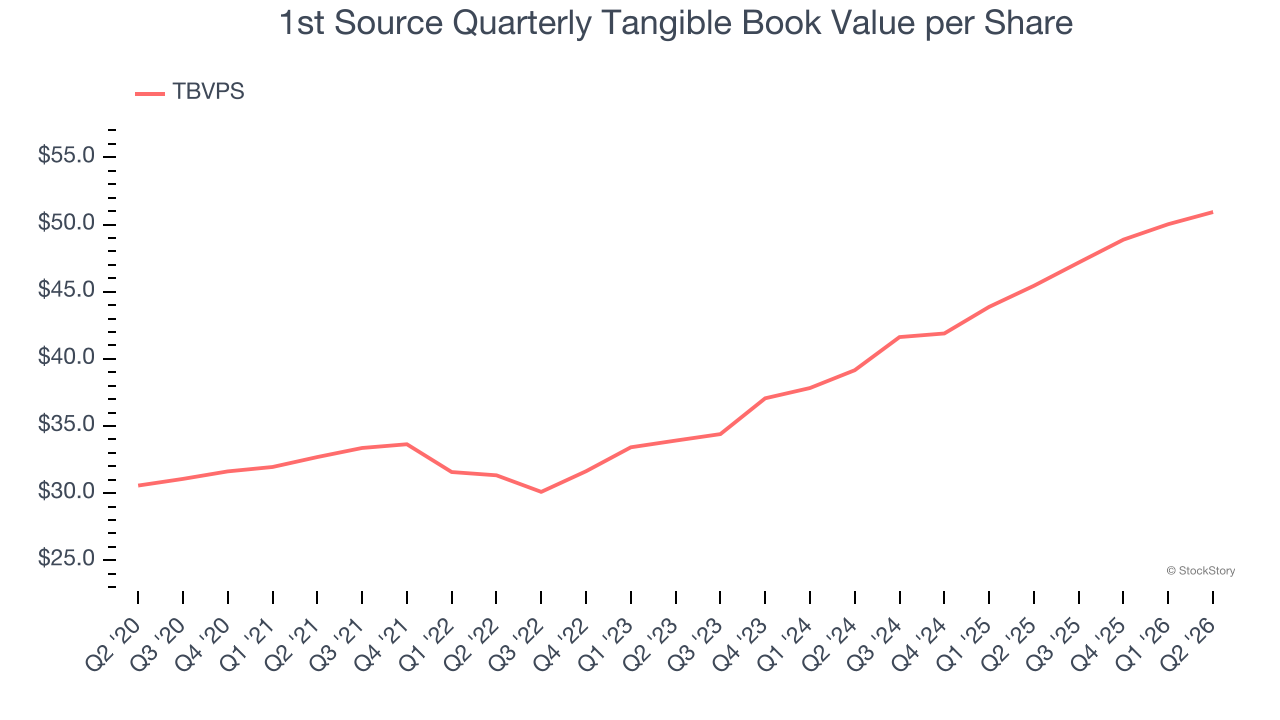
We consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation.
1st Source’s TBVPS increased by 9.3% annually over the last five years, and growth has recently accelerated as TBVPS grew at an impressive 14% annual clip over the past two years (from $39.16 to $50.93 per share).
One Reason to Be Careful:
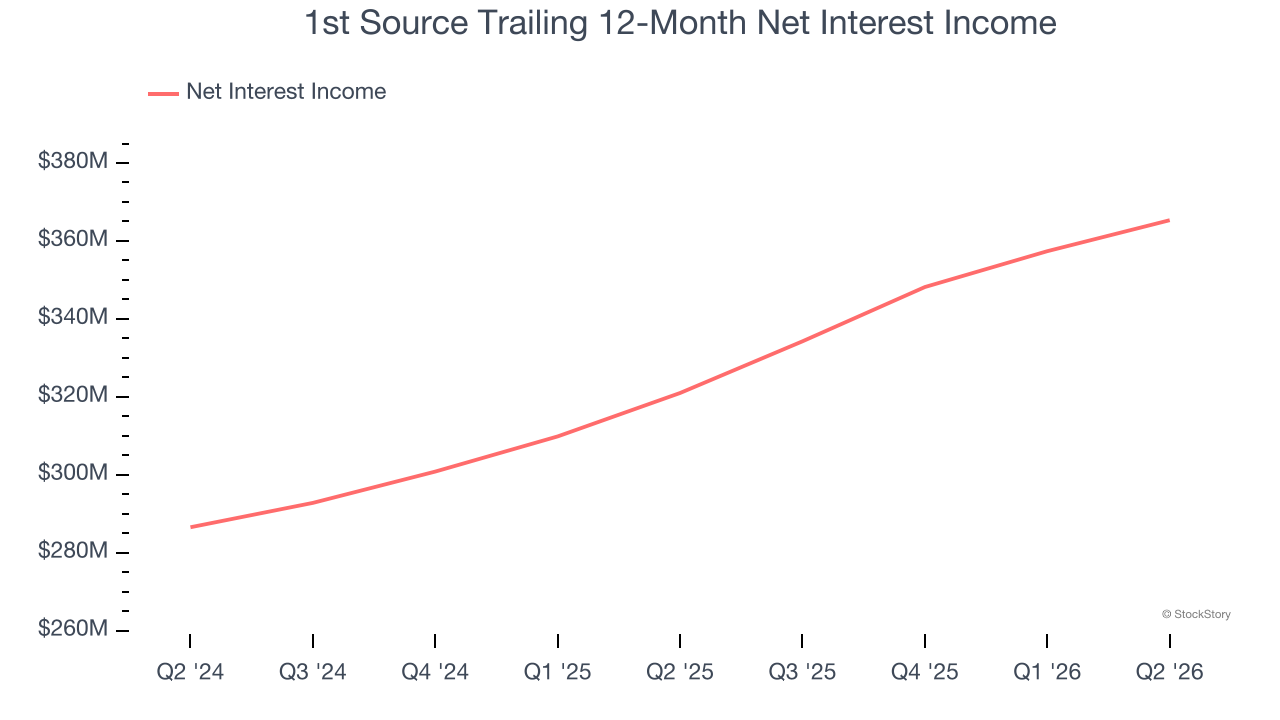
Net Interest Income Points to Soft Demand
Net interest income commands greater market attention due to its reliability and consistency, whereas one-time fees are often seen as lower-quality revenue that lacks the same dependable characteristics.
1st Source’s net interest income has grown at a 9.6% annualized rate over the last five years, slightly worse than the broader banking industry.
Final Judgment
1st Source’s merits more than compensate for its flaws, and with its shares beating the market recently, the stock trades at 1.5× forward P/B (or $85.89 per share). Is now the time to initiate a position? See for yourself in our full research report, it’s free.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.