The end of the earnings season is always a good time to take a step back and see who shined (and who didn’t). Let’s take a look at how professional tools and equipment stocks fared in Q3, starting with ESAB (NYSE: ESAB).
Automation that increases efficiency and connected equipment that collects analyzable data have been trending, creating new demand. Some professional tools and equipment companies also provide software to accompany measurement or automated machinery, adding a stream of recurring revenues to their businesses. On the other hand, professional tools and equipment companies are at the whim of economic cycles. Consumer spending and interest rates, for example, can greatly impact the industrial production that drives demand for these companies’ offerings.
The 8 professional tools and equipment stocks we track reported a mixed Q3. As a group, revenues missed analysts’ consensus estimates by 1.2% while next quarter’s revenue guidance was 4.9% below.
In light of this news, share prices of the companies have held steady as they are up 1% on average since the latest earnings results.
ESAB (NYSE: ESAB)
Having played a significant role in the construction of the iconic Sydney Opera House, ESAB (NYSE: ESAB) manufactures and sells welding and cutting equipment for numerous industries.
ESAB reported revenues of $824.5 million, up 13.3% year on year. This print was in line with analysts’ expectations, but overall, it was a softer quarter for the company with full-year EBITDA guidance missing analysts’ expectations and a significant miss of analysts’ EPS estimates.
“ESAB delivered record third quarter core sales and adjusted EBITDA, with organic growth in both segments, despite a dynamic global environment and continued inflationary pressure. We improved sales, margins and cash generation sequentially. Disciplined execution, investment in growth and our EBXai operating system are delivering results,” said Shyam P. Kambeyanda, ESAB President and CEO. “We built this enterprise to win in any market, and we are executing with urgency to capture the opportunities ahead.”
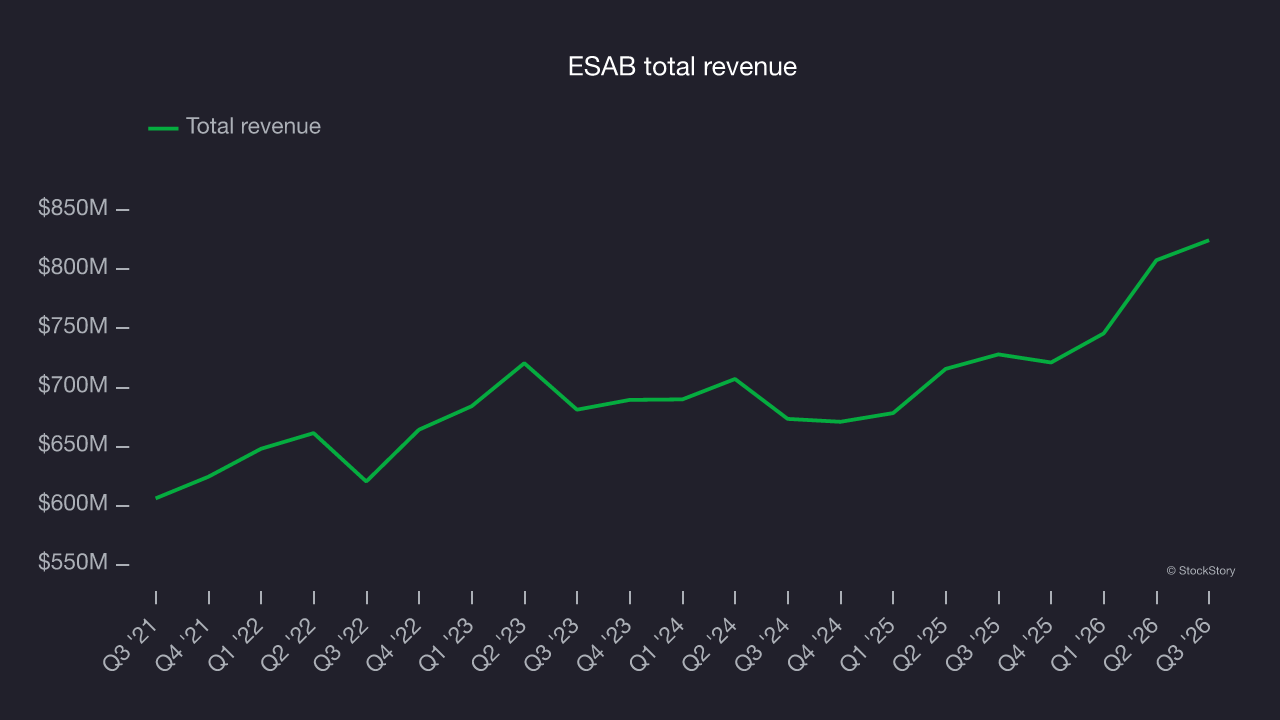
Interestingly, the stock is up 8.9% since reporting and currently trades at $82.82.
Read our full report on ESAB here, it’s free.
Best Q3: Fortive (NYSE: FTV)
Taking its name from the Latin root of "strong", Fortive (NYSE: FTV) manufactures products and develops industrial software for numerous industries.
Fortive reported revenues of $1.11 billion, up 7.8% year on year, outperforming analysts’ expectations by 3.3%. The business had an impressive quarter with a solid beat of analysts’ EBITDA estimates and full-year EPS guidance exceeding analysts’ expectations.
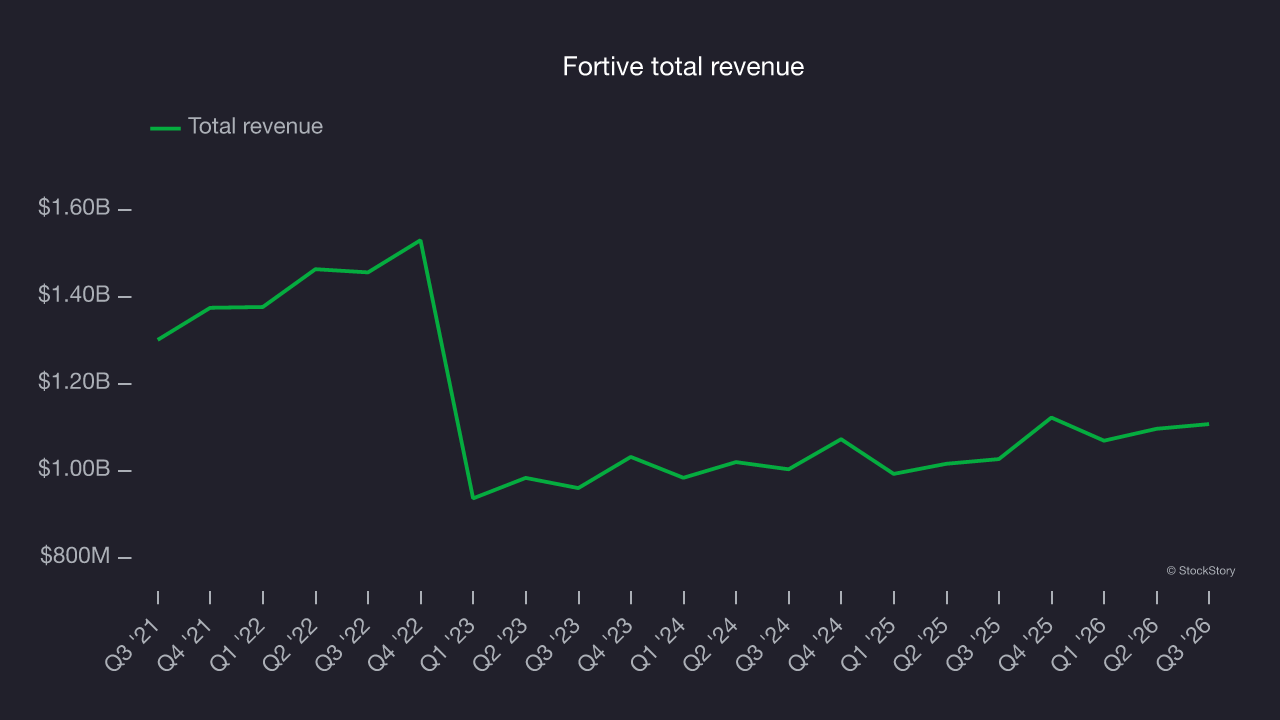
The market seems happy with the results as the stock is up 6.1% since reporting. It currently trades at $65.39.
Is now the time to buy Fortive? Access our full analysis of the earnings results here, it’s free.
Weakest Q3: Snap-on (NYSE: SNA)
Founded in 1920, Snap-on (NYSE: SNA) is a global provider of tools, equipment, and diagnostics for various industries such as vehicle repair, aerospace, and the military.
Snap-on reported revenues of $1.28 billion, flat year on year, falling short of analysts’ expectations by 3.8%. It was an underwhelming quarter as it posted a significant miss of analysts’ EPS estimates.
The stock is flat since the results and currently trades at $367.24.
Read our full analysis of Snap-on’s results here.
Lincoln Electric (NASDAQ: LECO)
Headquartered in Ohio, Lincoln Electric (NASDAQ: LECO) manufactures and sells welding equipment for various industries.
Lincoln Electric reported revenues of $1.22 billion, up 15.1% year on year. This result surpassed analysts’ expectations by 3.9%. Aside from that, it was a mixed quarter as it also recorded a solid beat of analysts’ adjusted operating income estimates but a significant miss of analysts’ organic revenue estimates.
Lincoln Electric pulled off the biggest analyst estimate beat in the group. The stock is up 5.1% since reporting and currently trades at $271.86.
Read our full, actionable report on Lincoln Electric here, it’s free.
Stanley Black & Decker (NYSE: SWK)
With an iconic “STANLEY” logo which has remained virtually unchanged for over a century, Stanley Black & Decker (NYSE: SWK) is a manufacturer primarily catering to the tool and outdoor equipment industry.
Stanley Black & Decker reported revenues of $3.73 billion, flat year on year. This print was in line with analysts’ expectations. Overall, it was a very strong quarter as it also produced a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
The stock is up 9.8% since reporting and currently trades at $114.87.
Read our full, actionable report on Stanley Black & Decker here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.