Local business platform Yelp (NYSE: YELP) announced better-than-expected revenue in Q3 2026, but revenue fell by 1.4% year on year to $370.9 million. Its GAAP profit of $0.63 per share was 48.1% above analysts’ consensus estimates.
For more on Yelp, read our full research report for free.
Yelp (YELP) Q3 2026 highlights:
- Revenue $370.9 million vs S&P analysts’ consensus estimates of $368.7 million (1.4% year-on-year decline, 0.6% beat)
- EPS (GAAP) $0.63 vs analysts’ consensus estimates of $0.43 (48.1% beat)
- Adjusted EBITDA $92.27 million vs analysts’ consensus estimates of $73.87 million (24.9% margin, 24.9% beat)
- Operating margin 13.2%, in line with the same quarter last year
- Free cash flow margin 22.8%, up from 16.3% in the previous quarter
- Market capitalization $1.20 billion
“Yelp continued to advance its AI transformation in the third quarter, and recently introduced more than 30 new features and updates, including a smarter and more personalized Yelp Assistant,” said Jeremy Stoppelman, Yelp's co-founder and chief executive officer. “Our AI tools for businesses are gaining traction, supported by substantial advances in voice AI that enable more natural conversations in both Yelp Host and Hatch. Continued demand for our trusted local content across the AI ecosystem drove growth in revenue from data licensing. While we expect consumers and local businesses to continue facing a challenging economic environment, I'm confident our strategic initiatives will position Yelp to deliver long-term shareholder value.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years. Yelp’s revenue grew at a sluggish 4% compounded annual growth rate over the last three years, falling short of the consumer internet sector standard.
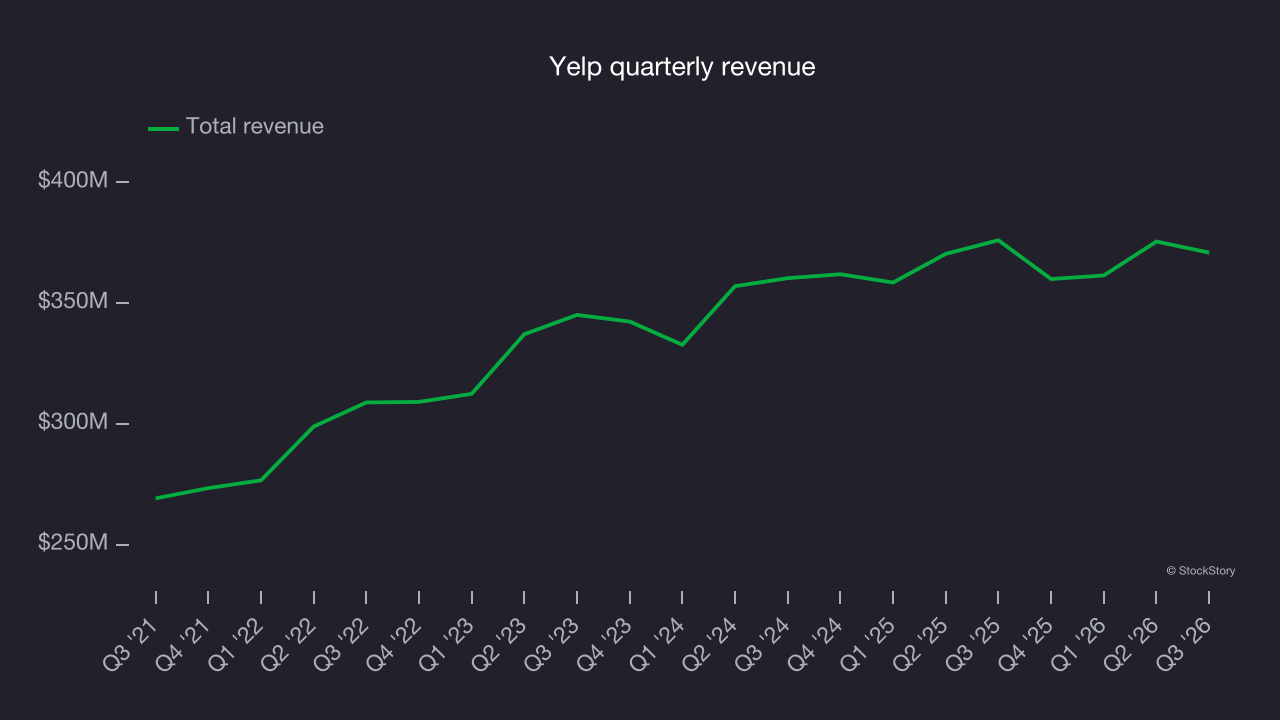
This quarter, Yelp’s revenue fell by 1.4% year on year to $370.9 million but beat Wall Street’s consensus estimates by 0.6%.
Looking ahead, sell-side analysts expect revenue to grow 1.6% over the next 12 months, according to S&P, a slight deceleration versus the last three years. This projection is underwhelming and indicates its products and services will face some demand challenges.
Free cash flow
Free cash flow matters because accounting profits alone can’t pay the bills.
Yelp has shown strong cash profitability, driven by its attractive business model that enables it to reinvest or return capital to investors while maintaining a cash cushion. The company’s free cash flow margin averaged 19.6% over the last two years, a high level for a consumer internet business.
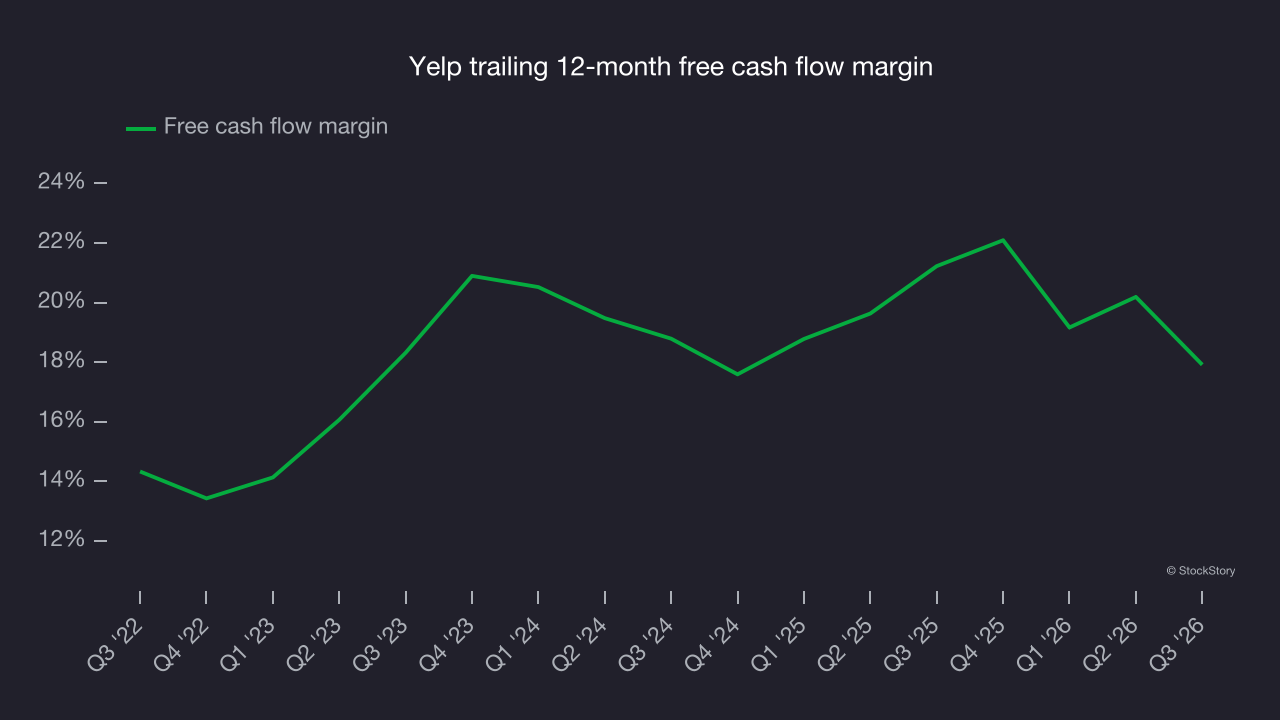
Yelp’s free cash flow totaled $84.54 million in Q3, equivalent to a 22.8% margin. The company’s cash profitability declined as its margin fell 8.8 percentage points from the same quarter last year, but it’s still above its two-year average. The quarterly decline should not carry too much weight because investment needs can be seasonal, causing short-term swings. Long-term trends are more important.
Key takeaways from Yelp’s Q3 results
Yelp’s EBITDA beat analysts’ consensus estimates by a wide margin, making this a solid quarter. Investors were likely hoping for more: Shares tumbled 6.2% to $19.25 immediately after the release.
For more on Yelp as an investment, consider its valuation, business qualities and latest quarterly results. Read the full research report here (it’s free).