Environmental waste treatment and services provider Perma-Fix (NASDAQ: PESI) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 2.8% year on year to $17.95 million. Its GAAP loss of $0.16 per share was 23.8% above analysts’ consensus estimates.
For more on Perma-Fix, read the full research report for free.
Perma-Fix (PESI) Q3 2026 highlights:
- Revenue $17.95 million vs S&P analysts’ consensus estimates of $14.9 million (2.8% year-on-year growth, 20.5% beat)
- EPS (GAAP) -$0.16 vs analysts’ consensus estimates of -$0.21 (23.8% beat)
- Adjusted EBITDA -$3.06 million (-17% margin, 109% year-on-year decline)
- Adjusted EBITDA margin -17%, down from -8.4% in the same quarter last year
- Market capitalization $271.8 million
“Our Services Segment continued to grow, with revenue up 46% year over year, gross margin improving to 12.2% and the segment generating operating income. Our PFAS (Per- and polyfluoroalkyl) destruction business saw increased sales and receipts compared with the first half of the year. Our Gen 2.0 PFAS destruction unit is expected to begin commissioning in the fourth quarter of 2026, with operations anticipated to commence during the first half of 2027. The State of Florida enacted legislation this year phasing out PFAS-containing firefighting foam, subject to specified exceptions, which we expect to support continued demand for PFAS destruction. With a growing backlog, new pricing taking effect and DFLAW volumes increasing, we believe Perma-Fix is positioned for improved results in the coming year.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term. Over the last five years, Perma-Fix’s demand was weak and its revenue declined by 7.1% per year. That underwhelming result points to poor business quality.
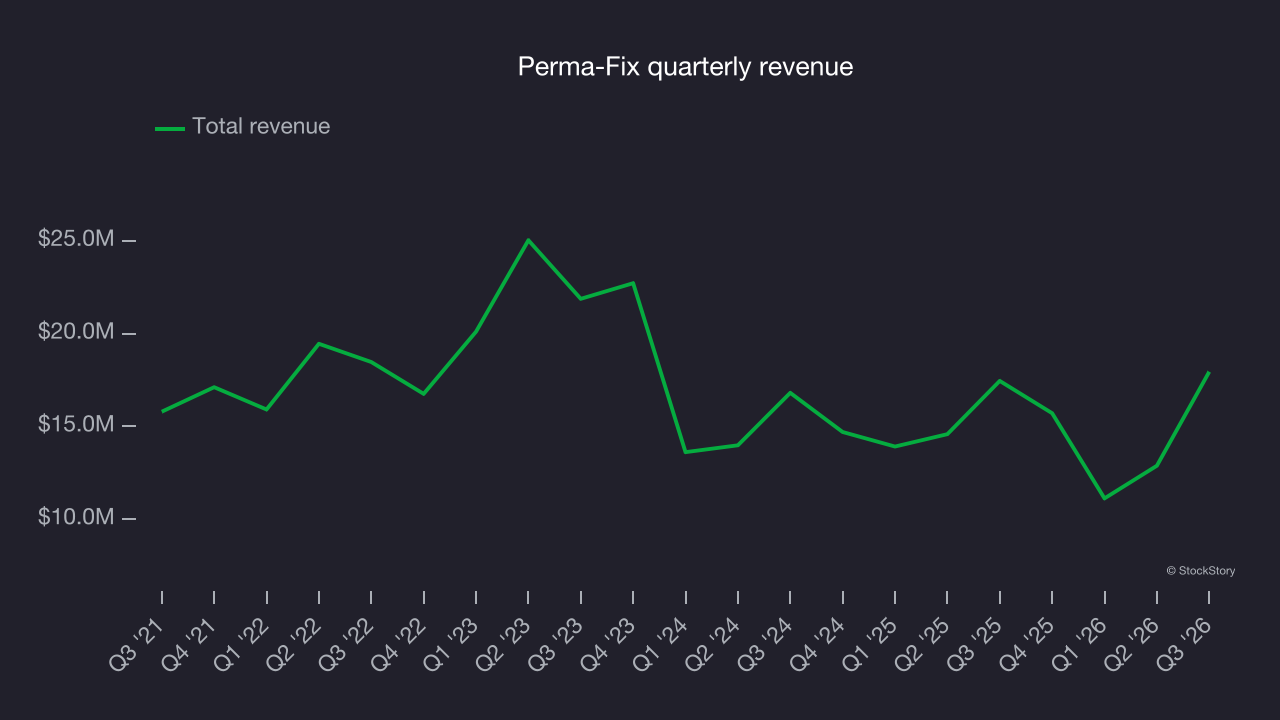
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Perma-Fix’s annualized revenue declines of 7.3% over the last two years align with its five-year trend, suggesting its demand has consistently shrunk. 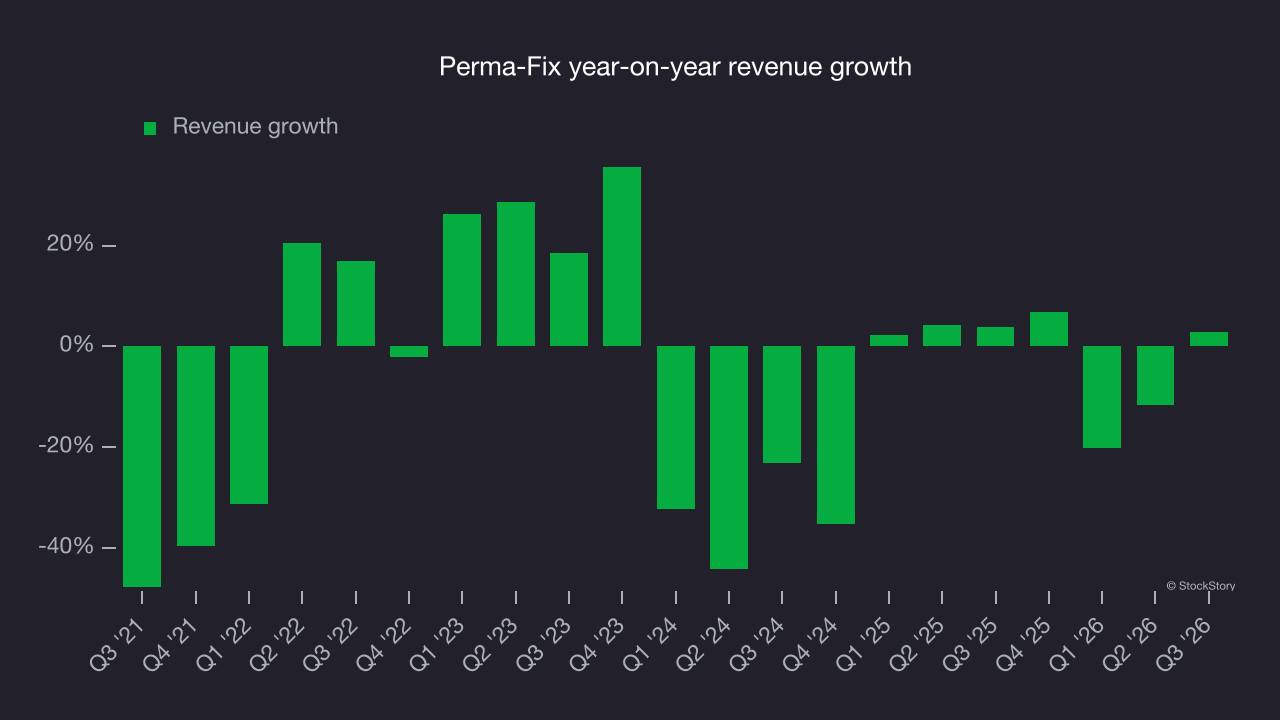
This quarter, Perma-Fix reported modest year-on-year revenue growth of 2.8% but beat Wall Street’s consensus estimates by 20.5%.
Looking ahead, sell-side analysts expect revenue to grow 51.4% over the next 12 months, according to S&P, an improvement versus the last two years. This strong growth projection suggests its newer products and services will drive better revenue performance.
Operating margin
Perma-Fix’s high expenses have contributed to an average operating margin of negative 15.2% over the last five years. Unprofitable industrial companies warrant extra scrutiny because they can be vulnerable in a downturn. That raises doubts about the business’s ability to endure a full cycle.
Looking at the trend in its profitability, Perma-Fix’s operating margin decreased by 27.9 percentage points over the last five years. Perma-Fix’s performance was poor, showing that costs were rising and it couldn’t pass them on to its customers.
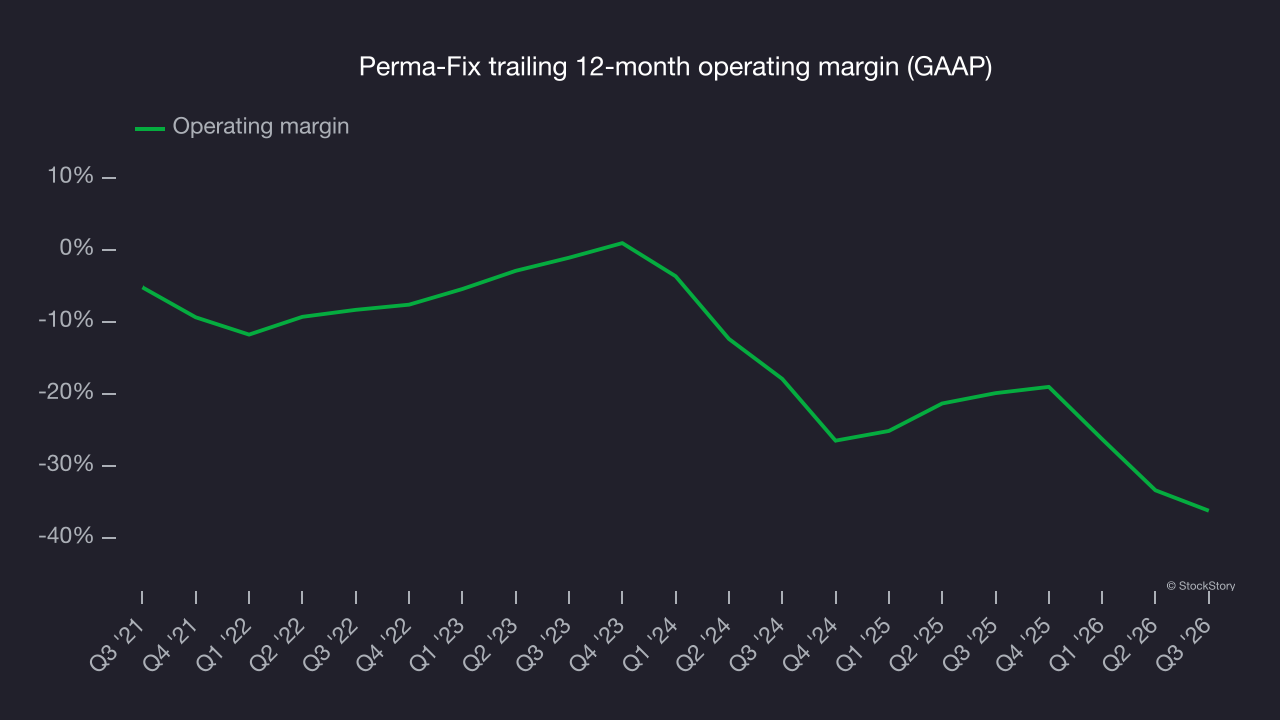
This quarter, Perma-Fix generated a negative 20.4% operating margin. The company’s persistent lack of profits raises concerns.
Free cash flow
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate.
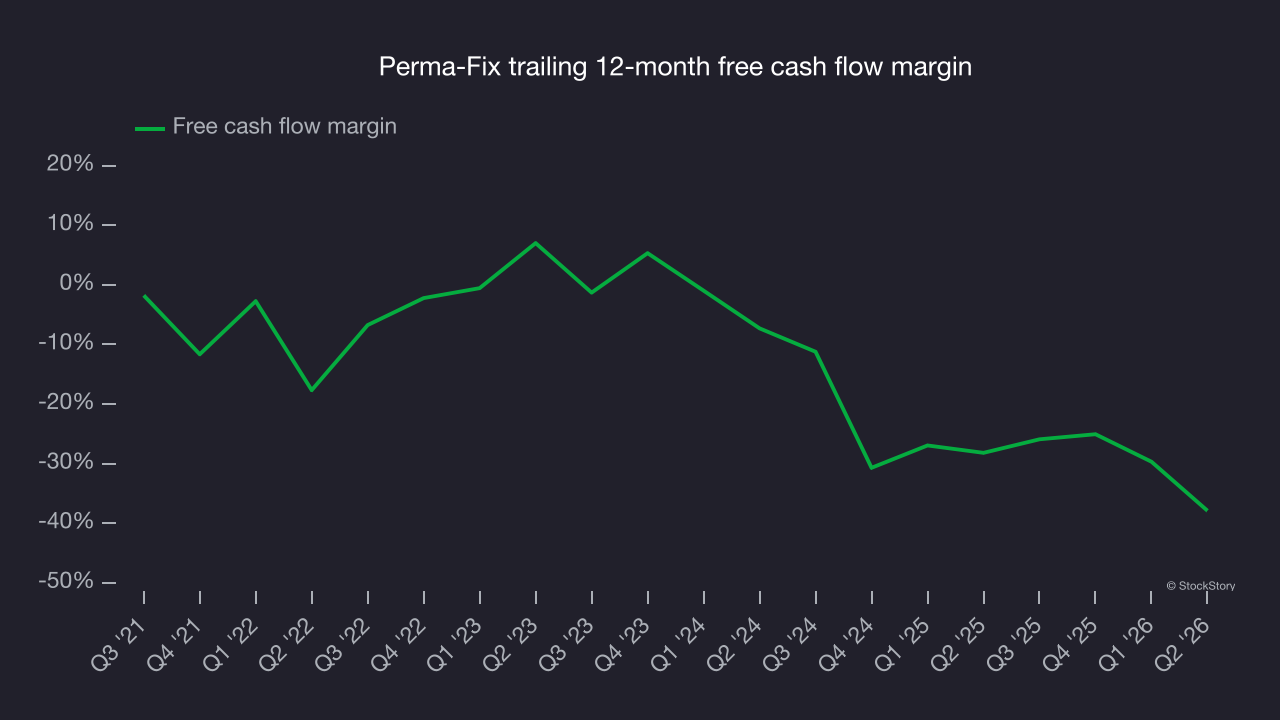
Perma-Fix’s demanding reinvestments have drained its resources over the last five years, straining its finances and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 14%, meaning it burned $13.97 in cash for every $100 in revenue.
Perma-Fix’s free cash flow margin dropped by 27 percentage points during that time. Almost any movement in the wrong direction is undesirable because it is already burning cash. If the trend continues, it could signal it’s in the middle of a large investment cycle.
Key takeaways from Perma-Fix’s Q3 results
Perma-Fix delivered sizable beats on both EBITDA and revenue this quarter, exceeding analysts’ consensus estimates for EBITDA and Wall Street’s revenue estimates by wide margins. Those results gave the quarter some important positives. Shares edged higher 1.3% to $12.98 immediately after the report.
Perma-Fix had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. That decision also requires considering its valuation and business quality alongside the latest quarterly results. For more on Perma-Fix, read the full research report here (it’s free).