Online auto marketplace CarGurus (NASDAQ: CARG) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 11.5% year on year to $258.4 million. On the other hand, next quarter’s revenue guidance of $261 million was less impressive, coming in 0.9% below analysts’ consensus estimates. Its non-GAAP profit of $0.70 per share was 5.4% above analysts’ consensus estimates.
For more on CarGurus, read our free full research report.
CarGurus (CARG) Q3 2026 highlights:
- Revenue $258.4 million vs S&P analysts’ consensus estimates of $256.5 million (11.5% year-on-year growth, 0.7% beat)
- Adjusted EPS $0.70 vs S&P analysts’ consensus estimates of $0.66 (5.4% beat)
- Adjusted EBITDA $89.66 million vs analysts’ consensus estimates of $86.69 million (34.7% margin, 3.4% beat)
- Revenue guidance $261 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $263.4 million
- Adjusted EPS guidance $0.76 at the midpoint for Q4 2026, above analysts’ consensus estimates of $0.73
- EBITDA guidance $97 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $94.95 million
- Free cash flow margin 28.6%, down from 34.9% in the previous quarter
- Paying dealers 34,701, up 1,028 year on year
- Market capitalization $3.25 billion
“We delivered strong third-quarter results, with revenue up 12% year-over-year at the high end of guidance and Adjusted EBITDA near the high end,” said Jason Trevisan, Chief Executive Officer of CarGurus. “We are bringing products to market faster and building from our marketplace foundation into a broader set of AI enabled solutions across the dealer workflow including building out our inventory pillar with the launch of StockVantage. For consumers, we are meeting shoppers in the AI tools they already use as we work toward becoming the expert guide for car shopping in an AI-led world. We believe disciplined execution and robust free cash flow position us to create long-term value for stockholders.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. CarGurus struggled to consistently increase demand as its $994 million of revenue for the trailing 12 months was close to its revenue three years ago. This was an underwhelming result, but there are still things to like about CarGurus.
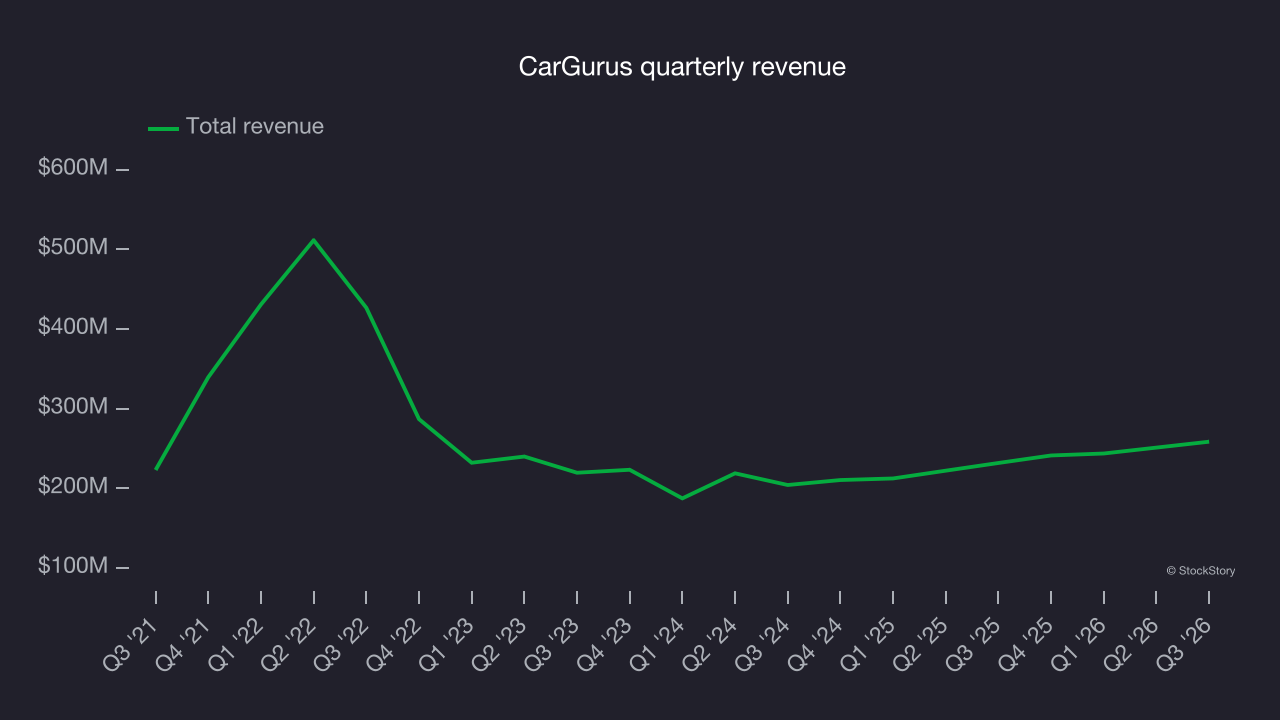
This quarter, CarGurus reported year-on-year revenue growth of 11.5%, and its $258.4 million of revenue exceeded Wall Street’s consensus estimates by 0.7%. Company management is currently guiding for an 8.3% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 8.8% over the next 12 months, according to S&P. Although this projection indicates its newer products and services will lead to better top-line performance, it is still below average for the sector. Still, the company is tracking well in other measures of financial health.
Paying dealers
User growth
As an online marketplace, CarGurus generates revenue growth by increasing both the number of users on its platform and the average order size in dollars.
Over the last two years, CarGurus’s paying dealers, a key performance metric for the company, increased by 5.2% annually to 34,701 in the latest quarter. This growth rate trails the fastest-growing consumer internet applications. If CarGurus wants to accelerate growth, it likely needs to engage users more effectively with its existing offerings or innovate with new products. 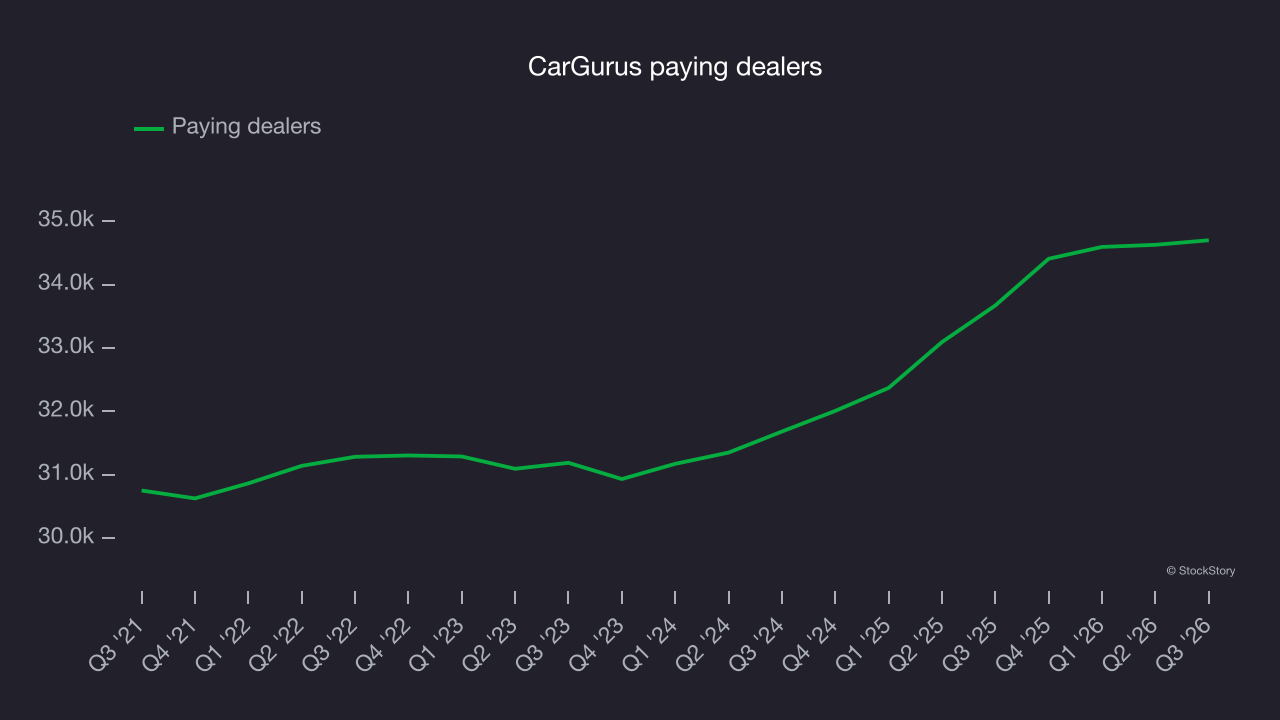
In Q3, CarGurus added 1,028 paying dealers, leading to 3.1% year-on-year growth. Quarterly growth was slower than its two-year pace, suggesting its new initiatives aren’t accelerating user growth just yet.
Revenue per user
Average revenue per user, or ARPU, is a critical metric to track because it measures how much the company earns in transaction fees from each user. ARPU also offers insight into a user’s average order size and CarGurus’s take rate, or “cut”, on each order.
CarGurus’s ARPU growth has been impressive over the last two years, averaging 8.2%. Its ability to increase monetization while growing its paying dealers demonstrates its platform’s value, as its users continue to spend more each year. 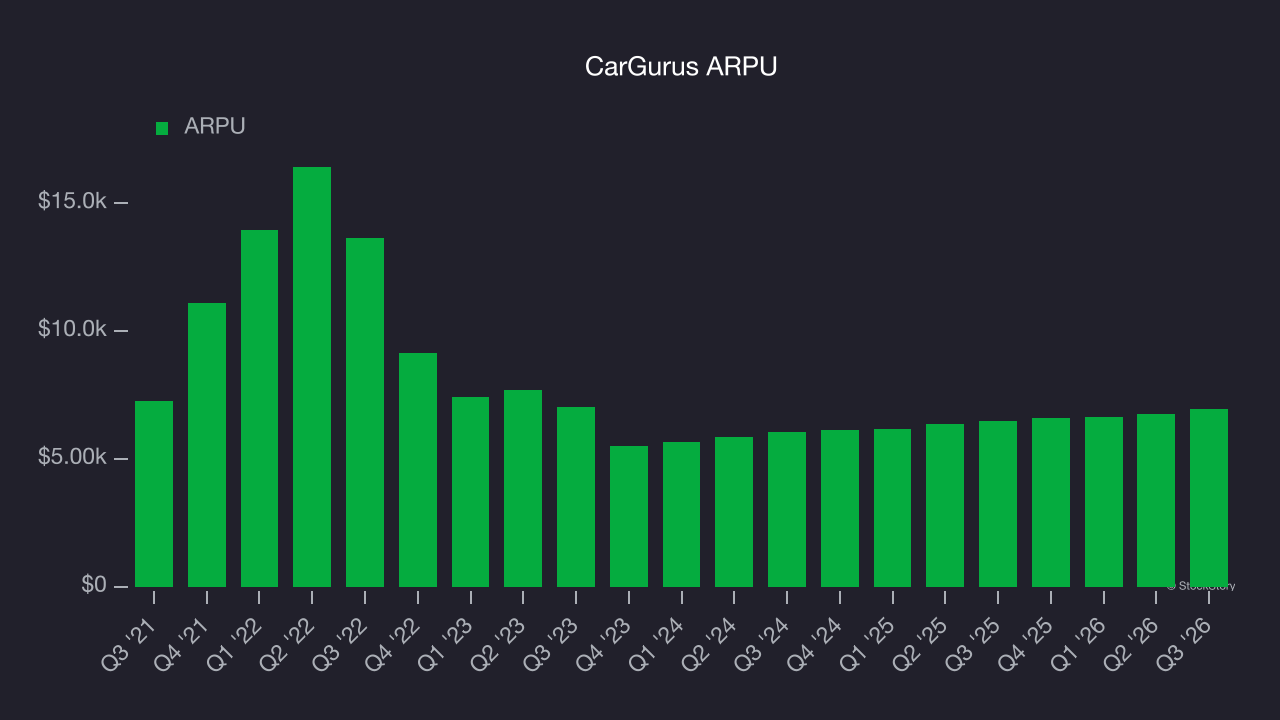
This quarter, CarGurus’s ARPU reached $6,955. It grew by 7.1% year on year, faster than its paying dealers.
Key takeaways from CarGurus’s Q3 results
CarGurus’s outlook was mixed: EBITDA guidance for next quarter topped Wall Street’s consensus estimates, but revenue guidance fell slightly short. Quarterly EBITDA also beat analysts’ consensus estimates, a positive in a quarter that still left room for improvement. Shares rose 3.8% to $37.52 immediately after the results.
Is CarGurus a buy at its current price? That decision should take into account valuation, business quality and the latest earnings. For more on CarGurus, read our full research report here (it’s free).