Financial automation platform BILL (NYSE: BILL) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027), with revenue falling 10.6% year on year to $353.8 million. Next quarter’s revenue guidance of $358 million underwhelmed, coming in 21.1% below analysts’ consensus estimates. Its non-GAAP profit of $1.18 per share was 20.7% above analysts’ consensus estimates.
For more on BILL, read our free full research report.
BILL (BILL) Q3 CY2026 highlights:
- Revenue $353.8 million vs S&P analysts’ consensus estimates of $438.8 million (19.4% miss)
- Adjusted EPS $1.18 vs S&P analysts’ consensus estimates of $0.98 (20.7% beat)
- Adjusted operating income $136.9 million vs analysts’ consensus estimates of $114.9 million (38.7% margin, 19.2% beat)
- Revenue guidance The company adjusted its revenue guidance for the full year to $1.45 billion at the midpoint
- Adjusted EPS guidance Management adjusted its full-year adjusted EPS guidance to $4.07 at the midpoint
- Operating margin 14.5%, up from -5.2% in the same quarter last year
- Free cash flow margin 23.4%, up from 22.1% in the previous quarter
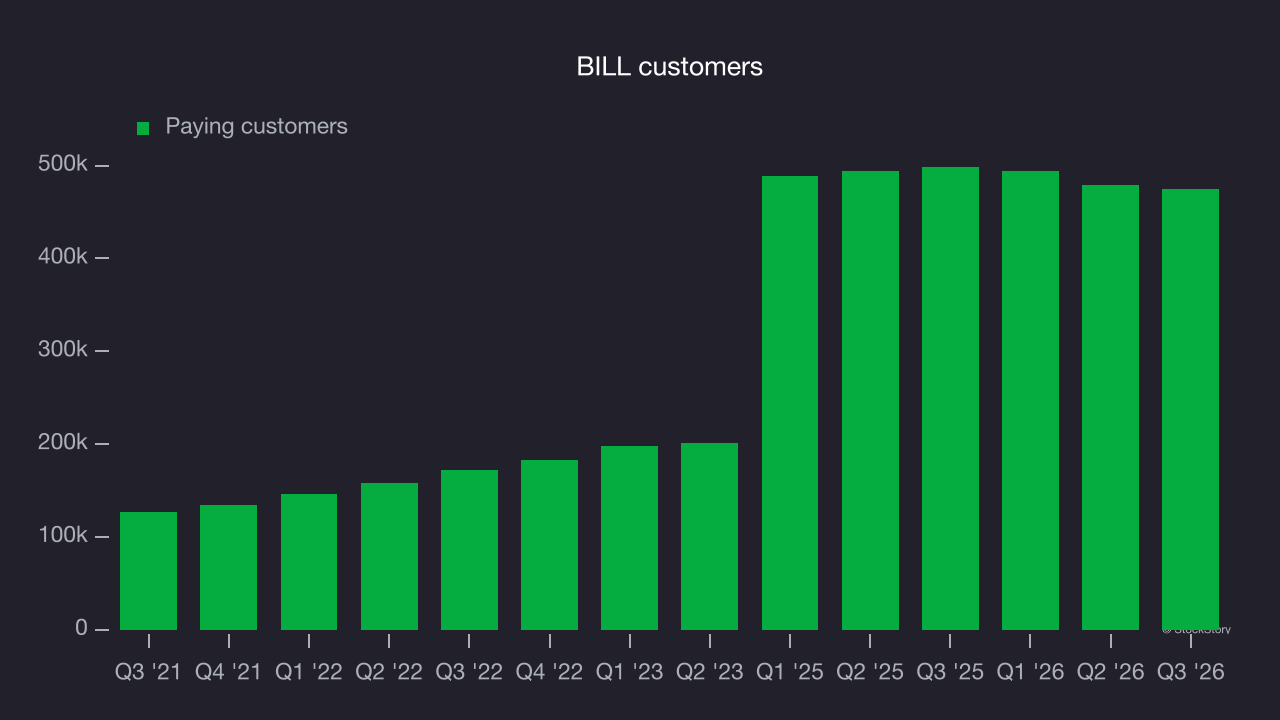
- Customers 475,300, down from 479,300 in the previous quarter
- Billings $354.7 million at quarter end
- Market capitalization $4.42 billion
“AI is changing what’s possible for us, and it shows in our product velocity: five new launches this quarter, and a Visa pilot built in four weeks,” said René Lacerte, BILL CEO and Founder. “We’re well positioned to serve the millions of businesses that still need help simplifying their finances.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Over the last five years, BILL grew its revenue at a strong 39% compounded annual growth rate. Its growth beat the average software company and shows its offerings resonate with customers.
Long-term growth matters most, but within software, a half-decade historical view may miss recent innovations or disruptive industry trends. BILL’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 9.5% over the last two years was well below its five-year trend.
This quarter, BILL missed Wall Street’s consensus estimates and reported an uninspiring 10.6% year-on-year revenue decline, generating $353.8 million of revenue. Management is guiding for a 13.7% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 16.6% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is above the sector average and indicates its newer products and services will spur better top-line performance.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
BILL’s billings came in at $354.7 million in Q3, and over the last four quarters, billings growth averaged an underwhelming 7.8% year on year. This performance mirrored its total revenue and suggests that increasing competition is making it harder to acquire and retain customers.
Customer base
BILL reported 475,300 customers at the end of the quarter, a sequential decrease of 4,000. That was better than last quarter and well above the typical growth over the previous year. This indicates that BILL has recently improved its go-to-market strategy and that those changes are working for now.
Key takeaways from BILL’s Q3 results
BILL’s strong customer growth and next-quarter EPS guidance above Wall Street’s consensus estimates were positives, but its revenue outlook fell short. Both full-year and next-quarter revenue guidance missed consensus estimates, leaving a quarter that could have been better. Shares remained flat at $50.88 immediately after the report.
The latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine whether the stock is a buy. Read our full research report here (it’s free).