Beverage company Zevia (NYSE: ZVIA) announced better-than-expected revenue in Q3 2026, with revenue up 18.4% year on year to $48.34 million. Guidance for next quarter’s revenue was better than expected at $38.5 million at the midpoint, 0.5% above analysts’ consensus estimates. Its GAAP loss of $0.03 per share was $0.02 above analysts’ consensus estimates.
For more on Zevia, read our free full research report.
Zevia (ZVIA) Q3 2026 highlights:
- Revenue $48.34 million vs S&P analysts’ consensus estimates of $44.98 million (18.4% year-on-year growth, 7.5% beat)
- EPS (GAAP) -$0.03 vs analysts’ consensus estimates of -$0.05 ($0.02 beat)
- Adjusted EBITDA -$890,000 (-1.8% margin, 48.3% year-on-year growth)
- Revenue guidance $38.5 million at the midpoint for Q4 2026, roughly in line with what analysts were expecting
- EBITDA guidance -$700,000 at the midpoint for Q4 2026, above analysts’ consensus estimates of -$766,670
- Operating margin -4.5%, up from -7% in the same quarter last year
- Free cash flow $1.35 million, up from -$65,000 in the same quarter last year
- Sales volumes rose 14.4% year on year (12.6% in the same quarter last year)
- Market capitalization $84.4 million
“Our better-than-expected third quarter results, combined with strong execution against our key focus areas and encouraging proof points across the business, reinforce our confidence in Zevia’s trajectory,” said Alexandre Ruberti, President and CEO of Zevia. “With a stronger foundation, significant liquidity and additional capital, we are entering an exciting new chapter for our business. We believe we now have the resources, momentum and strategic plan to accelerate our growth and create shareholder value over the long term.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
With $177.3 million in revenue over the past 12 months, Zevia is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
Zevia’s revenue grew at a sluggish 2.6% compounded annual growth rate over the last three years. This shows it failed to generate meaningful demand growth.
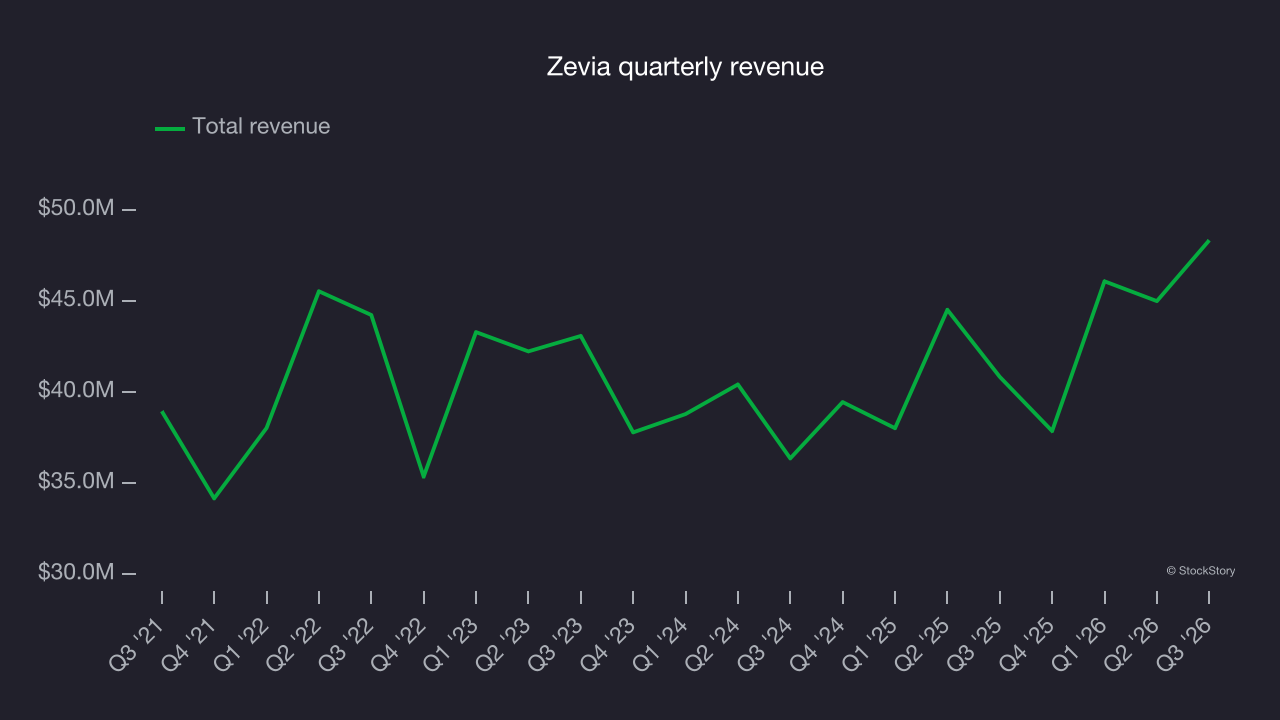
This quarter, Zevia reported year-on-year revenue growth of 18.4%, and its $48.34 million in revenue exceeded Wall Street’s consensus estimates by 7.5%. Management is guiding for a 1.7% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 2.6% over the next 12 months, according to S&P, similar to its three-year rate. This projection is underwhelming and indicates its newer products will not lead to better top-line performance yet.
Free cash flow
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate.
Zevia broke even from a free cash flow perspective over the last two years, giving the company limited opportunities to return capital to shareholders.
A positive sign is that Zevia’s margin expanded by 6.4 percentage points over the last year. The improvement shows it’s heading in the right direction, and its free cash flow profitability rose more than its operating profitability, indicating the business became less capital-intensive.
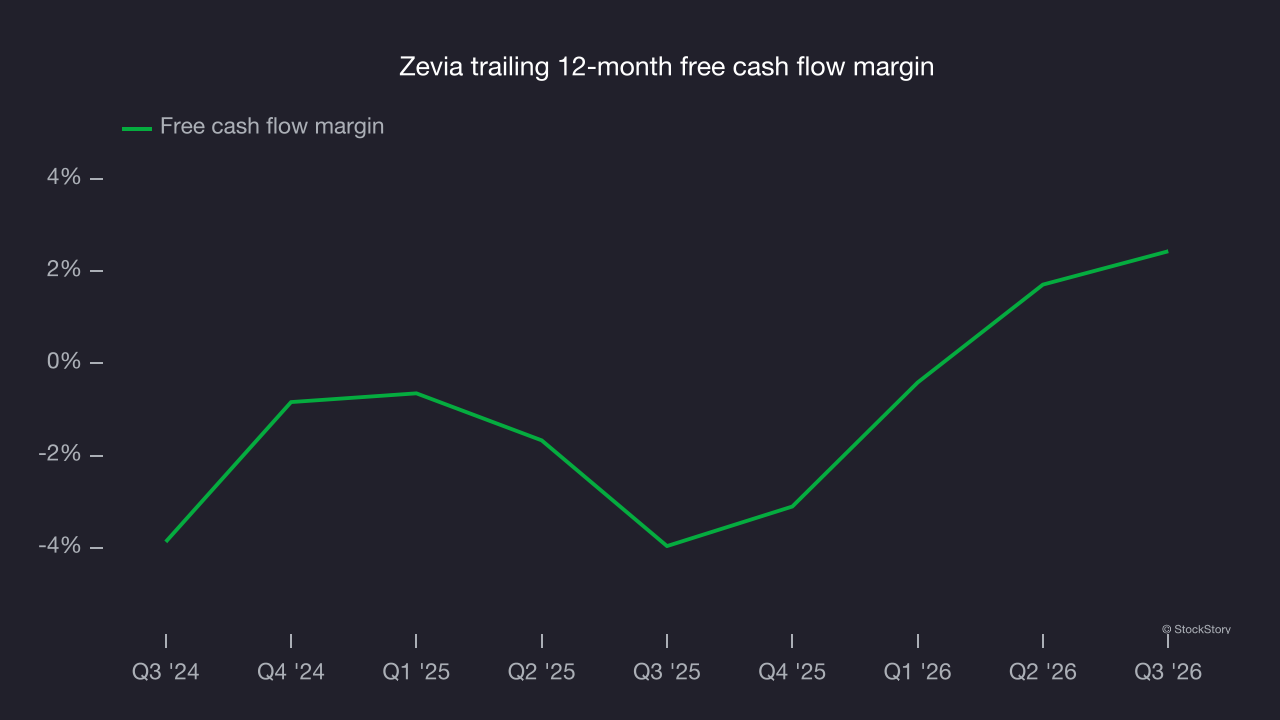
Zevia generated $1.35 million in free cash flow in Q3, equivalent to a 2.8% margin. This was a good result, as its margin was 2.9 percentage points higher than in the same quarter last year, building on its favorable historical trend.
Key takeaways from Zevia’s Q3 results
Zevia delivered a strong Q3, with EBITDA beating Wall Street’s consensus estimates by a wide margin and EPS also topping analysts’ consensus expectations. Shares soared 14.6% to $1.37 immediately after the report.
Zevia had a solid quarter, but in the bigger picture, is the stock a buy? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in the stock. For more on Zevia, read our full research report here (it’s free).