Wellness products company Nature’s Sunshine (NASDAQ: NATR) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 9.1% year on year to $116.6 million. The company’s full-year revenue guidance of $465 million at the midpoint came in 6.2% below analysts’ consensus estimates. Its non-GAAP profit of $0.14 per share was 44% below analysts’ consensus estimates.
For more on Nature's Sunshine, read our free full research report.
Nature's Sunshine (NATR) Q3 2026 highlights:
- Revenue $116.6 million vs S&P analysts’ consensus estimates of $129.5 million (9.1% year-on-year decline, 10% miss)
- Adjusted EPS $0.14 vs S&P analysts’ consensus estimates of $0.25 (44% miss)
- Adjusted EBITDA $11.14 million vs analysts’ consensus estimates of $12.16 million (9.6% margin, 8.4% miss)
- Revenue guidance The company lowered its revenue guidance for the full year to $465 million at the midpoint from $495 million, a 6.1% decrease
- EBITDA guidance $46 million at the midpoint for the full year, below analysts’ consensus estimates of $50.86 million
- Operating margin 4.5%, down from 7% in the same quarter last year
- Free cash flow margin 7.9%, down from 13.1% in the same quarter last year
- Market capitalization $212.4 million
"Our third-quarter results were disappointing and fell short of our expectations,” said Ken Romanzi, CEO of Nature’s Sunshine. “We faced several challenges in our business, particularly in China and in our Digital business. In China, operational disruptions have had a more significant impact on our consultant leadership base than we initially anticipated which we have already begun rebuilding. Further, following several quarters of exceptional growth in our Digital business, we are continuing to invest in this critical part of our portfolio to position it for the next phase of growth."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years.
With $480.3 million in revenue over the past 12 months, Nature's Sunshine is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
Nature's Sunshine’s revenue grew at a sluggish 3% compounded annual growth rate over the last three years. This shows it failed to generate substantial demand.
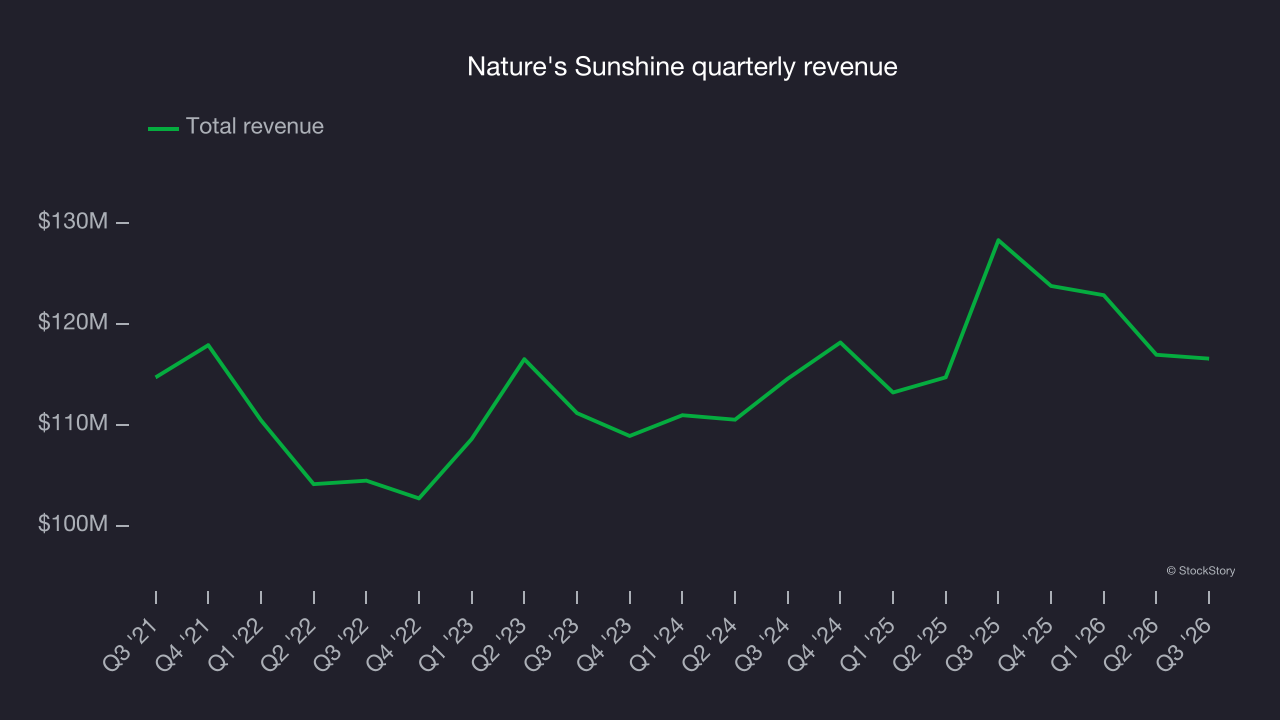
This quarter, Nature's Sunshine missed Wall Street’s consensus estimates and reported an uninspiring 9.1% year-on-year revenue decline, generating $116.6 million in revenue.
Looking ahead, sell-side analysts expect revenue to grow 6.5% over the next 12 months, according to S&P, an acceleration versus the last three years. This projection is above the sector average and implies its newer products will spur better top-line performance.
Free cash flow
Free cash flow matters because companies need cash, not accounting profits, to pay the bills.
Nature's Sunshine has shown mediocre cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 4.4%, below the expected level for a consumer staples business.
Nature's Sunshine’s margin dropped by 4.4 percentage points over the last year. That decline, along with its uninspiring margin, puts the company in a difficult position, and shareholders are likely hoping it can reverse course. If the trend continues, it could signal it’s becoming a more capital-intensive business.
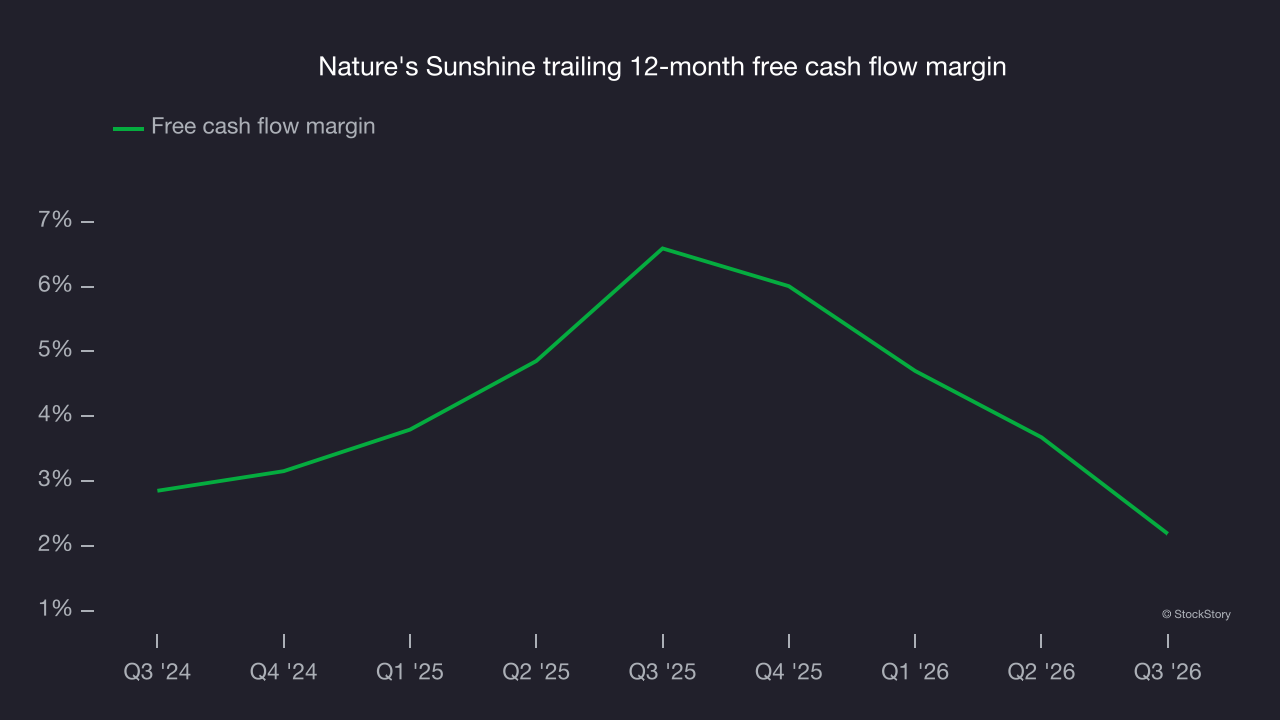
Nature's Sunshine’s free cash flow was $9.21 million in Q3, equivalent to a 7.9% margin. The company’s cash profitability deteriorated as its margin fell 5.2 percentage points from the same quarter last year, but it remained above its two-year average. This quarter’s decline should not carry too much weight because capital expenditures can be seasonal and companies often stockpile inventory in anticipation of higher demand, causing short-term swings. Long-term trends carry greater meaning.
Key takeaways from Nature's Sunshine’s Q3 results
Nature’s Sunshine delivered a softer quarter with few positives: Revenue fell short of Wall Street’s consensus estimates, and full-year revenue guidance also missed expectations. Shares plunged 13.3% to $11.13 immediately after the report.
Nature's Sunshine’s earnings report left more to be desired. A closer look can help assess whether this quarter has created a buying opportunity. The latest quarter is only one part of the company’s longer-term business quality. Quality, combined with valuation, can help determine if the stock is a buy. For more on Nature's Sunshine, read the full research report here (it’s free).