Oil and gas producer SM Energy (NYSE: SM) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 167% year on year to $2.17 billion. Its GAAP profit of $0.39 per share was 80.1% below analysts’ consensus estimates.
For more on SM Energy, read our free full research report.
SM Energy (SM) Q3 2026 highlights:
- Revenue $2.17 billion vs S&P analysts’ consensus estimates of $2.12 billion (167% year-on-year growth, 2.2% beat)
- EPS (GAAP) $0.39 vs analysts’ consensus estimates of $1.96 (80.1% miss)
- Operating margin 10.9%, down from 30.4% in the same quarter last year
- Free cash flow margin 18.9%, down from 28.9% in the same quarter last year
- Oil production per day increased 102% year on year
- Market capitalization $8.91 billion
"This is a multi-year journey, and our strong and resilient balance sheet is the foundation. We remain on track for low one-times leverage at mid-cycle prices by year-end 2026, strengthening the capacity for durable stockholder returns. With integration substantially complete, our focus is on disciplined execution, continuous improvement and increasing the capital efficiency of the portfolio to compound long-term value for stockholders."
Revenue growth
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can perform well for a year or so, but a top-tier one should exhibit resilience through cycles. SM Energy’s 26.8% annualized revenue growth over the last five years was strong. Its growth surpassed the average energy upstream and integrated energy company and shows its offerings resonate with customers.
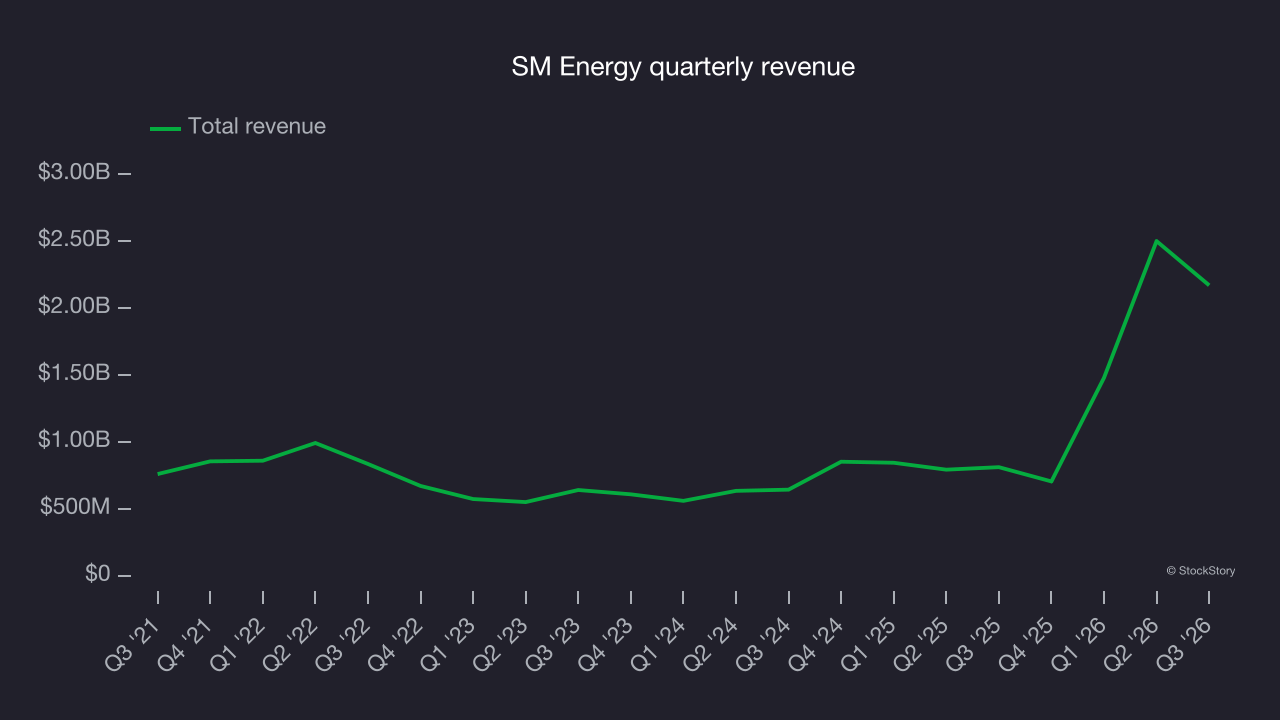
Even a long stretch in energy can be shaped by a single commodity cycle, so extending the view to ten years adds another perspective and reveals which companies are built to grow regardless of the pricing regime. SM Energy’s annualized revenue growth of 19.7% over the last ten years is below its five-year trend, but the results still suggest decent demand.
While looking at revenue is important, it can also introduce noise around commodity prices and M&A. Analyzing drivers of revenue, on the other hand, highlights what is happening inside the asset base and whether the economic footprint of a company is expanding. Over the last two years, SM Energy’s oil production per day averaged 64.6% year-on-year growth while its natural gas production per day averaged 52.1% year-on-year growth. 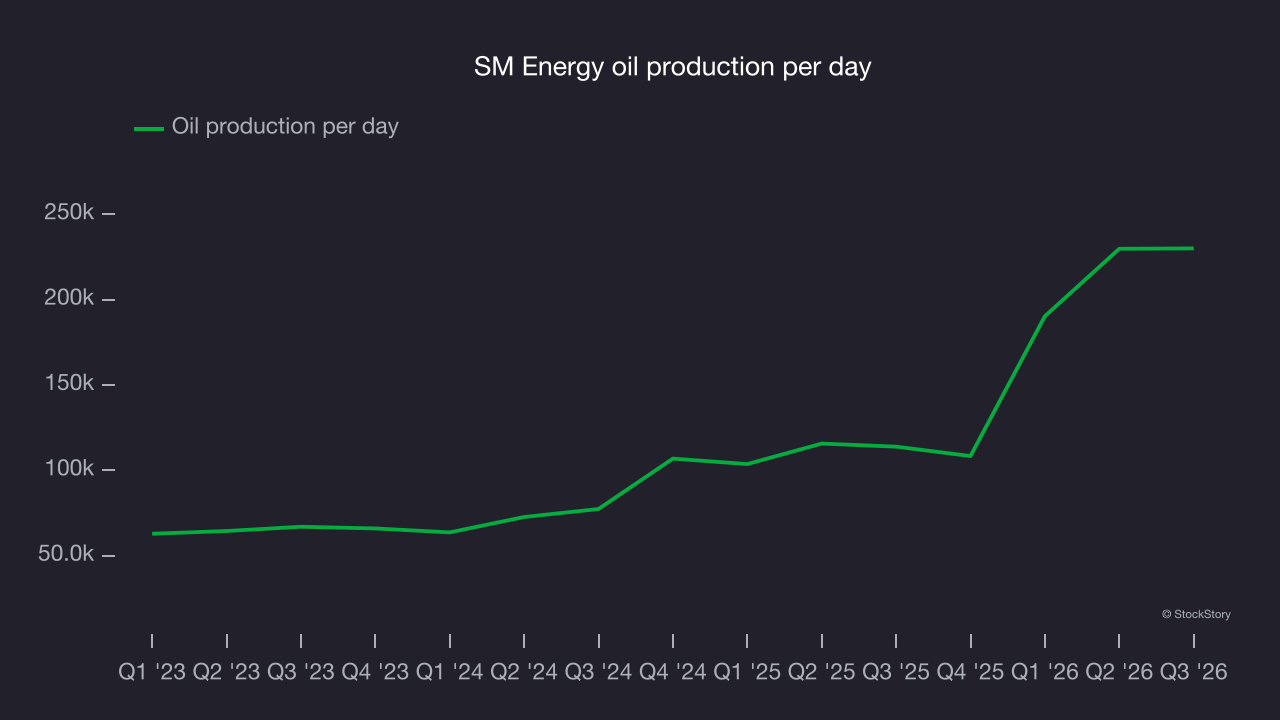
This quarter, SM Energy reported year-on-year revenue growth of 167%, and its $2.17 billion of revenue beat Wall Street’s consensus estimates by 2.2%. Its oil production per day grew 102% year on year.
Adjusted EBITDA margin
SM Energy has operated efficiently over the last five years. It demonstrated strong profitability for an upstream and integrated energy business, with an average EBITDA margin of 60.8%.
Analyzing the trend in its profitability, SM Energy’s EBITDA margin decreased by 3.7 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
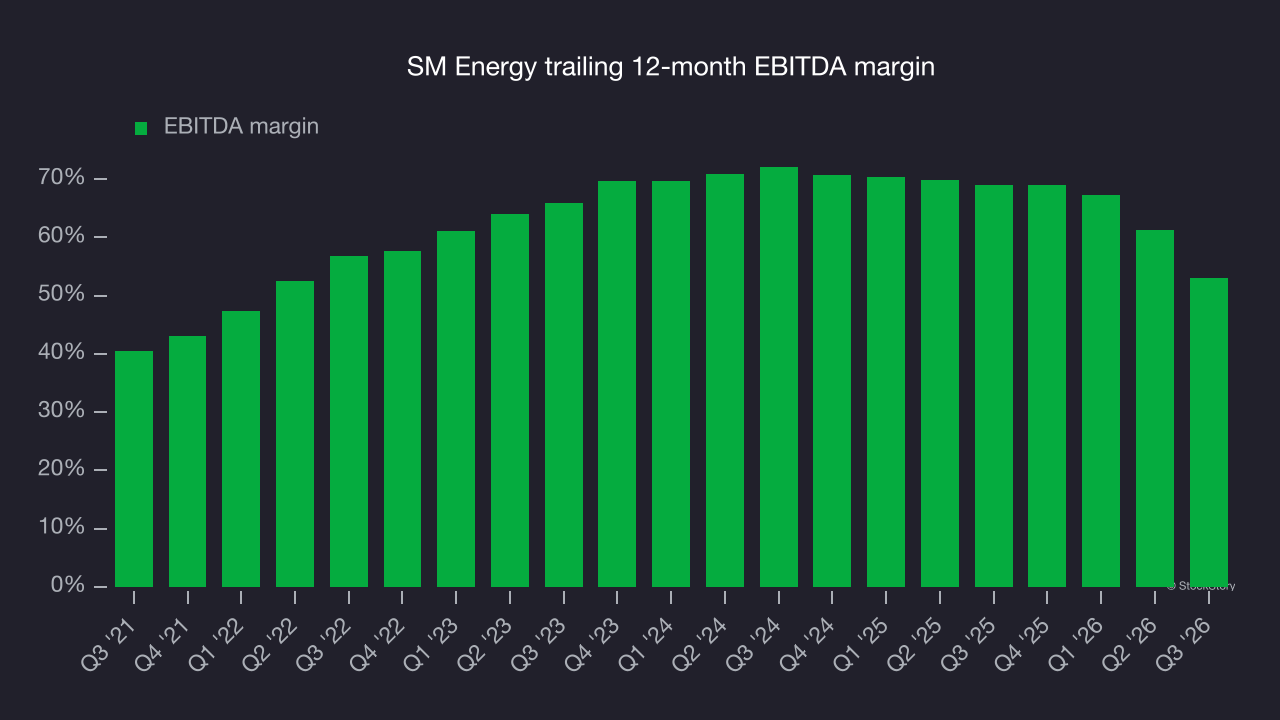
In Q3, SM Energy generated an EBITDA margin of 38.7%, down 31.6 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. Its adjusted EBITDA fell short of Wall Street’s consensus estimates.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing “rock” is before financing and reinvestment, while free cash flow, or FCF, shows how much value remains after paying to replace those wells. Because production declines over time, strong EBITDA can coexist with weak FCF if drilling is expensive or declines are steep. FCF therefore captures both operating efficiency and the cost of sustaining production.
SM Energy has shown strong cash profitability, driven by a lucrative business model that enables it to reinvest, return capital to investors and maintain a competitive advantage. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 19.4% over the last five years.
Absolute FCF margin levels matter, but so does the stability of free cash flow. All else equal, a steady 25.0% average free cash flow margin across commodity price cycles is preferable to very high margins when times are good and negative ones when they’re tough.
SM Energy’s ratio of quarterly free cash flow volatility to West Texas Intermediate, or WTI, crude oil price volatility over the past five years was 4.5 (lower is better), indicating unusually strong insulation from commodity swings. This stability supports superior capital access in downturns and positions SM Energy to act as a consolidator when weaker peers are forced to retrench.
Why compare free cash flow with commodity prices rather than revenue or EBITDA with WTI in SM Energy’s case? What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
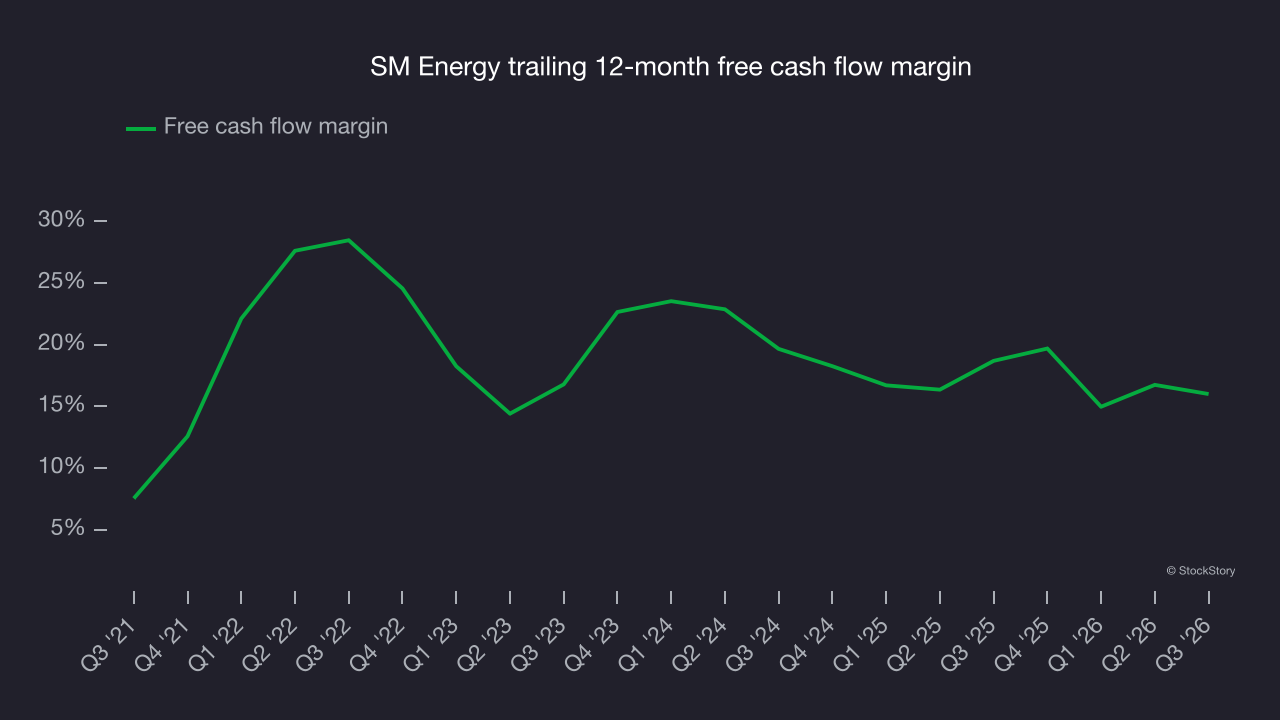
SM Energy’s free cash flow was $411 million in Q3, equivalent to an 18.9% margin. The company’s cash profitability deteriorated as its margin fell 9.9 percentage points from the same quarter last year, an unfavorable change given its longer-term trend.
Key takeaways from SM Energy’s Q3 results
SM Energy’s revenue beat analysts’ consensus estimates, but the EPS miss left the quarter looking weaker overall. Shares fell 4.7% to $34.96 immediately after the results.
SM Energy had an underwhelming quarter, but does that create an opportunity to buy the stock at the current price? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. Read the free full research report for more on SM Energy.