Home Bancshares’s 12.2% return over the past six months has outpaced the S&P 500 by 5%, and its stock price has climbed to $29.78 per share. This run-up might have investors contemplating their next move.
Is now the time to buy Home Bancshares, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why is Home Bancshares not exciting?
Despite the momentum, we’re cautious about Home Bancshares. Here are three reasons why HOMB doesn’t excite us, plus one stock we’d rather own.
1. Lackluster revenue growth
We at StockStory place the most emphasis on long-term growth, but within financials, a stretched historical view may miss recent interest rate changes, market returns, and industry trends. Home Bancshares’s recent performance shows its demand has slowed as its annualized revenue growth of 6.7% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 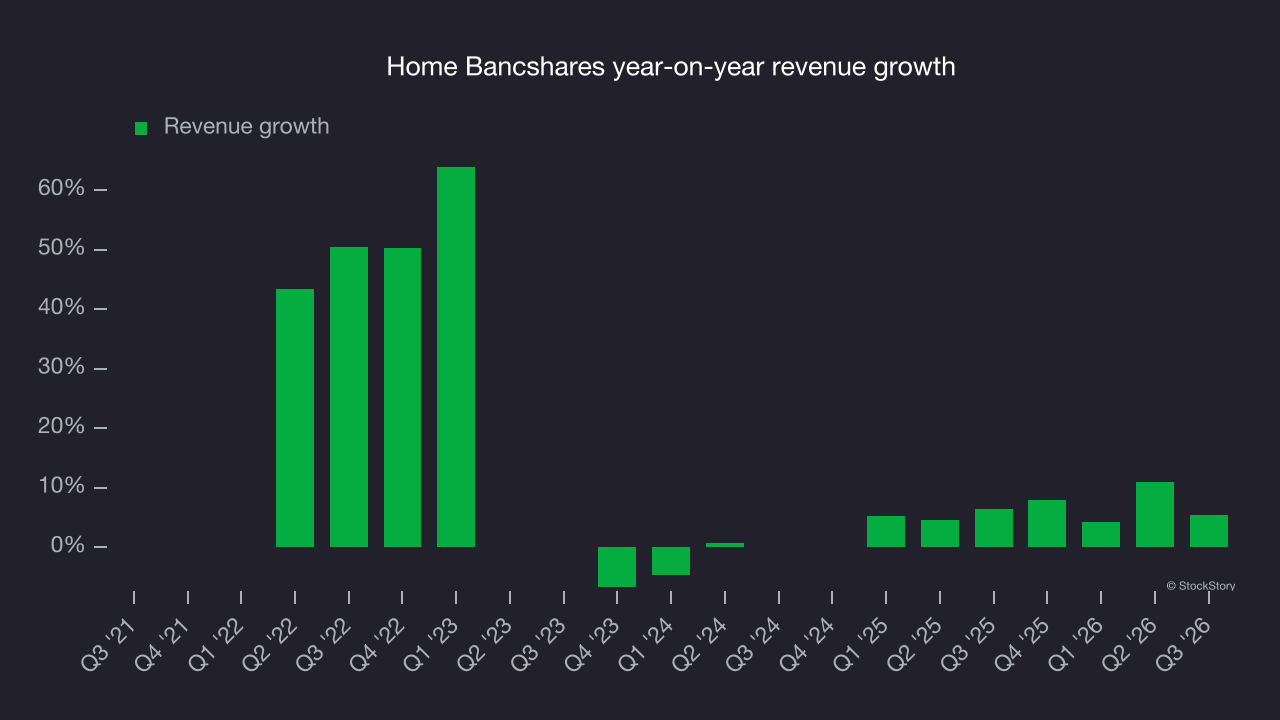 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
2. Projected net interest income growth is slim
Forecasted net interest income by Wall Street analysts signals a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Home Bancshares’s net interest income to rise by 4%, according to S&P, a slight deceleration versus its 6.1% annualized growth for the past two years. This projection is slightly below its 6.1% annualized growth rate for the past two years.
3. EPS barely growing
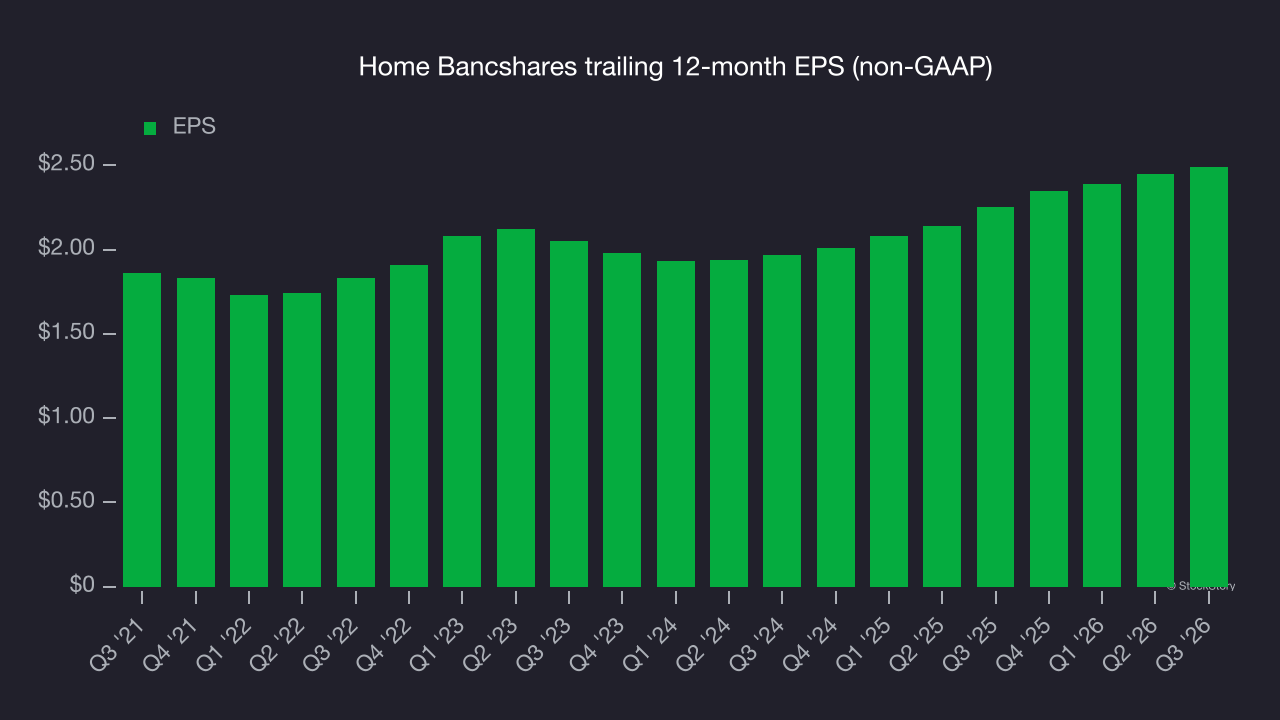
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Home Bancshares’s EPS grew at a weak 6% compounded annual growth rate over the last five years, lower than its 10.1% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
Final judgment
Home Bancshares isn’t a terrible business, but it isn’t one of our picks. With its shares outperforming the market lately, the stock trades at 1.3× forward P/B (or $29.78 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
High-quality stocks for all market conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.