Deere’s 17.2% return over the past six months has outpaced the S&P 500 by 10%, and its stock price has climbed to $677.62 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy Deere, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why do we think Deere will underperform?
Despite the momentum, we don’t have much confidence in Deere. Here are three reasons why DE doesn’t excite us, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
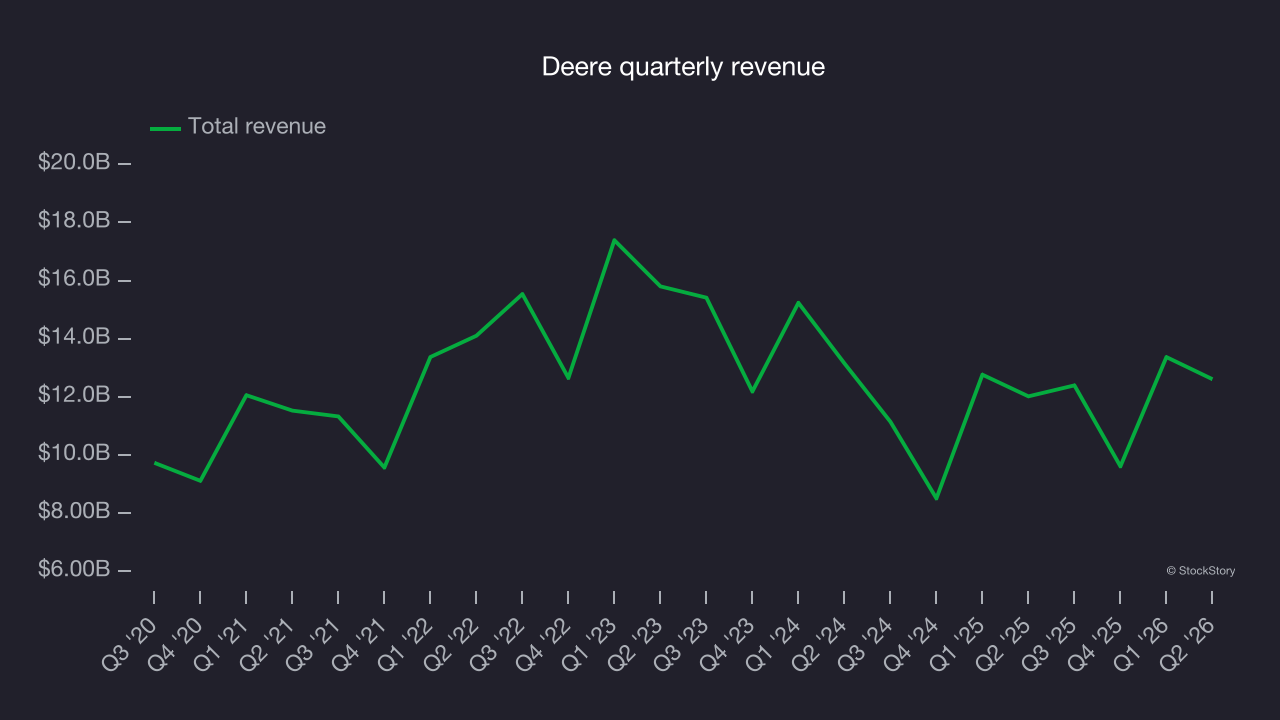
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Regrettably, Deere’s sales grew at a sluggish 2.5% compounded annual growth rate over the last five years. This was below our standards.
2. EPS growth has stalled
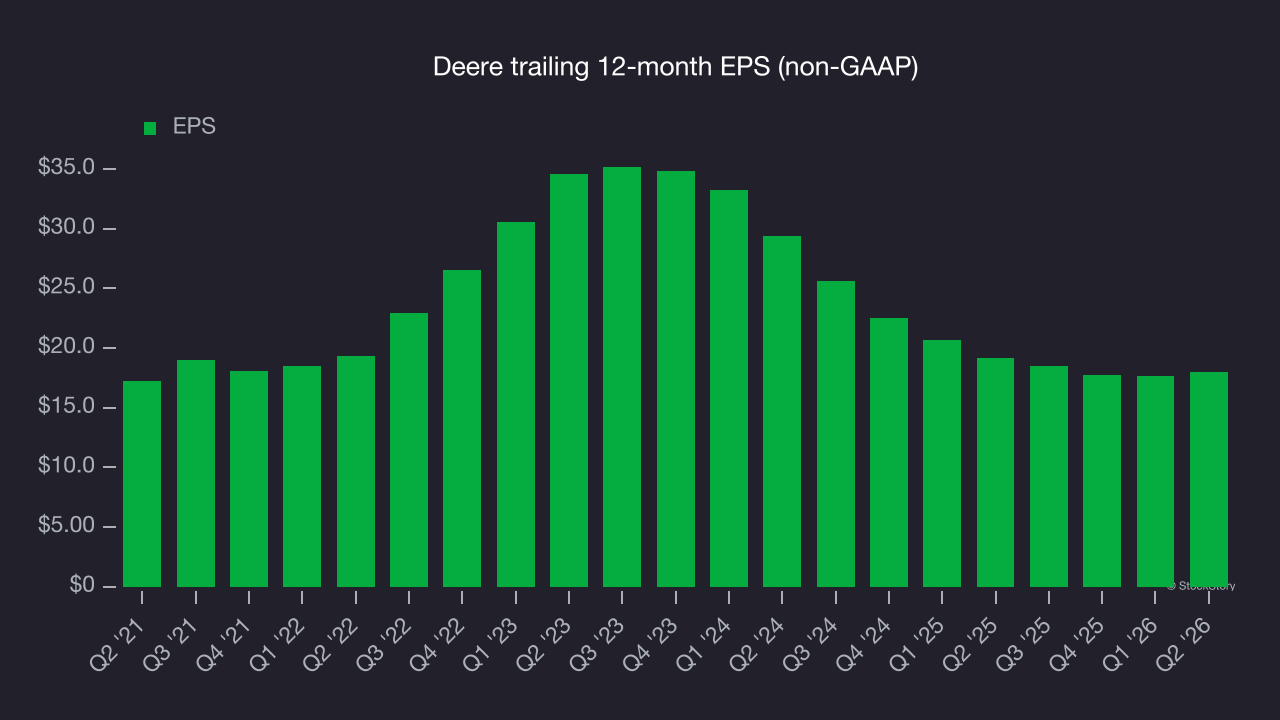
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Deere’s flat EPS over the last five years was below its 2.5% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. New investments fail to bear fruit as ROIC declines
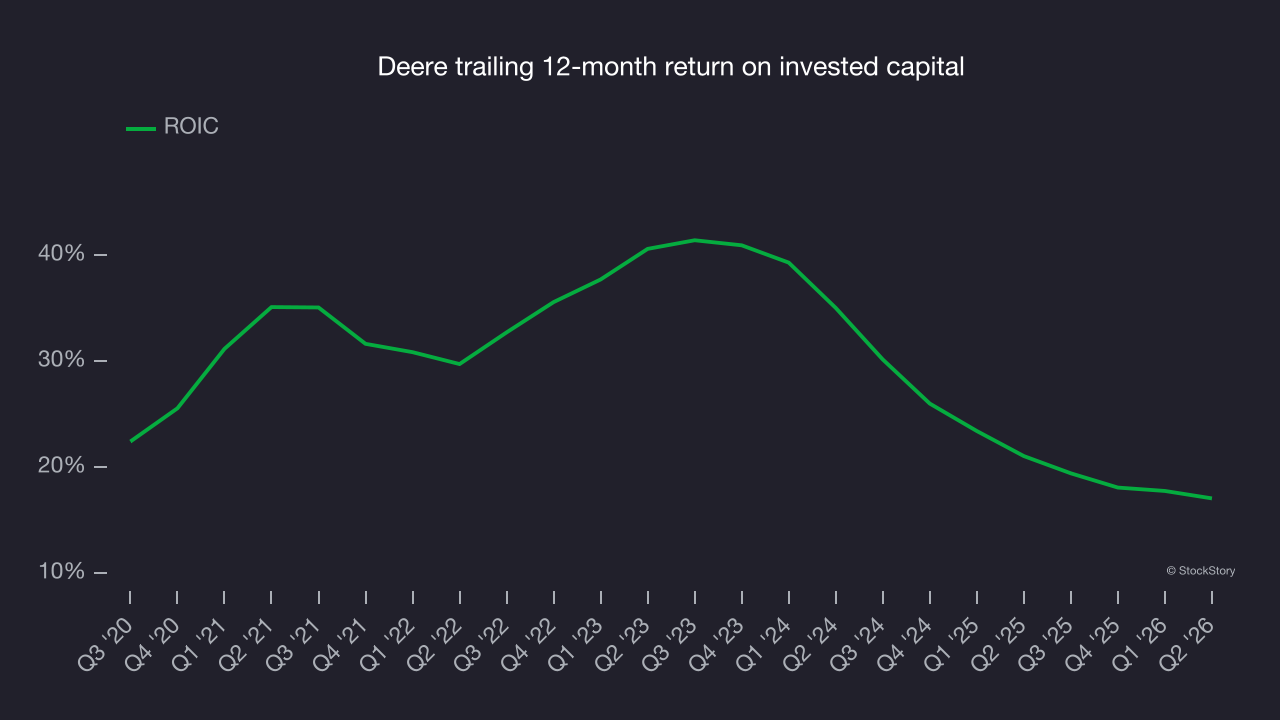
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Over the last few years, Deere’s ROIC has unfortunately decreased significantly. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final judgment
Deere falls short of our quality standards. With its shares beating the market recently, the stock trades at 31.3× forward P/E (or $677.62 per share). This valuation tells us a lot of optimism is priced in - we think there are better opportunities elsewhere. We’d recommend looking at the most entrenched endpoint security platform on the market.
High-quality stocks for all market conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.