Electronics distributor Richardson Electronics (NASDAQ: RELL) reported calendar Q3 2026 (fiscal Q1 2027) results beating Wall Street’s revenue expectations, with sales up 18.9% year on year to $64.92 million. Its GAAP profit of $0.27 per share was significantly above analysts’ consensus estimates.
Is now the time to buy Richardson Electronics? Find out by accessing our full research report, it’s free.
Richardson Electronics (RELL) Q3 CY2026 Highlights:
- Revenue: $64.92 million vs analyst estimates of $58.99 million (18.9% year-on-year growth, 10.1% beat)
- EPS (GAAP): $0.27 vs analyst estimates of $0.09 (significant beat)
- Operating Margin: 7.9%, up from 1.8% in the same quarter last year
- Free Cash Flow Margin: 6.4%, up from 0.6% in the same quarter last year
- Backlog: $184.4 million at quarter end, up 36.9% year on year
- Market Capitalization: $279.9 million
“Fiscal 2027 is off to an excellent start, as Richardson Electronics delivered its ninth consecutive quarter of year-over-year sales growth, expanded levels of profitability, and generated strong free cash flow. First-quarter performance continued to reflect strong demand in Power and Microwave Technologies (PMT), particularly for engineered solutions serving the semiconductor wafer fabrication equipment market, as well as distributed RF and microwave products. We also experienced significant growth in Green Energy Solutions (GES) and Canvys. Overall, our team delivered another strong operating performance,” said Edward J. Richardson, Chairman, Chief Executive Officer, and President.
Company Overview
Founded in 1947, Richardson Electronics (NASDAQ: RELL) is a distributor of power grid and microwave tubes as well as consumables related to those products.
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Richardson Electronics grew its sales at a sluggish 4.5% compounded annual growth rate. This fell short of our benchmark for the industrials sector and is a tough starting point for our analysis.
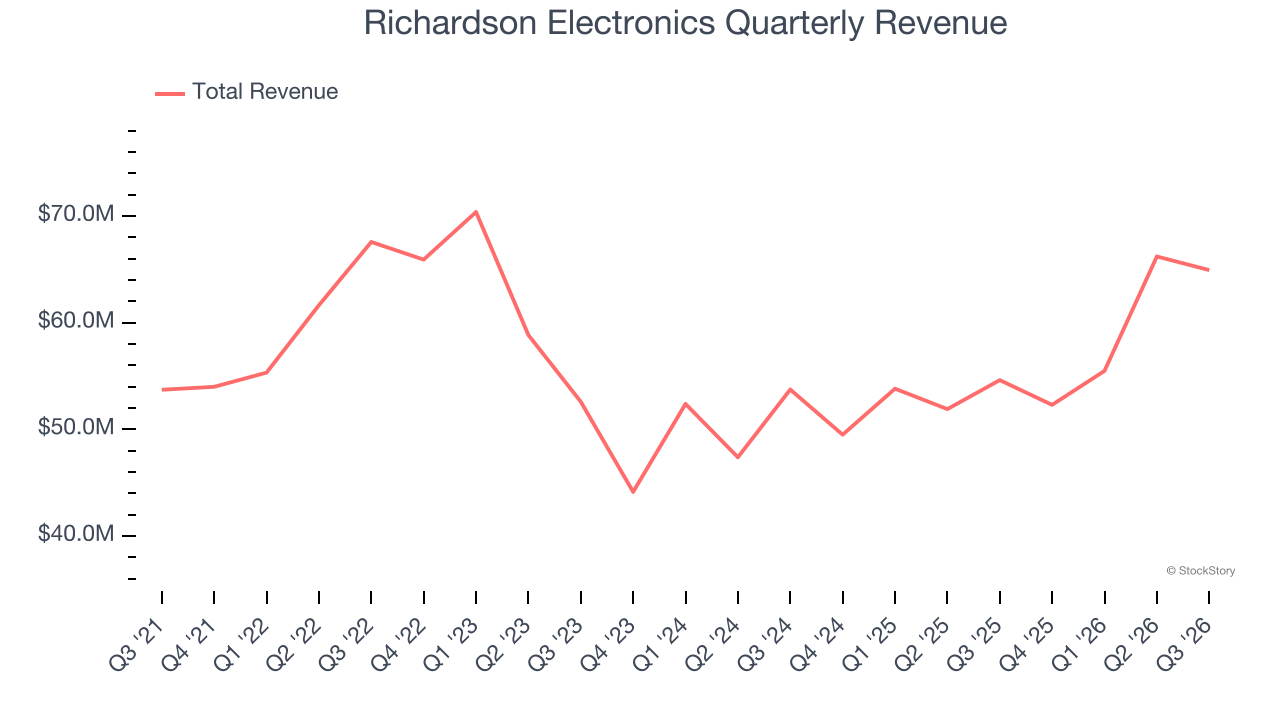
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. Richardson Electronics’s annualized revenue growth of 9.9% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 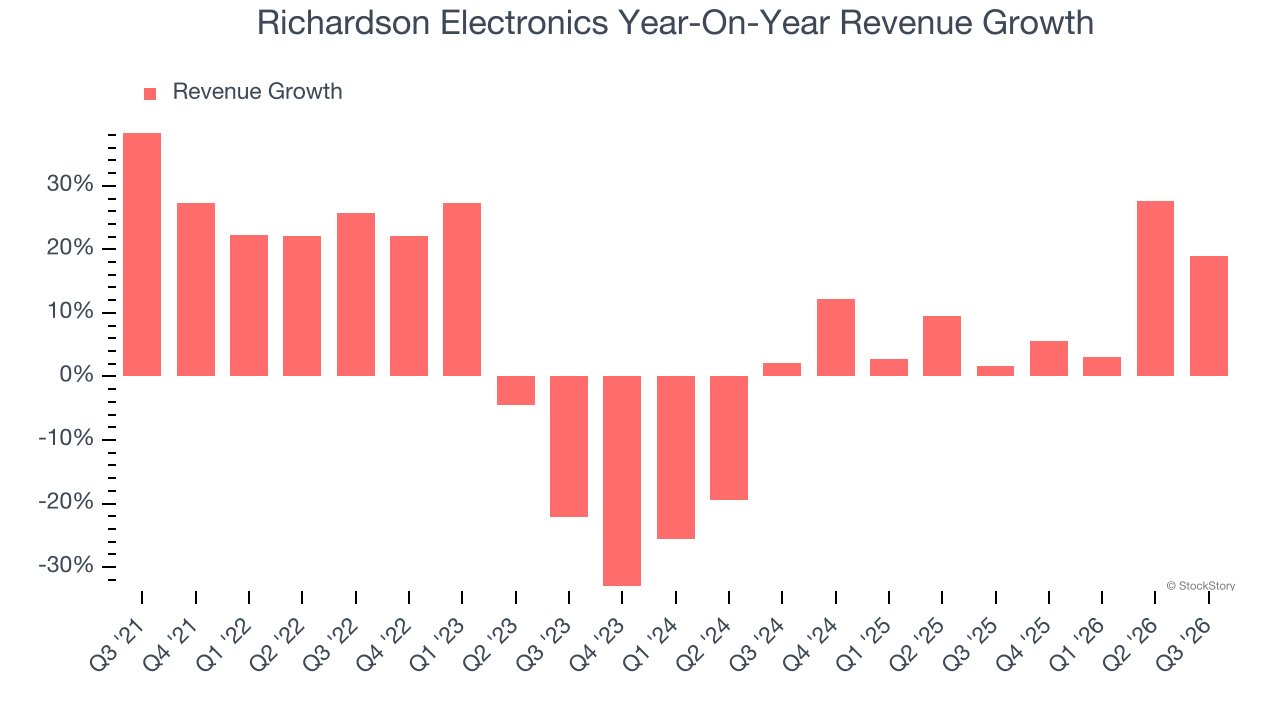
We can dig further into the company’s revenue dynamics by analyzing its backlog, or the value of its outstanding orders that have not yet been executed or delivered. Richardson Electronics’s backlog reached $184.4 million in the latest quarter and averaged 13.1% year-on-year growth over the last two years. Because this number is better than its revenue growth, we can see the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for Richardson Electronics’s products and services but raises concerns about capacity constraints. 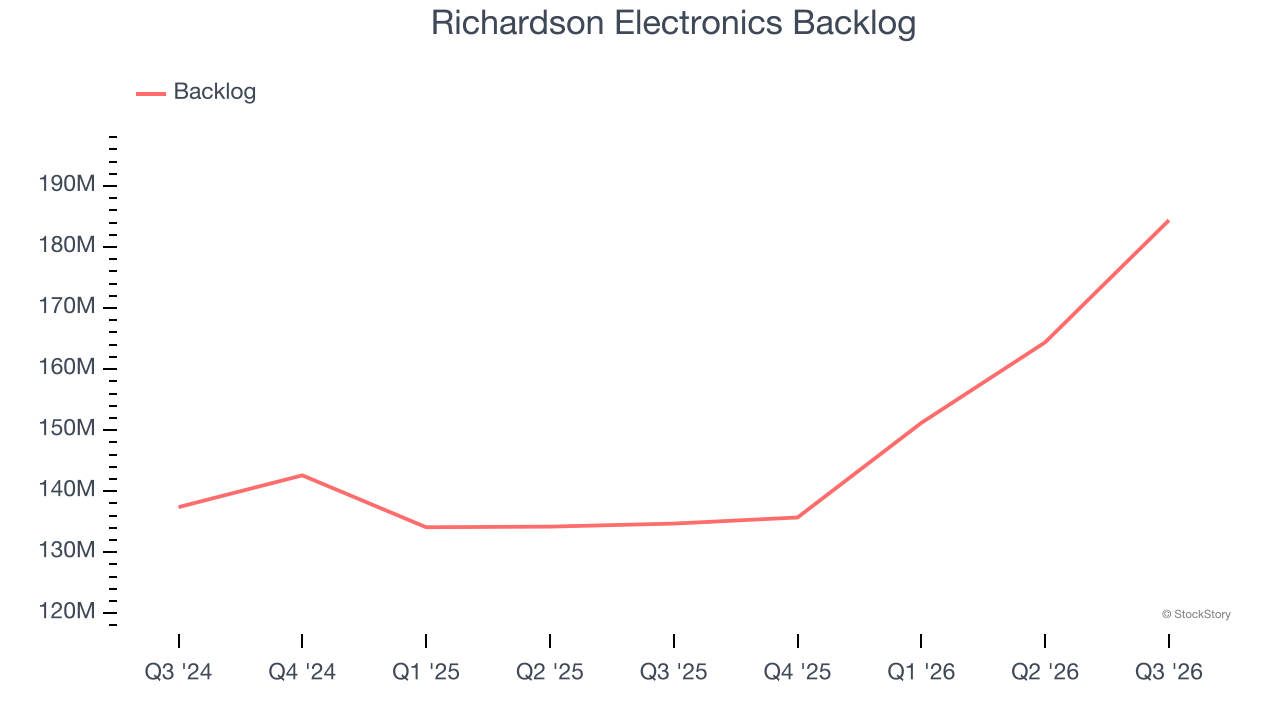
This quarter, Richardson Electronics reported year-on-year revenue growth of 18.9%, and its $64.92 million of revenue exceeded Wall Street’s estimates by 10.1%.
Looking ahead, sell-side analysts expect revenue to grow 4.8% over the next 12 months, a deceleration versus the last two years. This projection doesn’t excite us and indicates its products and services will see some demand headwinds.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Operating Margin
Richardson Electronics was profitable over the last five years but held back by its large cost base. Its average operating margin of 4.5% was weak for an industrials business.
Analyzing the trend in its profitability, Richardson Electronics’s operating margin decreased by 5.1 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Richardson Electronics’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers.
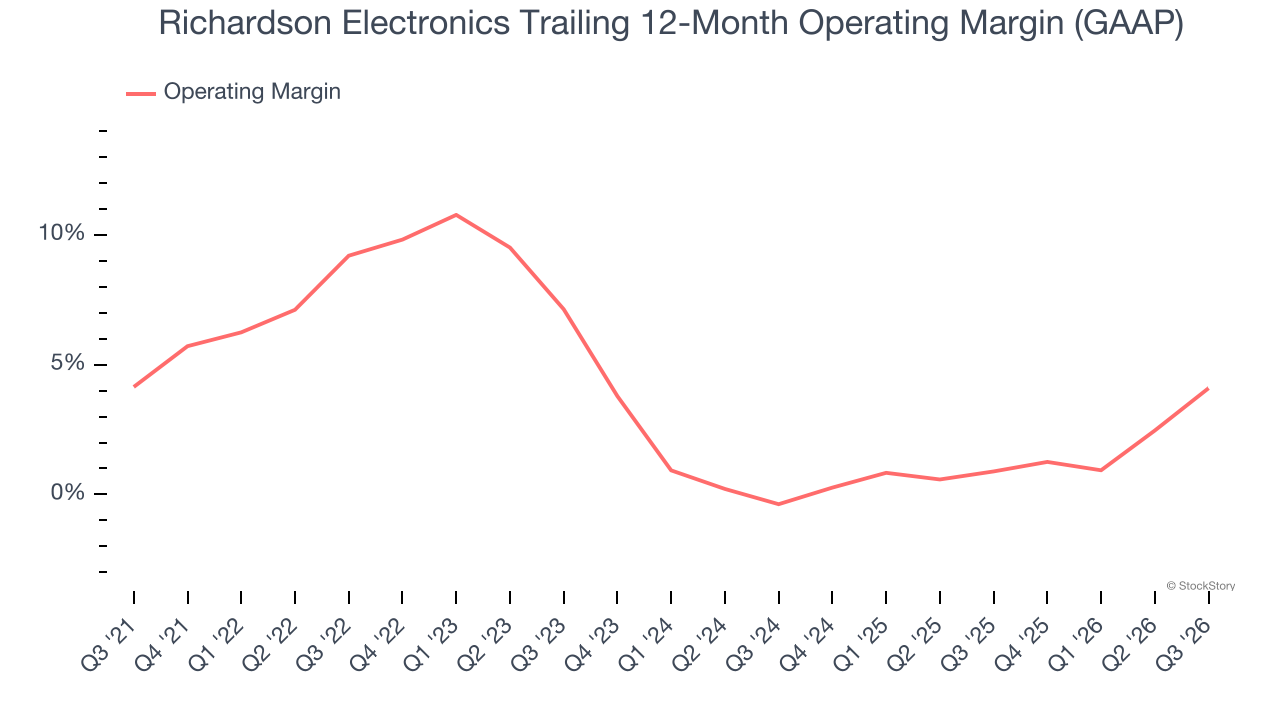
In Q3, Richardson Electronics generated an operating margin profit margin of 7.9%, up 6.1 percentage points year on year. The increase was solid, and because its operating margin rose more than its gross margin, we can infer it was more efficient with expenses such as marketing, R&D, and administrative overhead.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Richardson Electronics’s full-year EPS dropped 88.1%, or 17.1% annually, over the last four years. We tend to steer our readers away from companies with falling revenue and EPS, where diminishing earnings could imply changing secular trends and preferences. If the tide turns unexpectedly, Richardson Electronics’s low margin of safety could leave its stock price susceptible to large downswings.
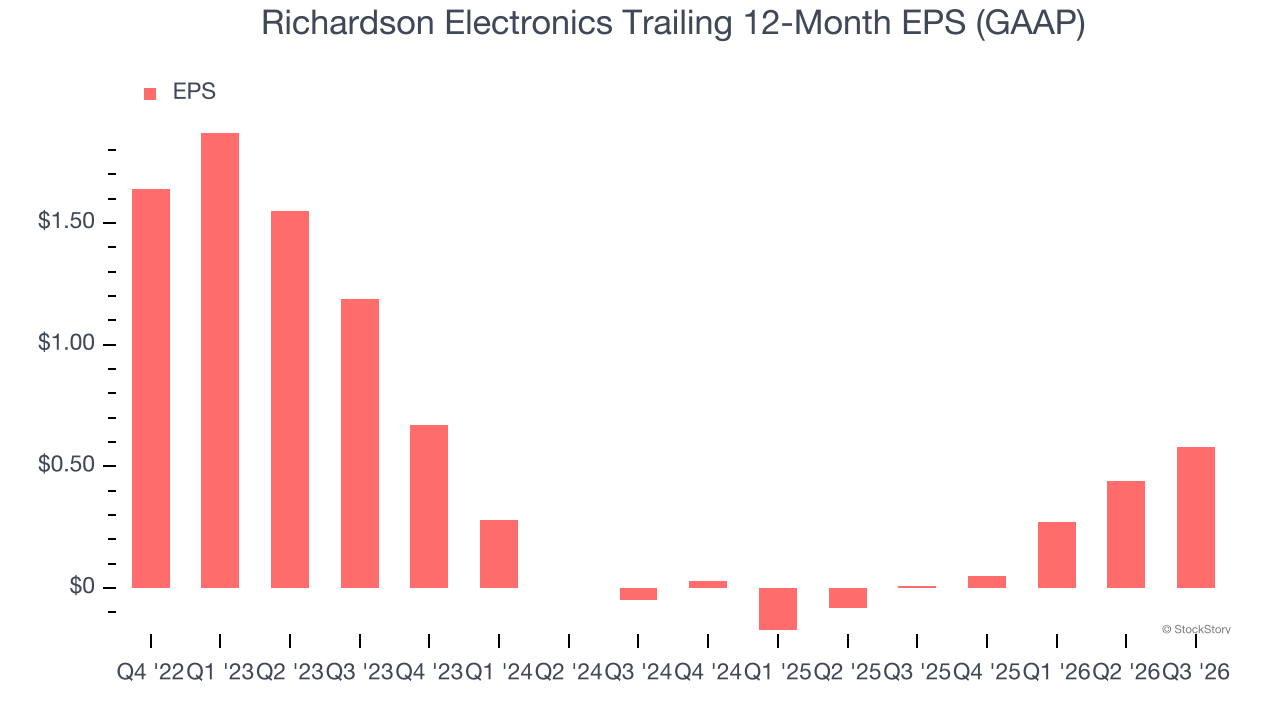
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Richardson Electronics, its two-year annual EPS growth of 269% was higher than its four-year trend. This acceleration made it one of the faster-growing industrials companies in recent history.
In Q3, Richardson Electronics reported EPS of $0.27, up from $0.13 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects Richardson Electronics’s full-year EPS to shrink by 1.7% from $0.58 to $0.57.
Key Takeaways from Richardson Electronics’s Q3 Results
It was good to see Richardson Electronics beat analysts’ EPS expectations this quarter. We were also excited its revenue outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this was a good print with some key areas of upside. The stock traded up 1.8% to $20.62 immediately following the results.
Richardson Electronics put up rock-solid earnings, but one quarter doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).