Packaged snacks company Mondelez (NASDAQ: MDLZ) met Wall Street’s revenue expectations in Q3 2026, with revenue rising 2.3% year on year to $9.97 billion. Its non-GAAP profit of $0.78 per share was 10.2% above analysts’ consensus estimates.
For more on Mondelez, read our free full research report.
Mondelez (MDLZ) Q3 2026 highlights:
- Revenue $9.97 billion vs S&P analysts’ consensus estimates of $9.97 billion (2.3% year-on-year growth, in line)
- Adjusted EPS $0.78 vs S&P analysts’ consensus estimates of $0.71 (10.2% beat)
- Operating margin 17.6%, up from 7.6% in the same quarter last year
- Free cash flow margin 9.9%, up from 4.3% in the same quarter last year
- Organic revenue rose 2.1% year on year (miss)
- Sales volumes rose 1.8% year on year (-4.6% in the same quarter last year)
- Market capitalization $78.97 billion
“We delivered strong third-quarter results, driven by broad based volume growth and robust share performance. We continue to see top- and bottom-line growth momentum across both developed and emerging markets, while significantly reinvesting in our brands, innovation, and distribution,” said Dirk Van de Put, Chairman and Chief Executive Officer. "We are resolute in delivering volume-led, compounding earnings growth that creates value for shareholders. We remain confident that our attractive categories, iconic brands, advantaged geographic footprint, and consumer-centric capabilities will sustain our performance for years to come.
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Even a poor business can perform well for one or two quarters, but a high-quality one grows for years.
With $39.9 billion in revenue over the past 12 months, Mondelez is one of the most widely recognized consumer staples companies. Its influence over consumers gives it negotiating leverage with distributors, enabling it to choose where it sells its products, an advantage many companies lack. However, its scale is a double-edged sword because there are only so many big store chains to sell into, making it harder to find incremental growth. To accelerate revenue growth, Mondelez likely needs to optimize its pricing or focus on new products and international expansion.
Mondelez’s revenue grew at a tepid 4.7% compounded annual growth rate over the last three years as consumers bought less of its products. We’ll explore what this means in the “Volume Growth” section.
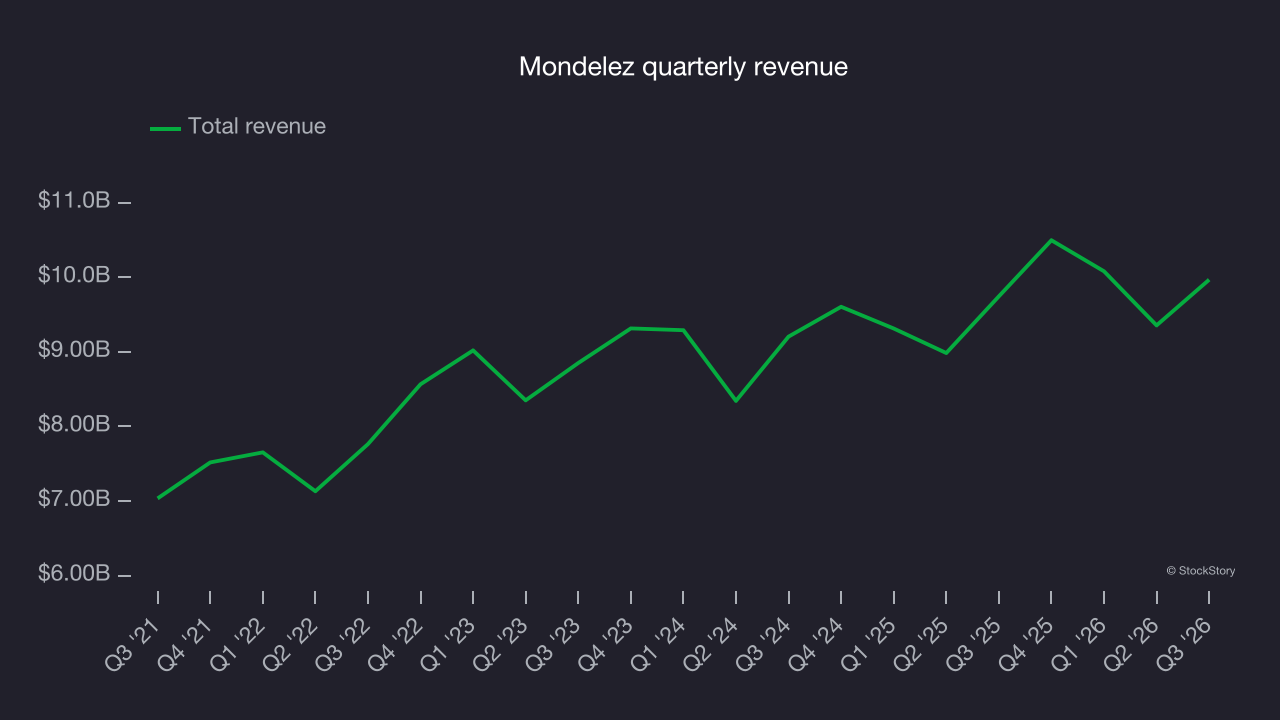
This quarter, Mondelez grew its revenue by 2.3% year on year, and its $9.97 billion of revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 2.4% over the next 12 months, according to S&P, a slight deceleration versus the last three years. This underwhelming projection indicates its products will face some demand headwinds.
Volume growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is central to a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
Mondelez’s average quarterly sales volumes have shrunk by 1.9% over the last two years. This decrease isn’t ideal because the quantity demanded for consumer staples products is typically stable.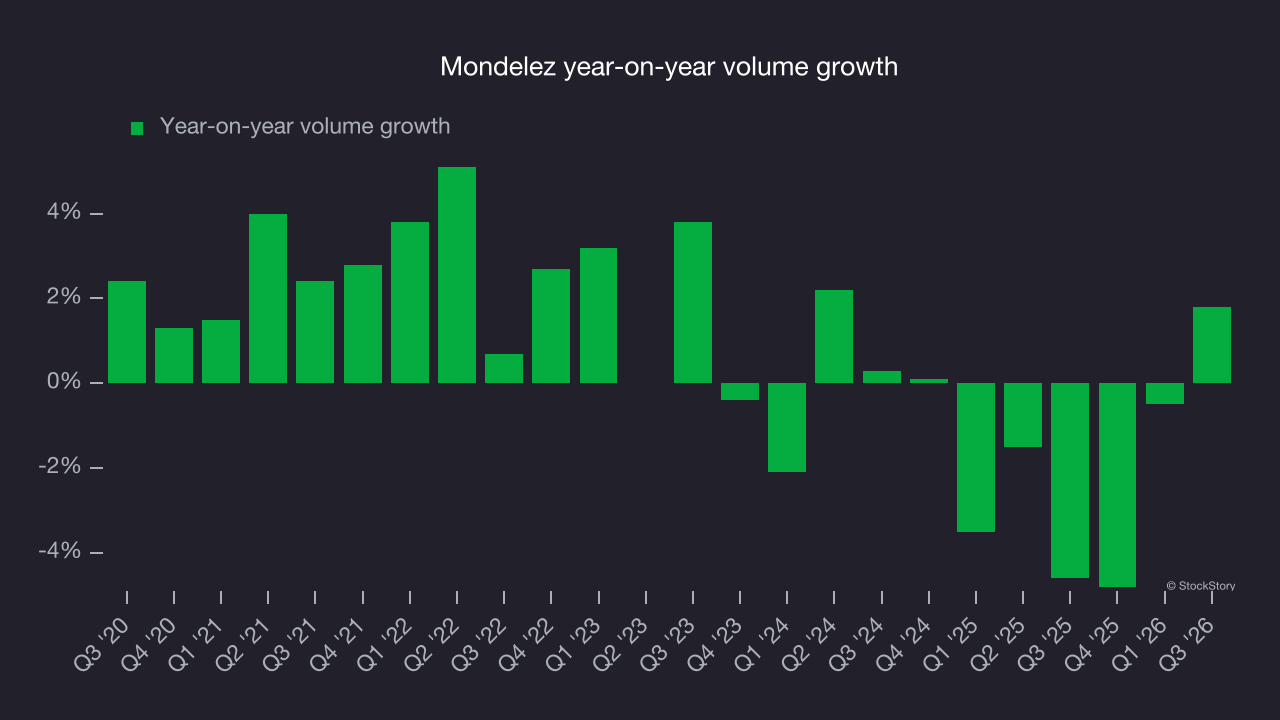
In Mondelez’s Q3 2026, sales volumes edged higher 1.8% year on year. This marked a positive turnaround from its historical levels, showing the company is heading in the right direction.
Key takeaways from Mondelez’s Q3 results
Mondelez’s Q3 results were mixed: EPS also topped Wall Street’s estimates but revenue was roughly in-line. Shares rose 3.2% to $64.53 immediately after the release.
The latest quarter matters when deciding whether to buy the stock, but not nearly as much as longer-term fundamentals and valuation. Read our full research report here for more on these factors (it’s free).