Dialysis provider DaVita Inc. (NYSE: DVA) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 4.6% year on year to $3.58 billion. Its non-GAAP profit of $3.82 per share was 6.9% above analysts’ consensus estimates.
For more on DaVita, read our free full research report.
DaVita (DVA) Q3 2026 highlights:
- Revenue $3.58 billion vs S&P analysts’ consensus estimates of $3.52 billion (4.6% year-on-year growth, 1.7% beat)
- Adjusted EPS $3.82 vs S&P analysts’ consensus estimates of $3.57 (6.9% beat)
- Adjusted EPS guidance Management slightly raised its full-year adjusted EPS guidance to $14.75 at the midpoint
- Operating margin 14%, in line with the same quarter last year
- Free cash flow margin 7.7%, down from 19.7% in the same quarter last year
- Sales volumes rose 1.2% year on year (-1.5% in the same quarter last year)
- Market capitalization $11.73 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. DaVita’s revenue grew at a mediocre 4.1% annualized rate over the last five years, falling short of the healthcare sector standard.
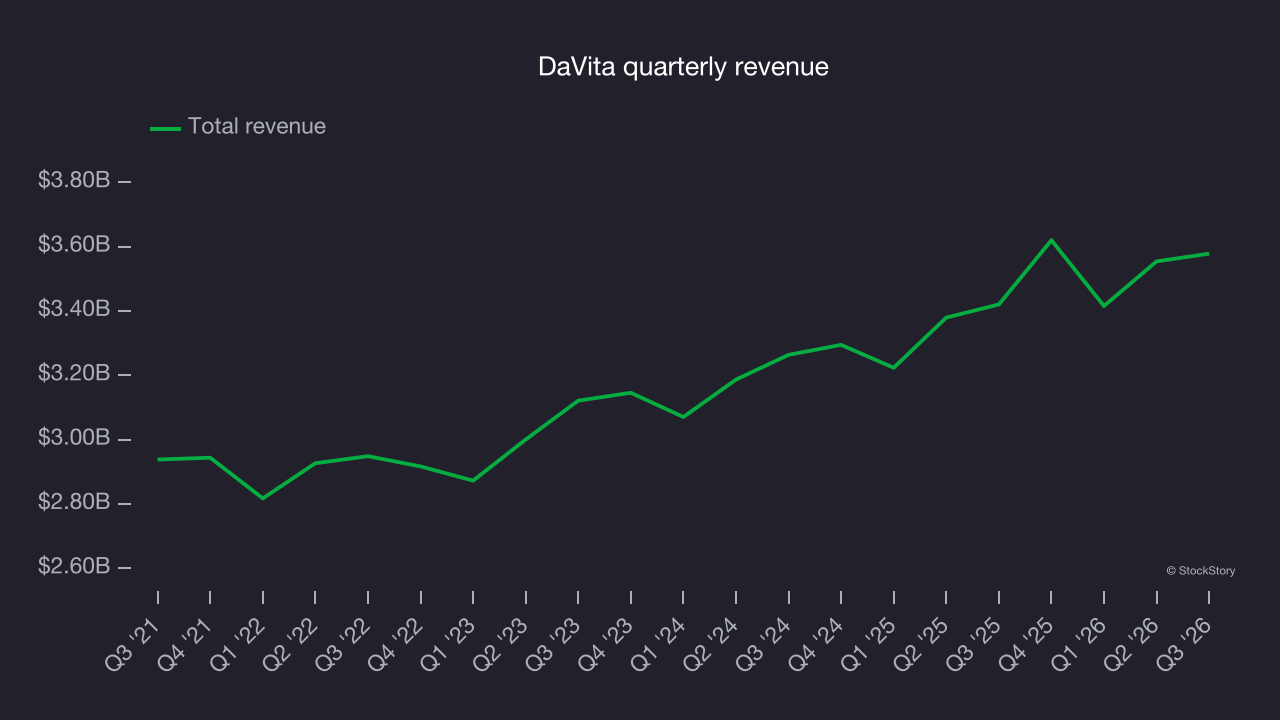
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. DaVita’s annualized revenue growth of 5.8% over the last two years is above its five-year trend, which is encouraging. 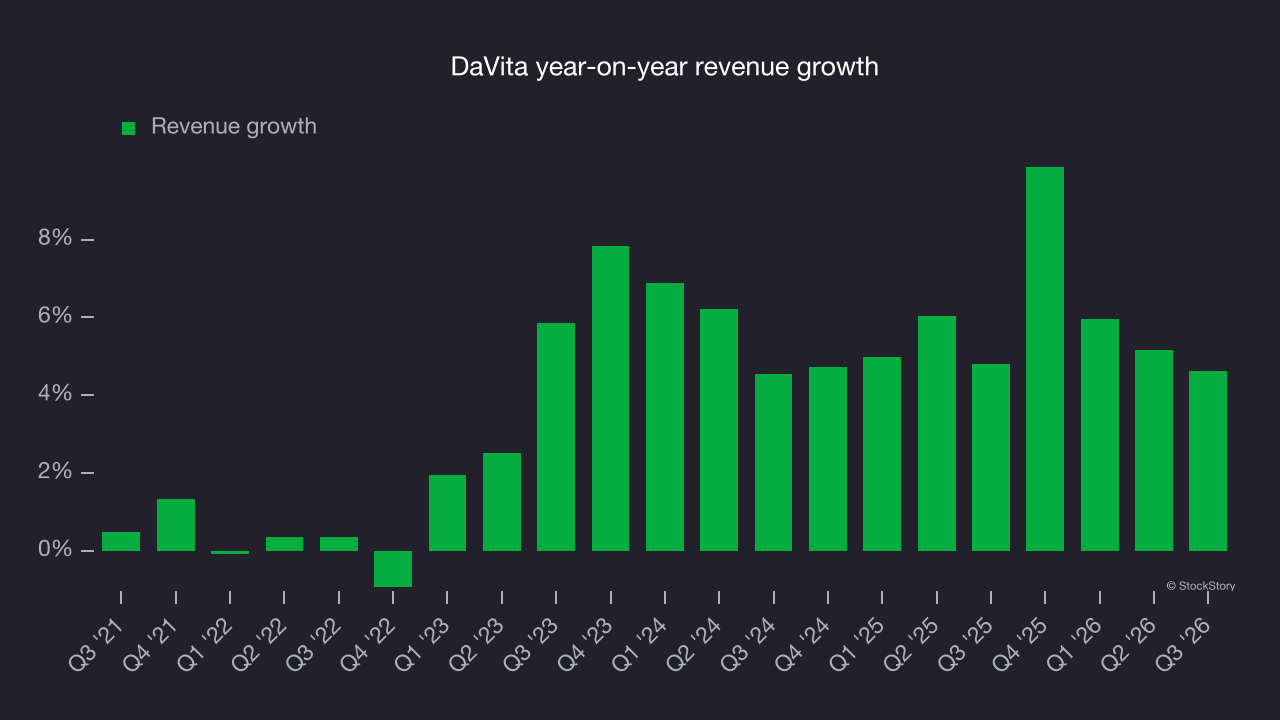
We can better understand the company’s revenue dynamics by analyzing its number of treatments, which reached 7.33 million in the latest quarter. Over the last two years, DaVita’s treatments were flat. Revenue growth outpaced treatment growth, indicating that the company benefited from price increases. 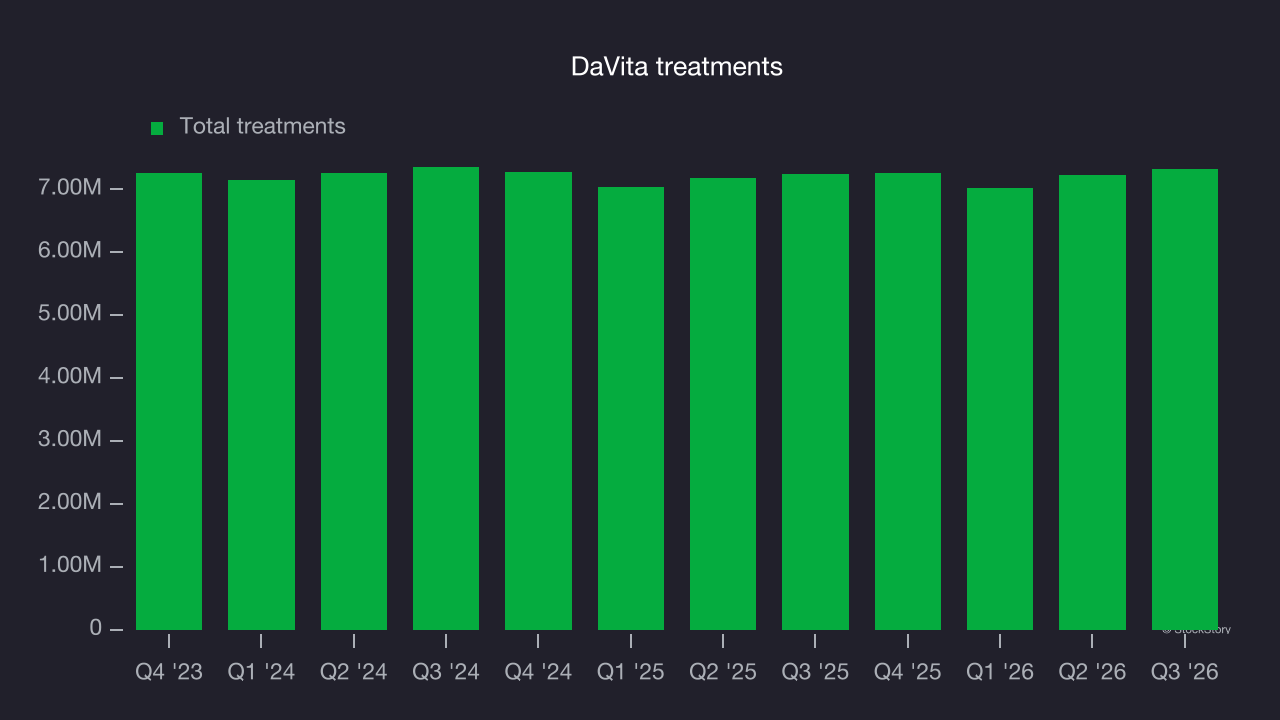
This quarter, DaVita reported modest year-on-year revenue growth of 4.6% but beat Wall Street’s consensus estimates by 1.7%.
Looking ahead, sell-side analysts expect revenue to grow 1.8% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will face some demand challenges.
Adjusted operating margin
DaVita has done a decent job managing its cost base over the last five years. The company has produced an average adjusted operating margin of 14.5%, higher than the broader healthcare sector.
Analyzing the trend in its profitability, DaVita’s adjusted operating margin rose by 2.3 percentage points over the last five years, as its revenue growth gave it operating leverage.
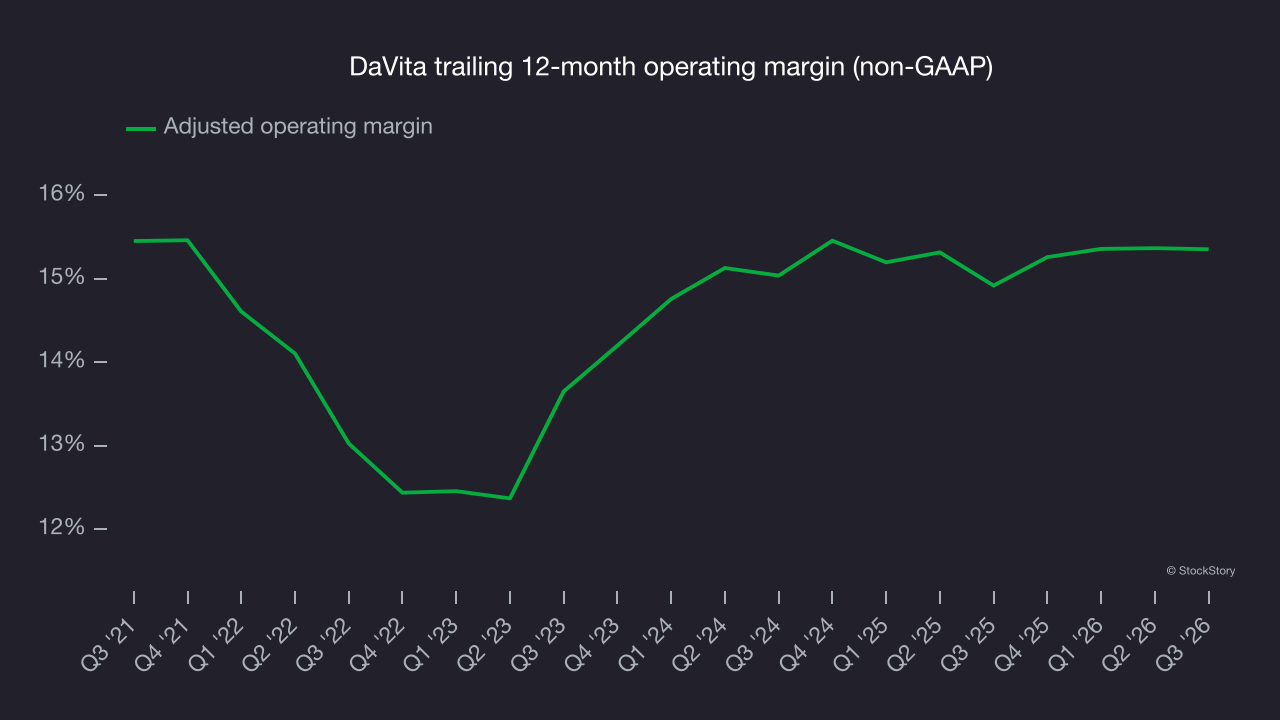
In Q3, DaVita generated an adjusted operating margin of 14.8%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
DaVita’s EPS grew at a 10% compounded annual growth rate over the last five years, higher than its 4.1% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
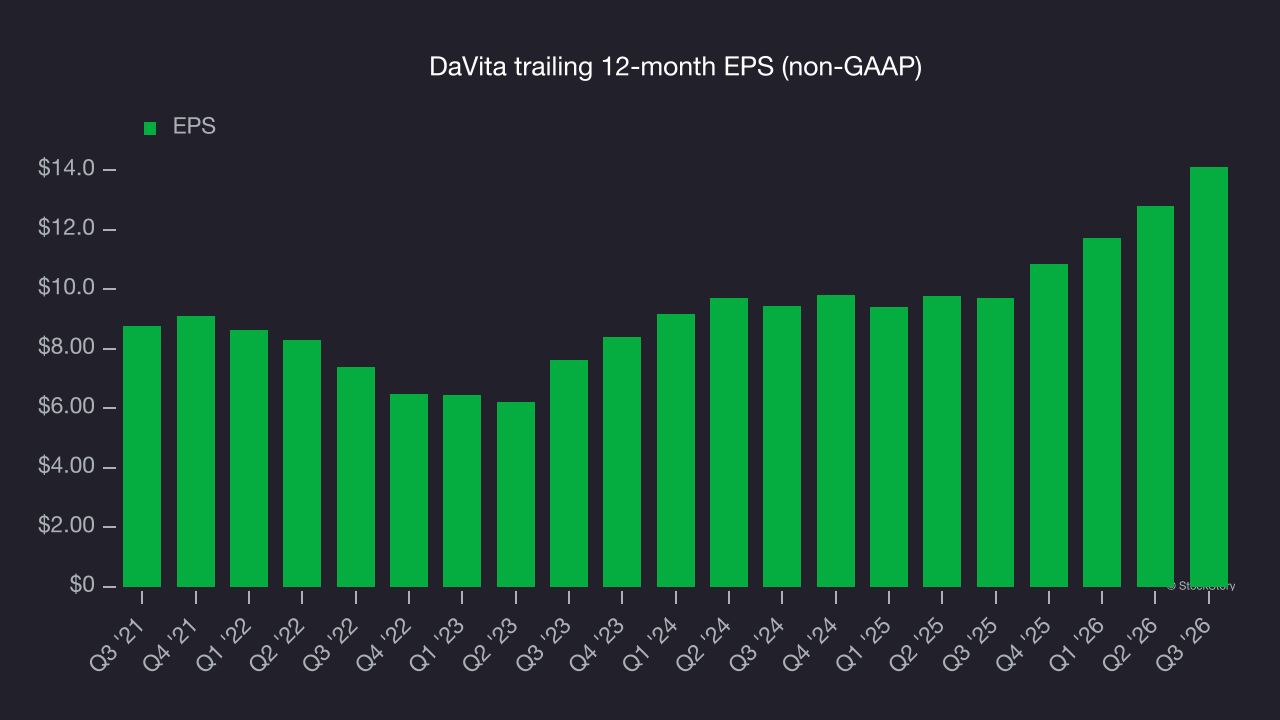
We can take a deeper look into DaVita’s earnings to better understand the drivers of its performance. As we mentioned earlier, DaVita’s adjusted operating margin was flat this quarter but expanded by 2.3 percentage points over the last five years. On top of that, its share count shrank by 40.4%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 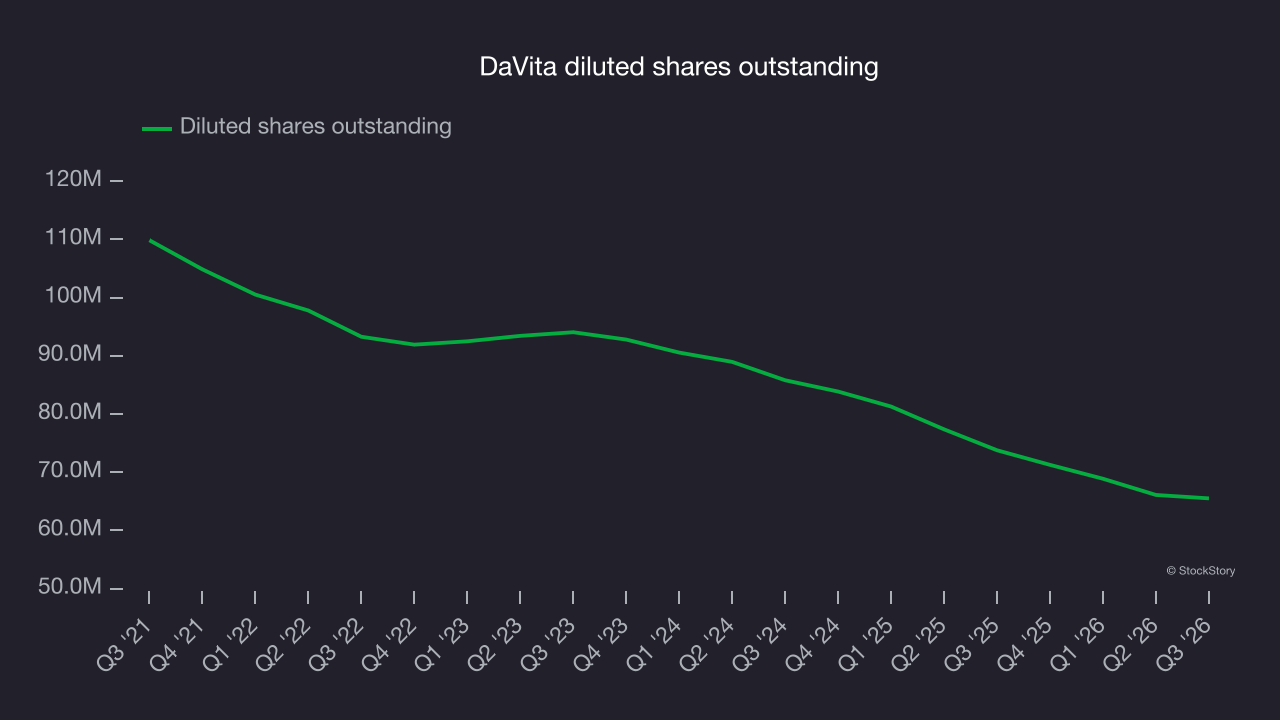
In Q3, DaVita reported adjusted EPS of $3.82, up from $2.51 in the same quarter last year. This result beat analysts’ consensus estimates by 6.9%. Over the next 12 months, Wall Street expects DaVita’s full-year EPS to grow 14.8% from $14.11 to $16.20, according to S&P.
Key takeaways from DaVita’s Q3 results
DaVita’s revenue and EPS beat consensus estimates, giving the quarter some key positives, but its full-year EPS guidance fell slightly short. The market appeared to be hoping for more: Shares tumbled 6.2% to $181.26 immediately after the results.
DaVita’s latest quarter matters, but longer-term business quality and valuation matter more when deciding whether to invest in the stock now. Read our full research report here (it’s free).