Elevator manufacturer Otis (NYSE: OTIS) announced better-than-expected revenue in Q3 2026, with revenue up 6.1% year on year to $3.91 billion. On the other hand, the company’s full-year revenue guidance of $15.2 billion at the midpoint came in 0.7% below analysts’ consensus estimates. Its non-GAAP profit of $1.05 per share was 3.5% above analysts’ consensus estimates.
For more on Otis, read our free full research report.
Otis (OTIS) Q3 2026 highlights:
- Revenue $3.91 billion vs S&P analysts’ consensus estimates of $3.86 billion (6.1% year-on-year growth, 1.4% beat)
- Adjusted EPS $1.05 vs S&P analysts’ consensus estimates of $1.01 (3.5% beat)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $15.2 billion at the midpoint
- Adjusted EPS guidance Management reiterated its full-year adjusted EPS guidance of $4.03 at the midpoint
- Operating margin 15.8%, in line with the same quarter last year
- Free cash flow margin 7.6%, down from 9.1% in the same quarter last year
- Organic revenue rose 6% year on year (beat)
- Market capitalization $28.24 billion
"Otis delivered another quarter of strong top-line growth, supported by sustained performance across all Service lines and growth in New Equipment. Our investments in field capability and AI-enabled pricing, combined with disciplined execution, continue to support double digit modernization growth and high single digit repair growth. Alongside our focus on service quality, reliability, uptime, and cost control, these actions drove the incremental increase in Service margin to above 24%," said Chair, CEO & President Judy Marks. "The third quarter Service revenue growth and sequential margin improvement continue to reinforce our Service flywheel strategy and give us confidence in the steps we are taking to build a stronger foundation for sustained growth."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Otis’s revenue grew at a weak 1.3% annualized rate over the last five years, falling short of our standards.
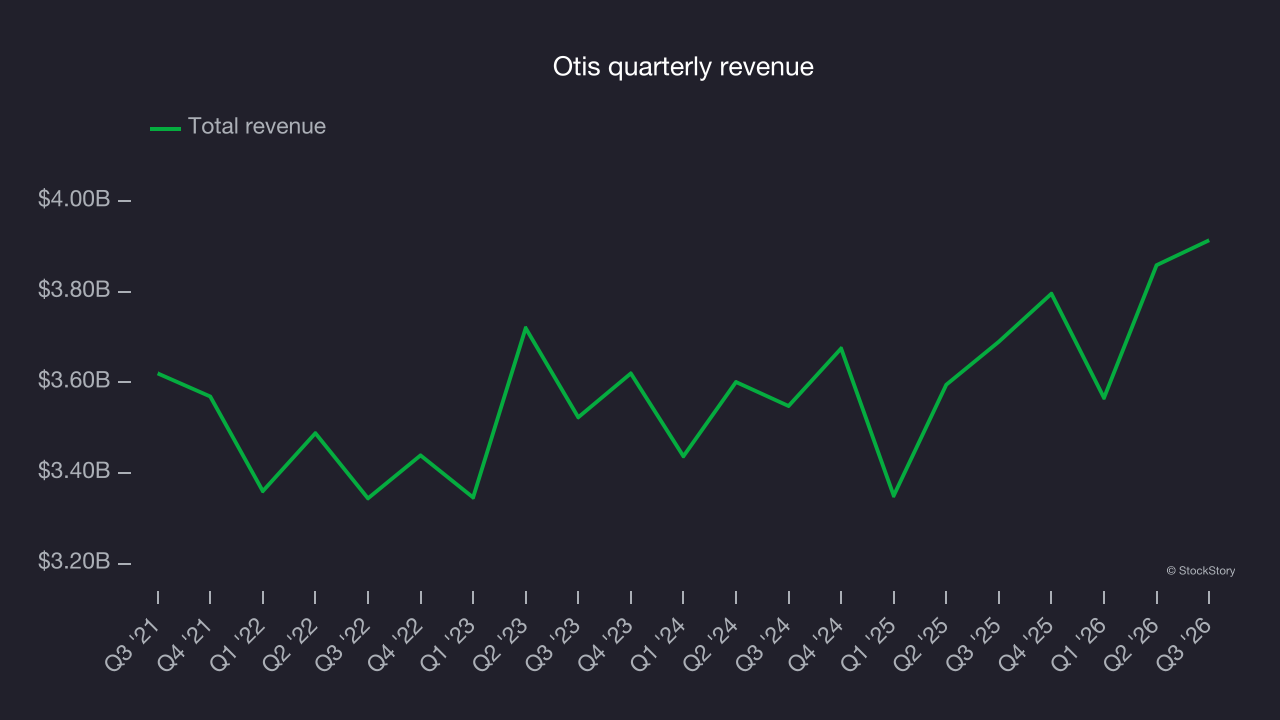
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Otis’s annualized revenue growth of 3.2% over the last two years is above its five-year trend, a positive sign. 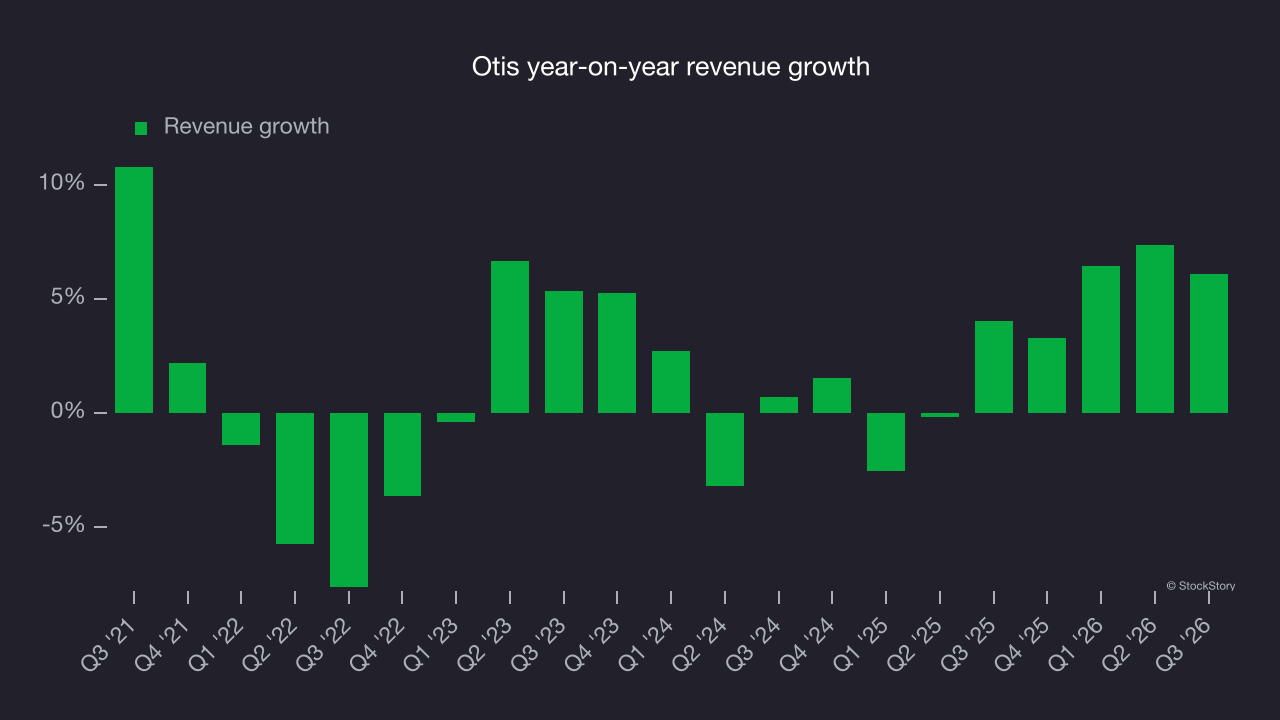
Organic revenue helps explain the company’s revenue dynamics by stripping out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Otis’s organic revenue averaged 2% year-on-year growth. This was in line with its two-year revenue growth, indicating that core operations, rather than acquisitions and divestitures, drove most of its results. 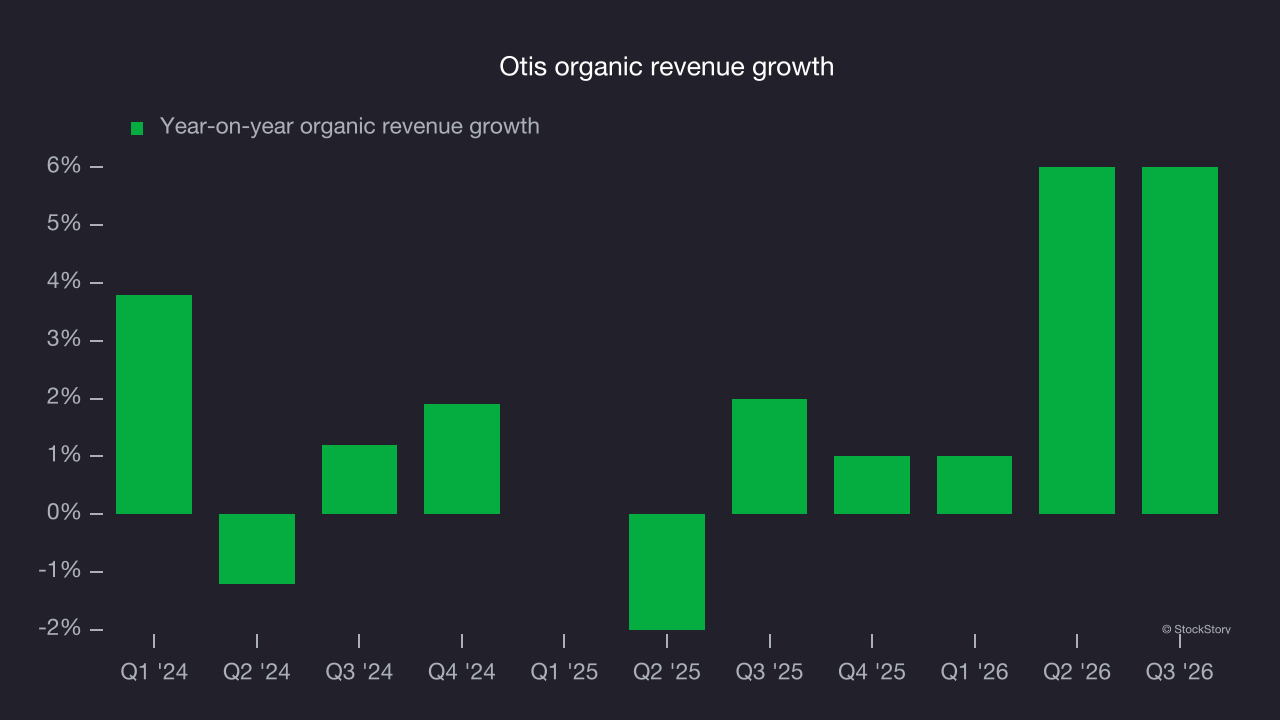
This quarter, Otis reported year-on-year revenue growth of 6.1%, and its $3.91 billion of revenue exceeded Wall Street’s consensus estimates by 1.4%.
Looking ahead, sell-side analysts expect revenue to grow 3.6% over the next 12 months, according to S&P, similar to its two-year rate. This projection is underwhelming and implies its newer products and services will not lead to better top-line performance yet.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Otis’s operating margin has more or less stayed the same over the last 12 months, averaging 14.8% over the last five years. This profitability was strong for an industrials business, showing it’s a well-run company with an efficient cost structure. This result was particularly impressive given its low gross margin, which largely reflects what it sells and requires significant shifts to change meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins point to well-managed operations.
Otis’s operating margin may have fluctuated slightly, but it has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
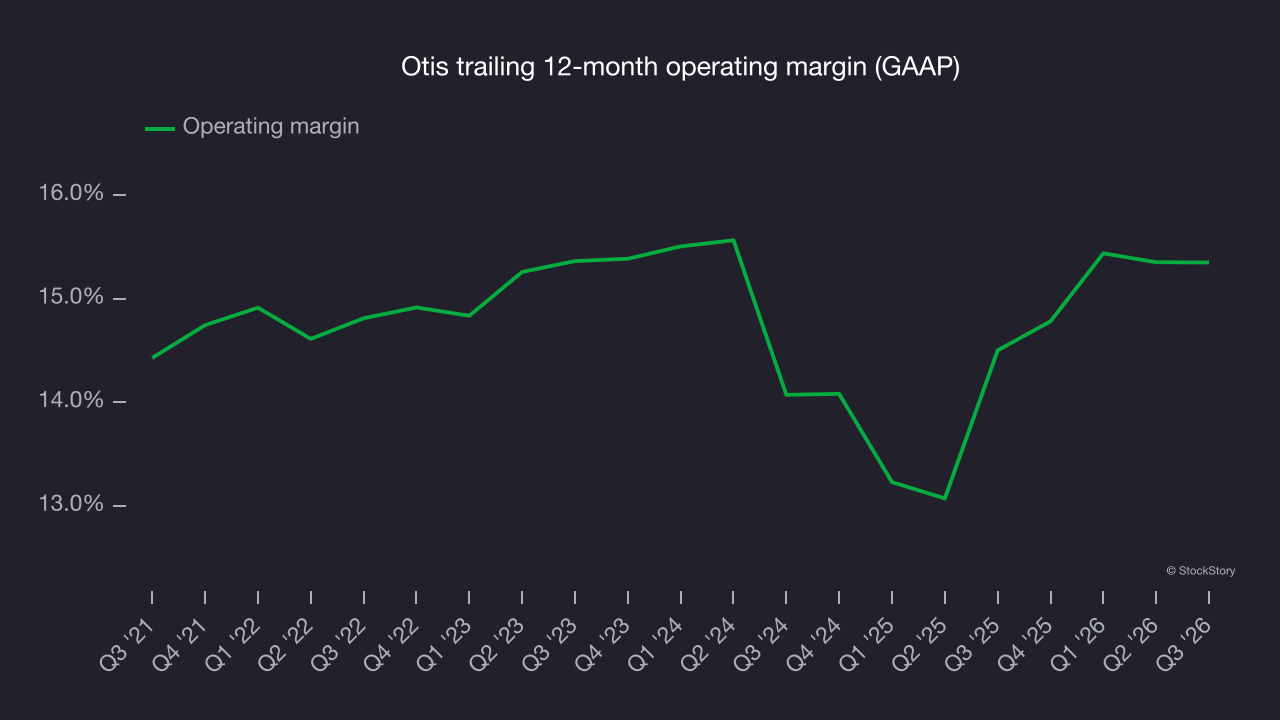
In Q3, Otis generated an operating margin of 15.8%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Otis’s EPS grew at a 6.2% compounded annual growth rate over the last five years. This performance was better than its revenue growth but doesn’t tell us much about its business quality because its operating margin improvement lagged peers.
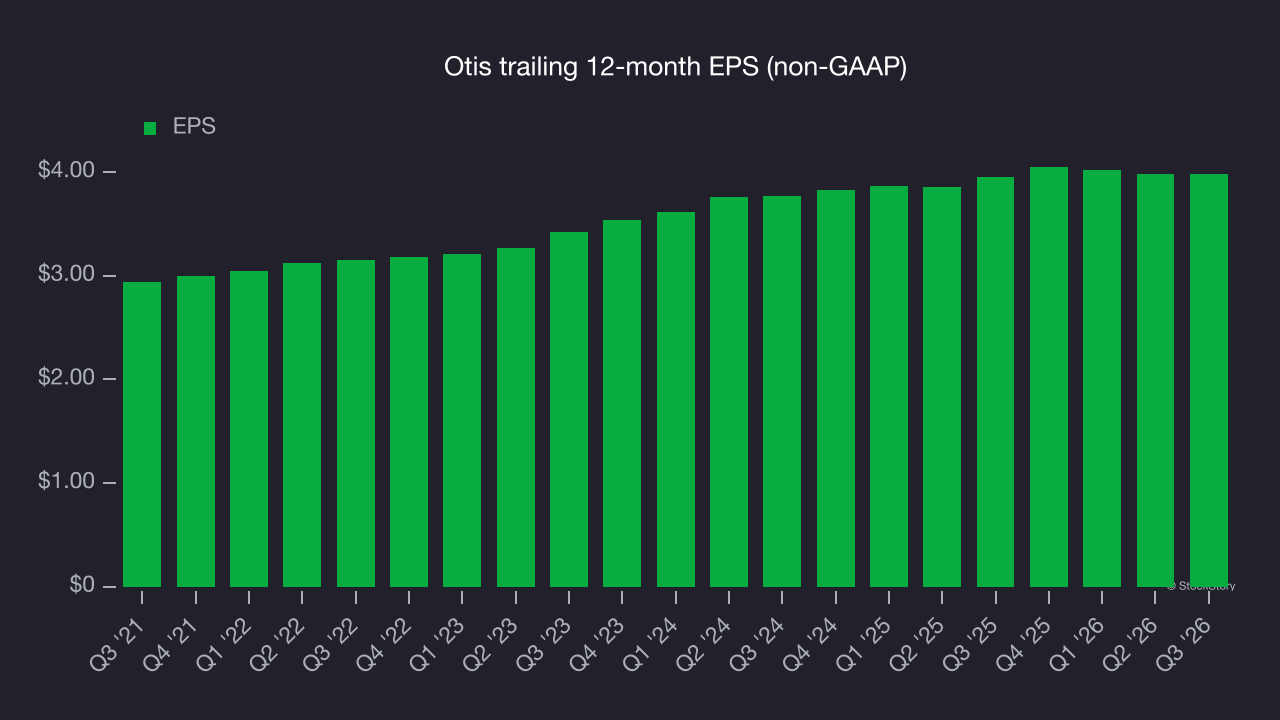
A closer look at Otis’s earnings helps explain the drivers of its performance. A five-year view shows that Otis has repurchased its stock, shrinking its share count by 11.3%. This indicates its EPS outperformed its revenue not because of increased operational efficiency but because of financial engineering, as buybacks boost per share earnings. 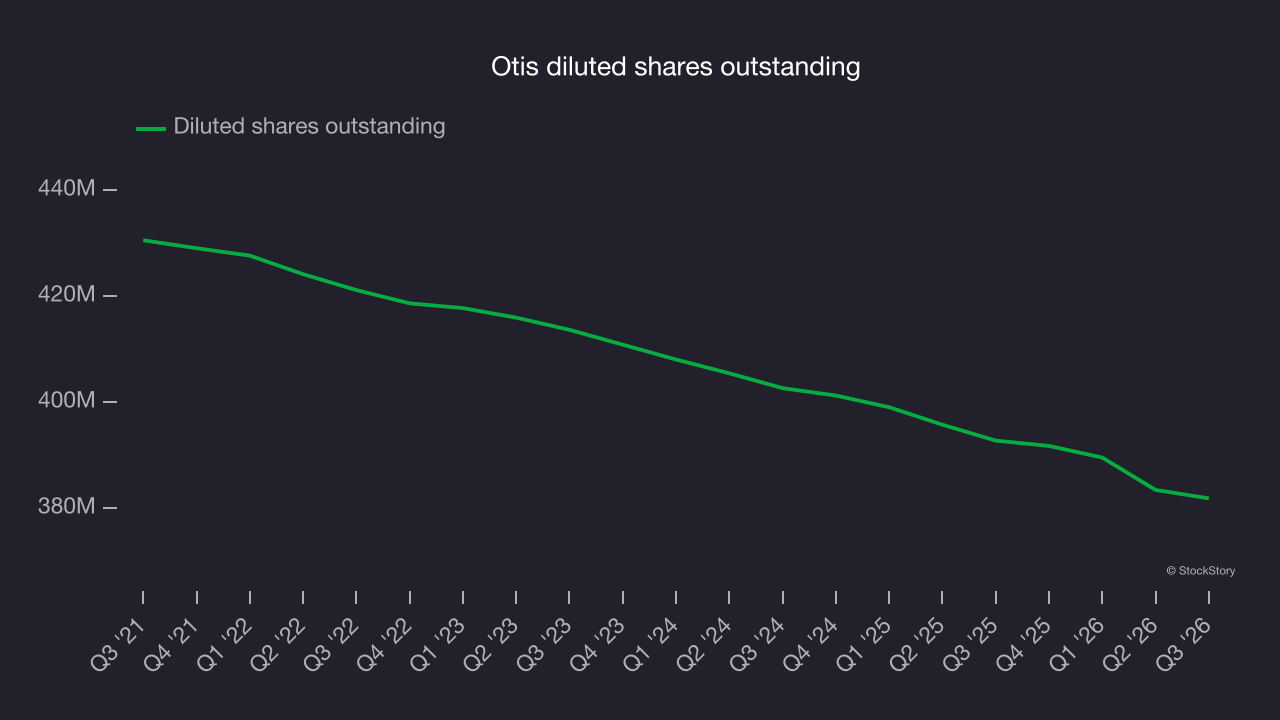
As with revenue, analyzing EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Otis, its two-year annual EPS growth of 2.7% was lower than its five-year trend.
In Q3, Otis reported adjusted EPS of $1.05, in line with the same quarter last year. This result beat analysts’ consensus estimates by 3.5%. Over the next 12 months, Wall Street expects Otis’s full-year EPS to grow 8.7% from $3.98 to $4.32, according to S&P.
Key takeaways from Otis’s Q3 results
Otis delivered modest revenue beats in Q3, with both organic revenue and total revenue narrowly topping analysts’ consensus estimates. Those were key positives, but full-year revenue guidance fell slightly short of expectations. Shares remained flat at $74.31 immediately after the report.
The latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here (it’s free).