Home-building design and manufacturing company Masco Corporation (NYSE: MAS) beat Wall Street’s revenue expectations in Q3 2026, as revenue rose 2.6% year on year to $1.97 billion. Its non-GAAP profit of $1.19 per share was 16.1% above analysts’ consensus estimates.
For more on Masco, read the full research report for free.
Masco (MAS) Q3 2026 highlights:
- Revenue $1.97 billion vs S&P analysts’ consensus estimates of $1.93 billion (2.6% year-on-year growth, 2% beat)
- Adjusted EPS $1.19 vs S&P analysts’ consensus estimates of $1.03 (16.1% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $4.70 at the midpoint, a 4.4% increase
- Operating margin 17.2%, up from 15.8% in the same quarter last year
- Free cash flow margin 16.9%, down from 21.6% in the same quarter last year
- Organic revenue rose 4% year on year (beat)
- Market capitalization $14.76 billion
“Our strong third quarter results reflect the strength of our teams, the disciplined execution of our strategy, and the resilience of our business,” said Masco’s President and CEO, Jon Nudi. “We are executing well against our strategy, delivering above-market growth and building momentum throughout the organization. In the third quarter, net sales increased 3 percent, or 4 percent excluding the impacts of our divestiture and currency, adjusted operating margin expanded 160 basis points to 17.9 percent, and adjusted earnings per share grew 23 percent. In addition, we returned $322 million to shareholders through dividends and share repurchases, demonstrating the strength of our cash flow generation and our ongoing commitment to disciplined capital allocation and shareholder value creation.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can report a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Masco’s demand was weak and its revenue declined by 1.4% per year. That outcome points to poor business quality.
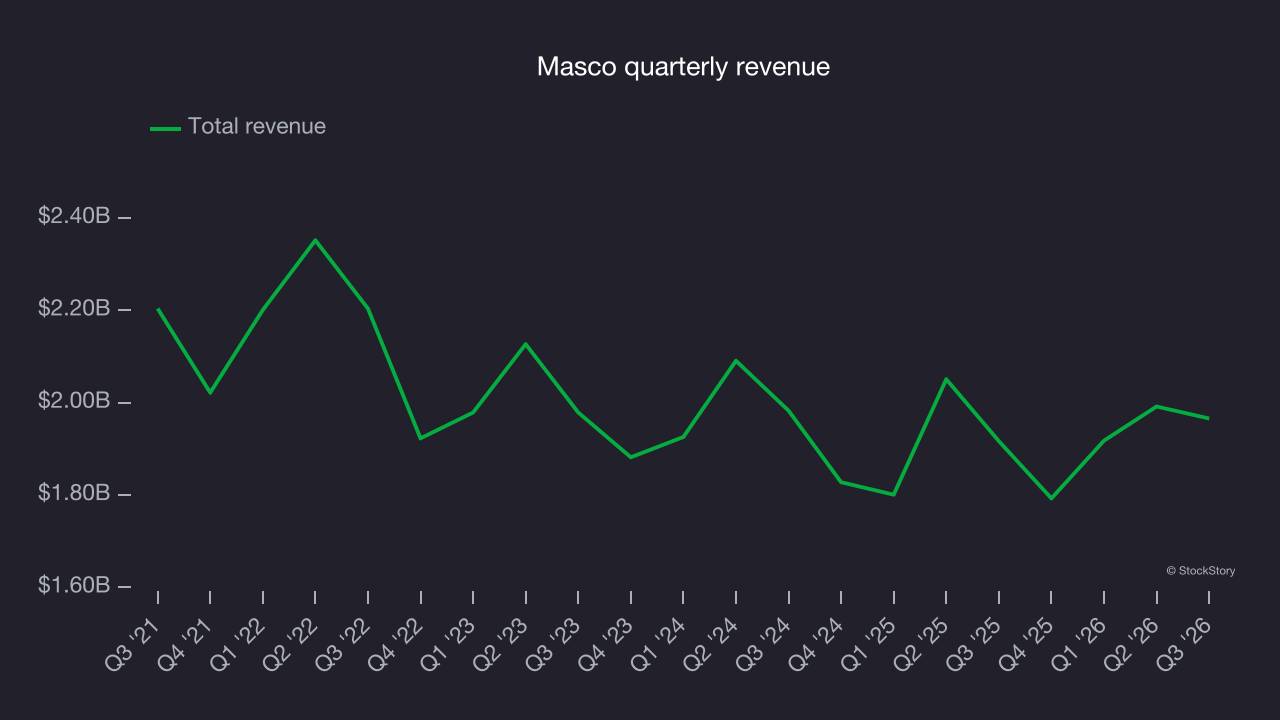
Long-term growth matters the most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Masco’s annualized revenue declines of 1.4% over the last two years align with its five-year trend, suggesting its demand has consistently shrunk. 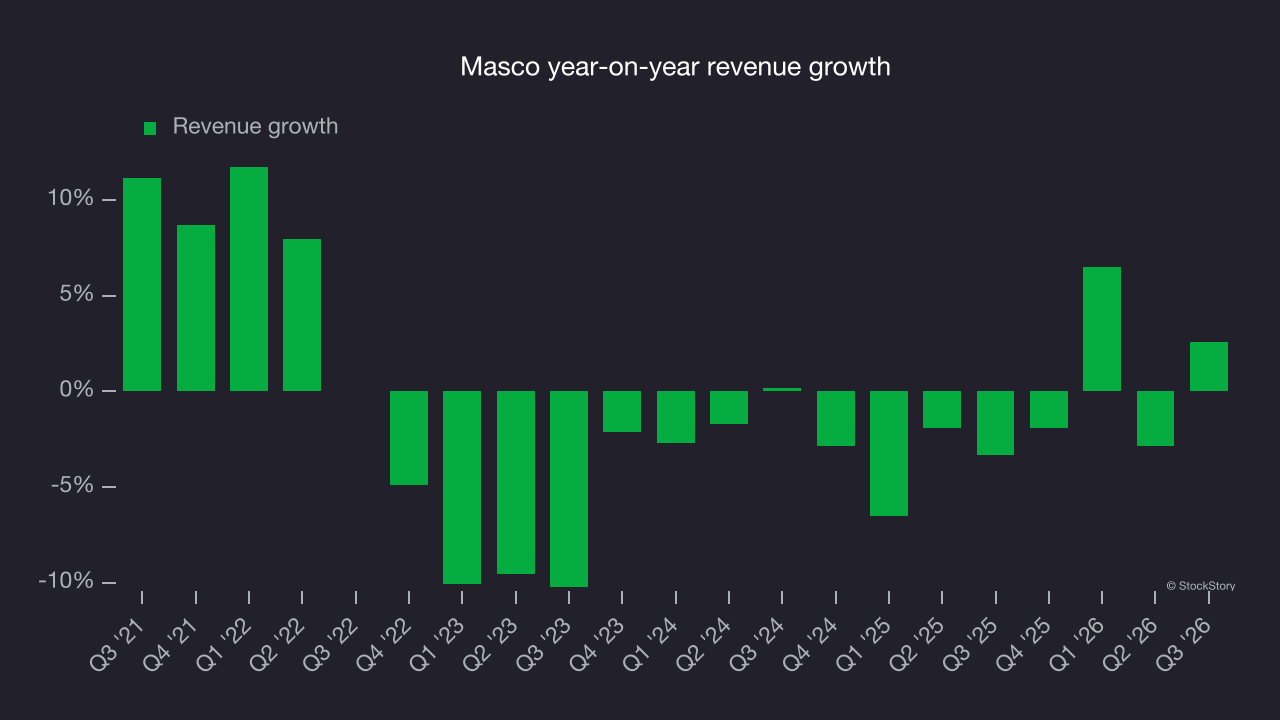
Organic revenue offers a closer look at the company’s revenue dynamics by stripping out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Masco’s organic revenue averaged 1.3% year-on-year growth. Organic growth outpaced its two-year revenue growth, indicating that some combination of divestitures and foreign exchange rates dampened its headline results. 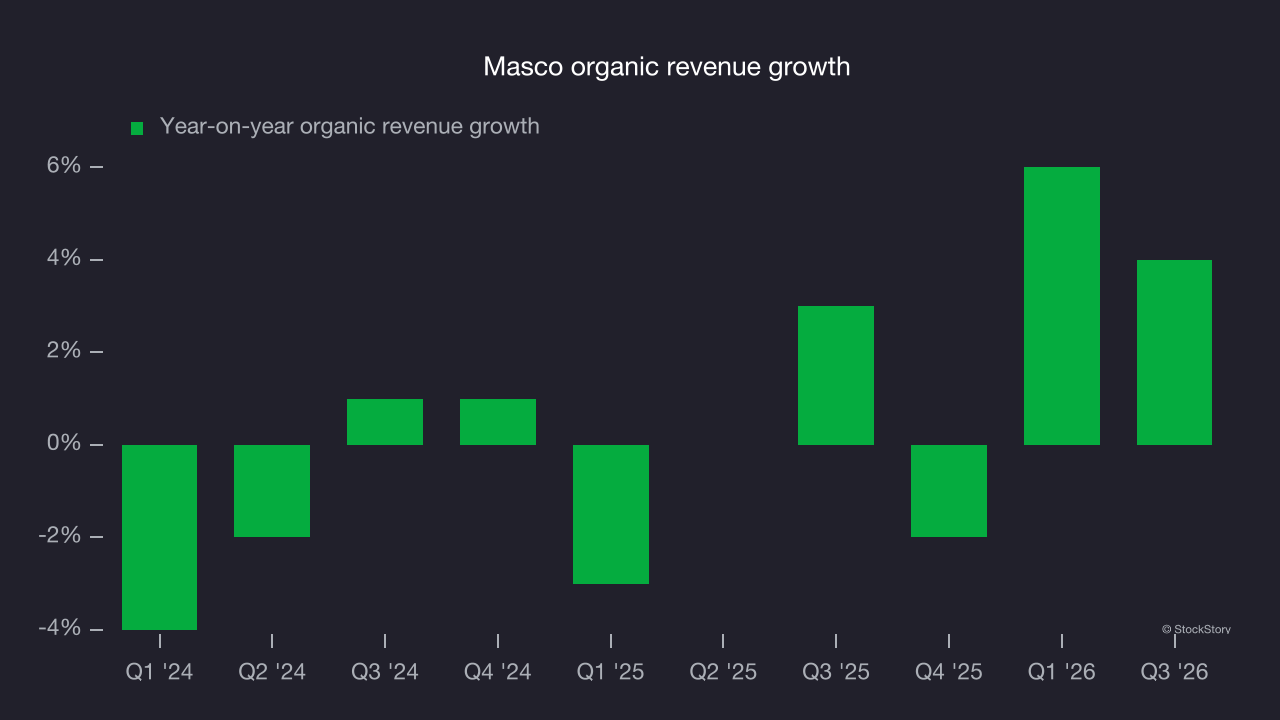
This quarter, Masco reported modest year-on-year revenue growth of 2.6% but beat Wall Street’s consensus estimates by 2%.
Looking ahead, sell-side analysts expect revenue to grow 1.3% over the next 12 months, according to S&P. Although this projection suggests its newer products and services will fuel better top-line performance, it is still below average for the sector.
Operating margin
Masco has operated efficiently over the last five years. It demonstrated high profitability for an industrials business, with an average operating margin of 16.5%. That outcome is unsurprising given its favorable gross margin baseline.
Analyzing the trend in its profitability, Masco’s operating margin rose by 2.7 percentage points over the last five years, showing its efficiency has improved.
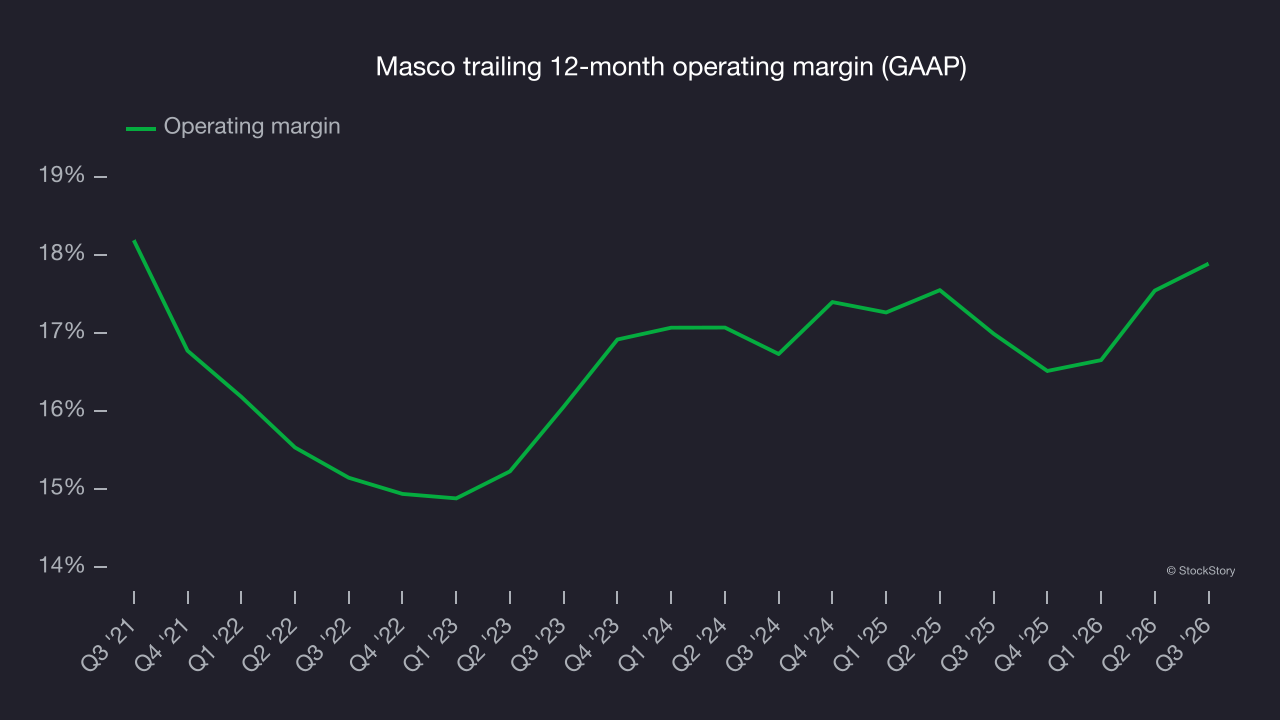
This quarter, Masco generated an operating margin of 17.2%, up 1.4 percentage points year on year. Its gross margin expanded more than its operating margin, indicating that leverage on its cost of sales was the primary driver of the recent efficiency gains.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Masco’s EPS grew at a 4.5% compounded annual growth rate over the last five years. On the positive side, this performance was better than its 1.4% annualized revenue declines and indicates that management adapted its cost structure in response to a challenging demand environment.
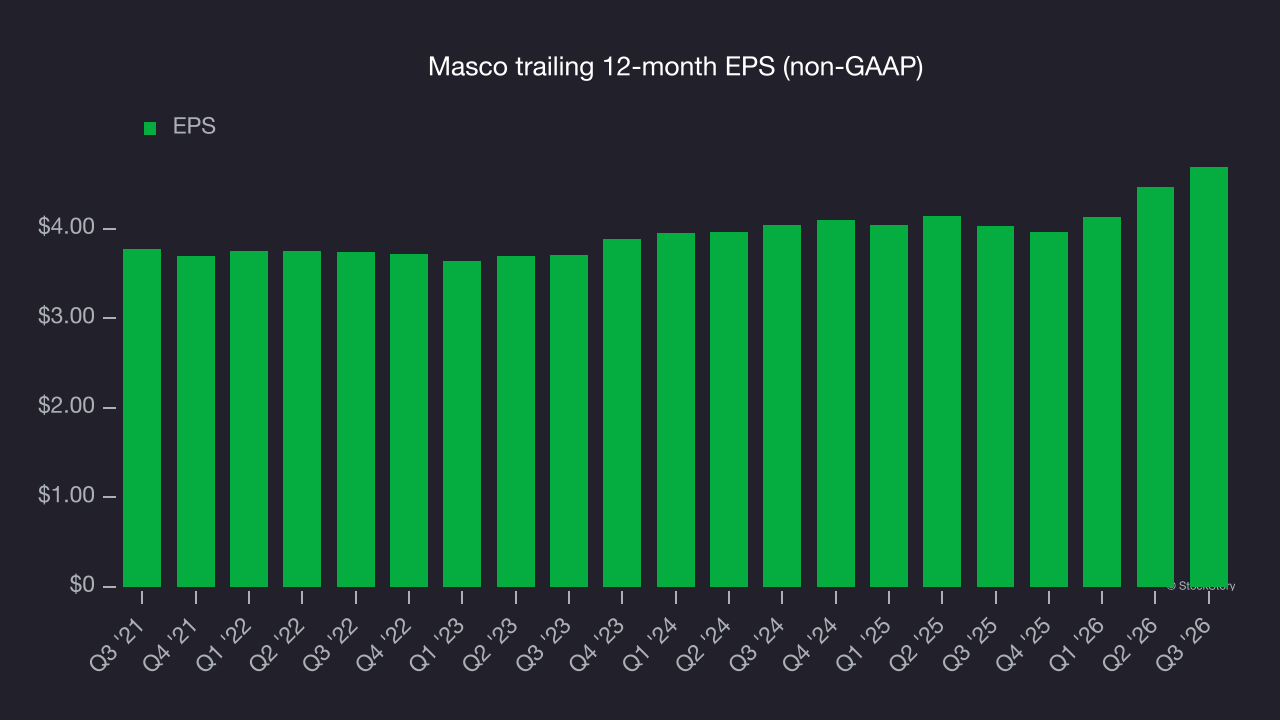
A closer look at Masco’s earnings helps explain its performance. As mentioned earlier, Masco’s operating margin expanded by 2.7 percentage points over the last five years. On top of that, its share count shrank by 20.6%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 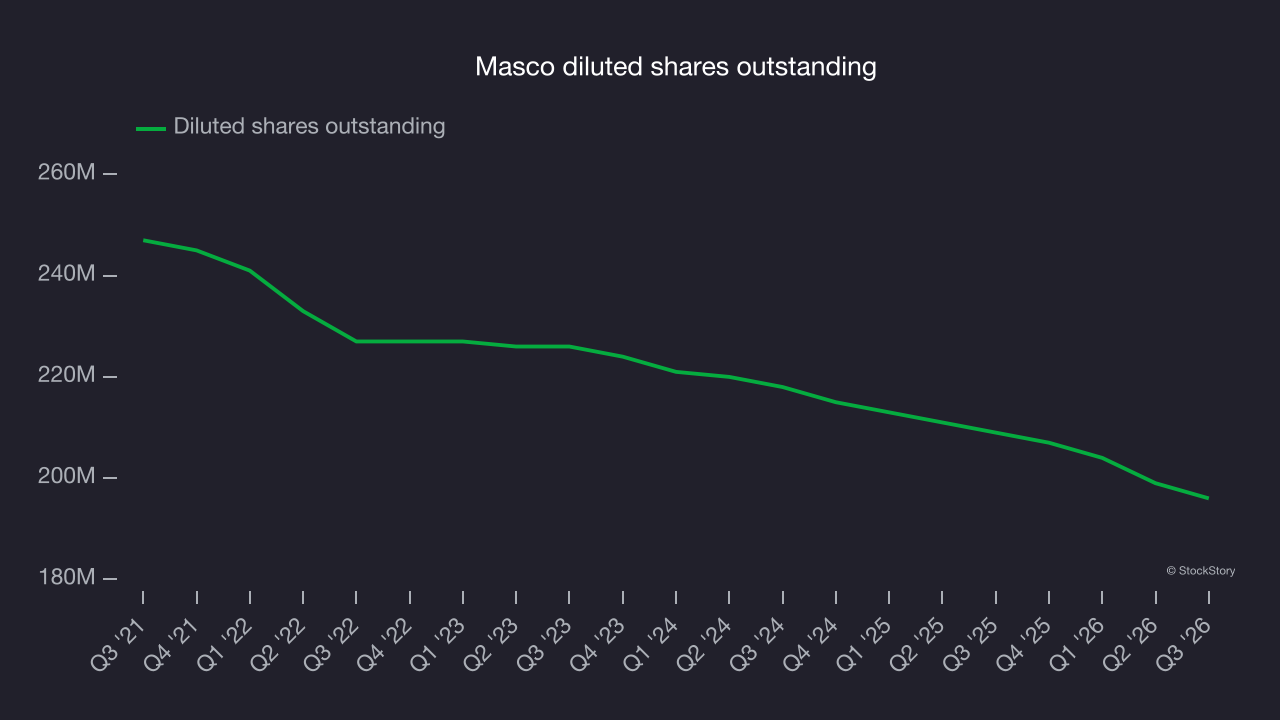
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Masco, its two-year annual EPS growth of 7.7% was higher than its five-year trend. Accelerating earnings growth is almost always an encouraging data point.
In Q3, Masco reported adjusted EPS of $1.19, up from $0.97 in the same quarter last year. This comfortably beat analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Masco’s full-year EPS to shrink by 4.5% from $4.69 to $4.48, according to S&P.
Key takeaways from Masco’s Q3 results
Masco delivered a good quarter with clear positives: organic revenue beat analysts’ consensus estimates by a wide margin, and full-year EPS guidance topped Wall Street’s consensus estimates. Shares surged 7% to $80.45 immediately after the report.
Masco reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. To assess the investment case, consider valuation, business quality and the latest earnings. For more on Masco, read our full research report here (it’s free).