Eyecare company Bausch + Lomb (NYSE: BLCO) exceeded Wall Street’s revenue expectations in Q3 2026, with revenue up 7.3% year on year to $1.38 billion. The company’s full-year revenue outlook of $5.5 billion at the midpoint was close to analysts’ consensus estimates. Its non-GAAP profit of $0.34 per share was 54.7% above analysts’ consensus estimates.
For more on Bausch + Lomb, read the full research report, available free.
Bausch + Lomb (BLCO) Q3 2026 highlights:
- Revenue $1.38 billion vs S&P analysts’ consensus estimates of $1.37 billion (7.3% year-on-year growth, in line)
- Adjusted EPS $0.34 vs S&P analysts’ consensus estimates of $0.22 (54.7% beat)
- Adjusted EBITDA $325 million vs analysts’ consensus estimates of $270.9 million (23.6% margin, 20% beat)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $5.5 billion at the midpoint from $5.49 billion
- EBITDA guidance $1.12 billion at the midpoint for the full year, above analysts’ consensus estimates of $1.05 billion
- Operating margin 11.3%, up from 7.4% in the same quarter last year
- Constant currency revenue rose 8% year on year (6% in the same quarter last year)
- Market capitalization $6.29 billion
“Our third-quarter performance reflects the strength and breadth of the business, with growth across all three segments and continued expansion in profitability,” said Thomas J. Appio, chairman and interim CEO, Bausch + Lomb. “We have delivered against the commitments outlined at Investor Day for four consecutive quarters, and I believe there are additional opportunities to improve execution, enhance profitability and create even more value over time.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Even a poor business can perform well for one or two quarters, but a high-quality one grows for years. Bausch + Lomb’s 7.9% annualized revenue growth over the last five years was decent. Its growth slightly outpaced that of the average healthcare company and shows its offerings resonate with customers.
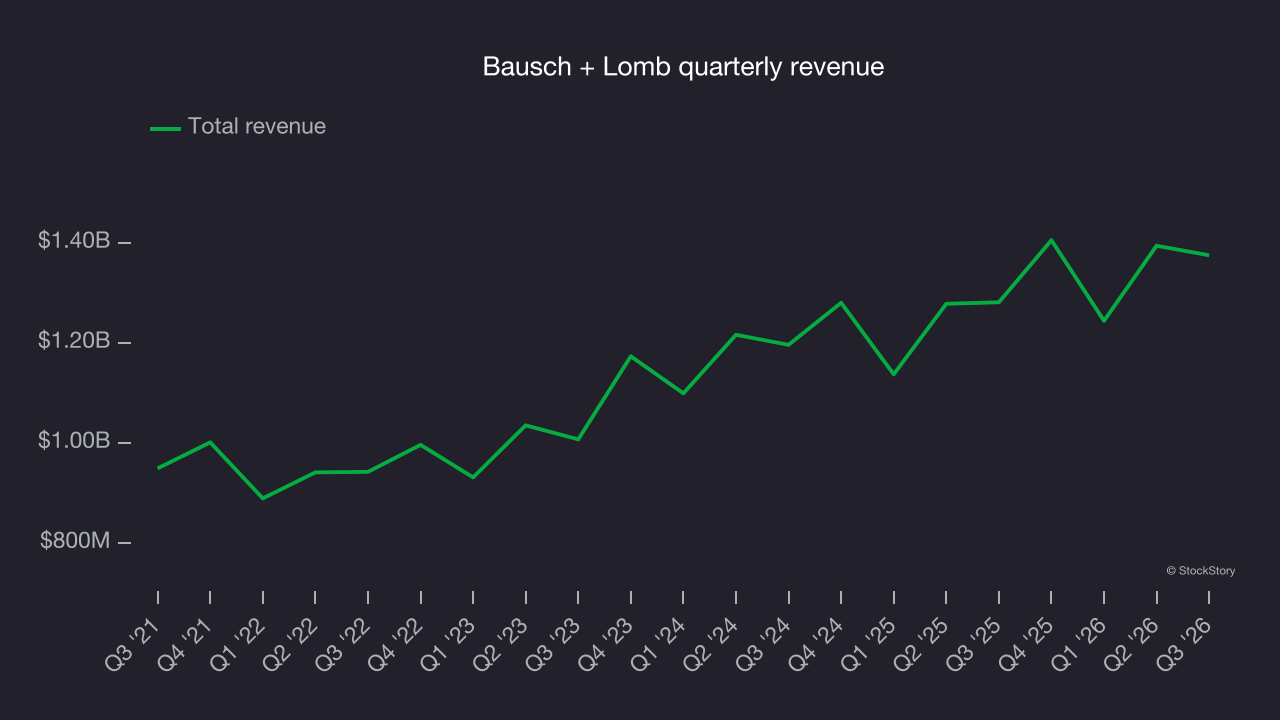
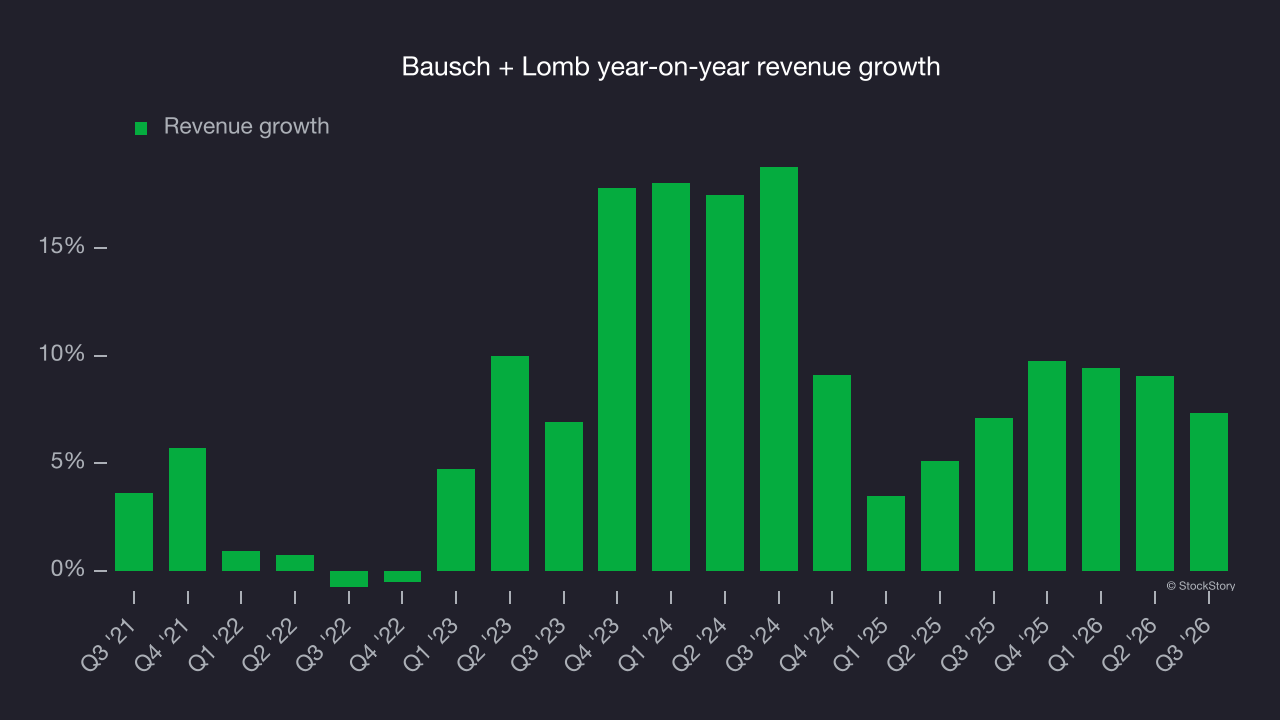
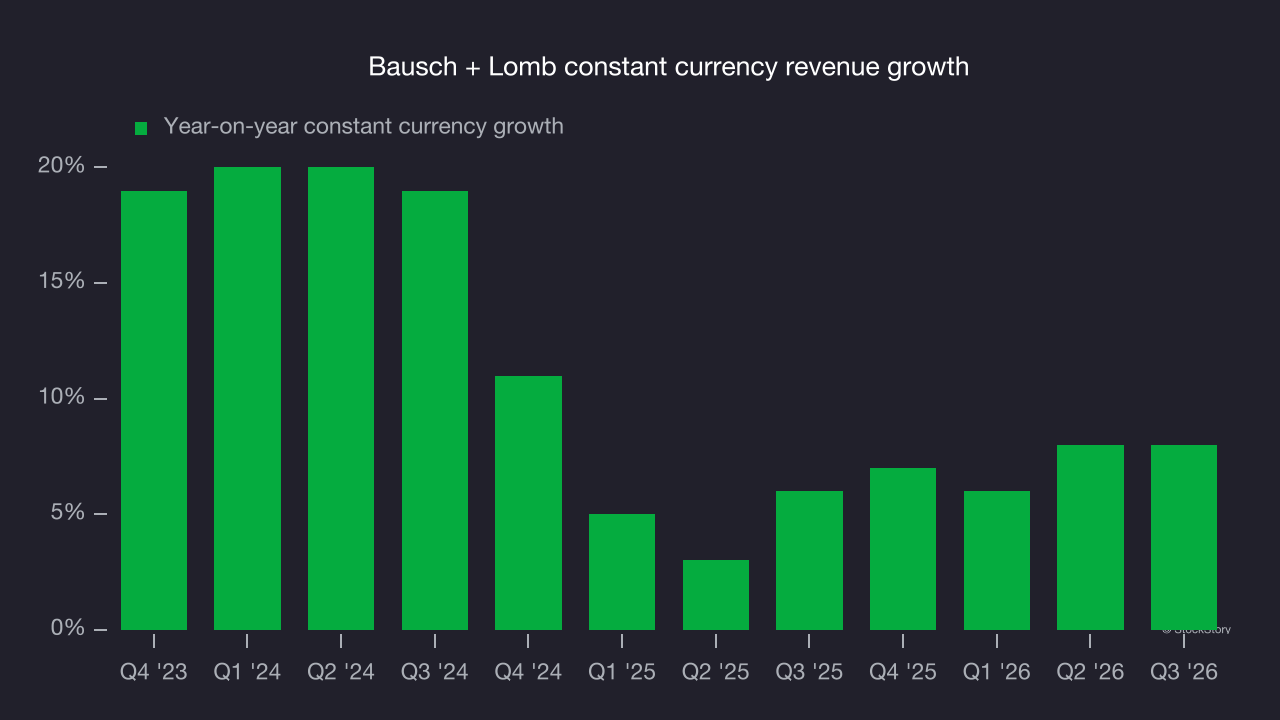
This quarter, Bausch + Lomb grew its revenue by 7.3% year on year, and its $1.38 billion of revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 5.6% over the next 12 months, according to S&P, a slight deceleration versus the last two years. Despite the slowdown, this projection is above the sector average and implies the market is forecasting some success for its newer products and services.
Adjusted operating margin
Bausch + Lomb has done a decent job managing its cost base over the last five years. The company has produced an average adjusted operating margin of 12.9%, higher than the broader healthcare sector.
Bausch + Lomb’s adjusted operating margin decreased by 2.3 percentage points over the last five years. The company’s two-year trajectory also shows it failed to restore profitability to its peak, as its margin fell by 1.6 percentage points. This was a poor performance, showing that its expenses were rising and it couldn’t pass those costs on to customers.
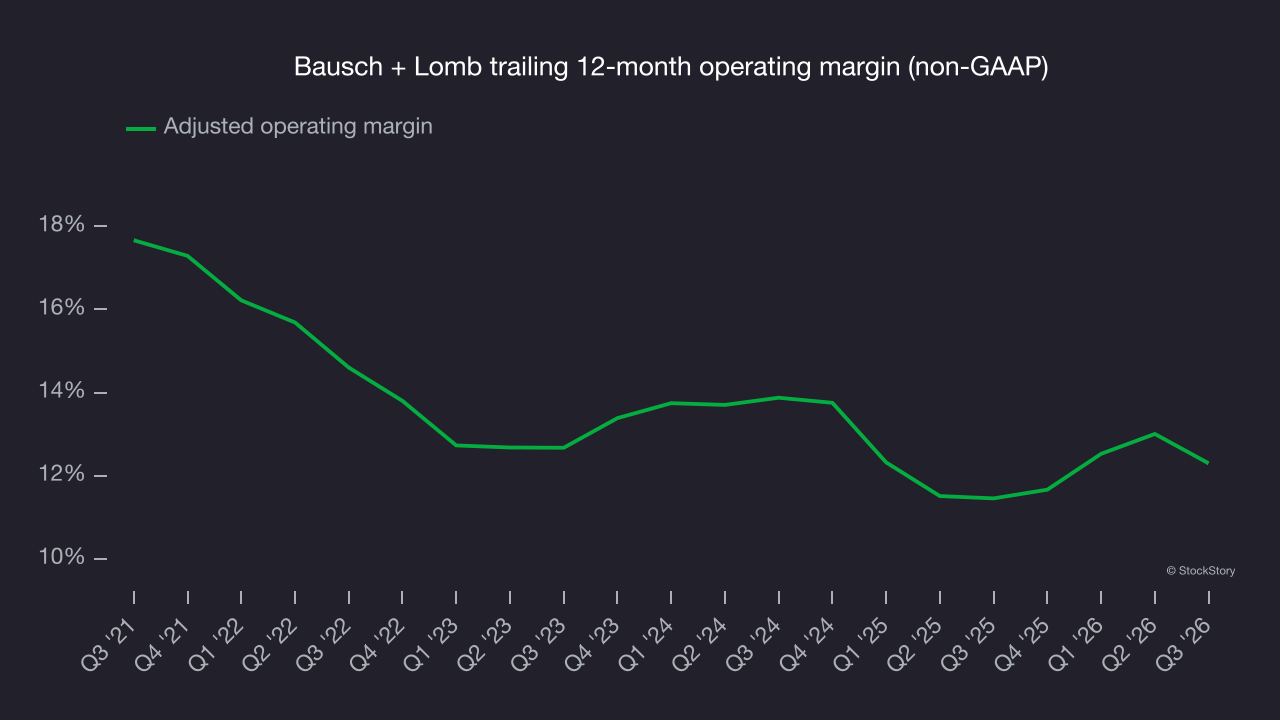
This quarter, Bausch + Lomb generated an adjusted operating margin of 11.3%, down 2.9 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Bausch + Lomb’s full-year EPS dropped 40.3%, or 8.8% annually, over the last four years. Companies with falling revenue and EPS warrant caution, as diminishing earnings could imply changing secular trends and preferences. If conditions turn unexpectedly, Bausch + Lomb’s low margin of safety could leave its stock price susceptible to large declines.
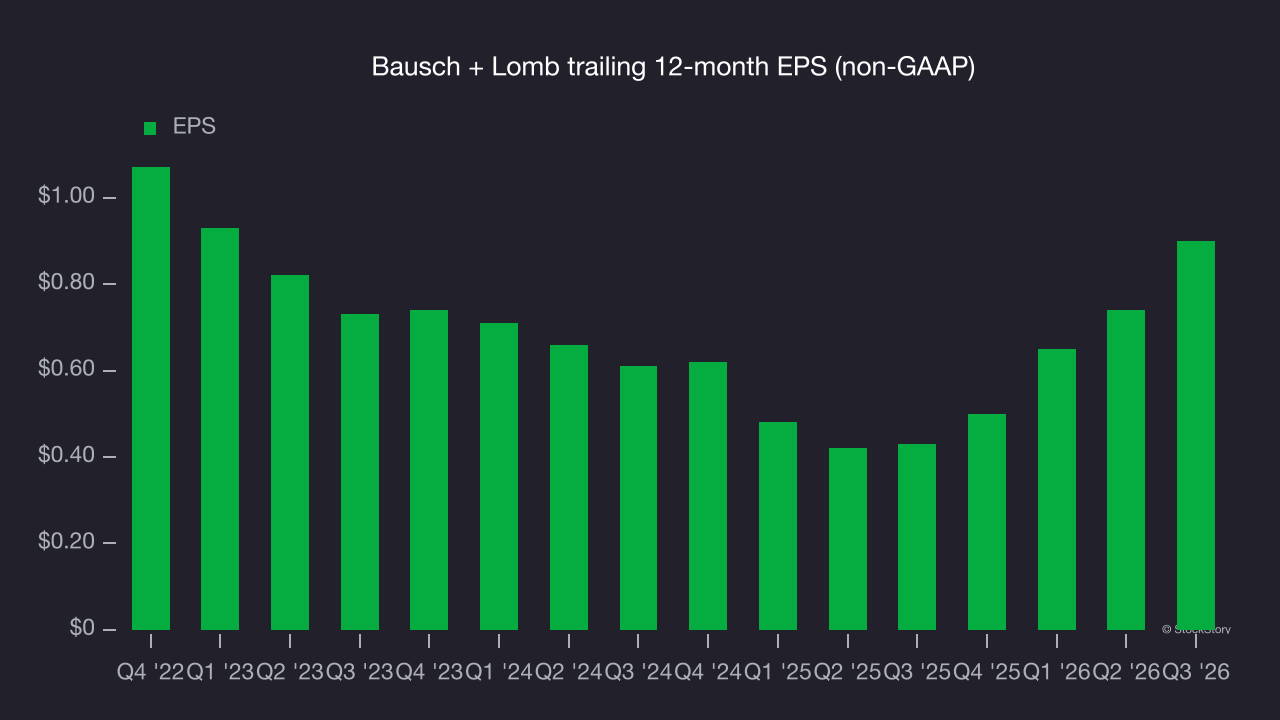
In Q3, Bausch + Lomb reported adjusted EPS of $0.34, up from $0.18 in the same quarter last year. This comfortably beat analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Bausch + Lomb’s full-year EPS to grow 21.6% from $0.90 to $1.09, according to S&P.
Key takeaways from Bausch + Lomb’s Q3 results
Bausch + Lomb delivered a solid quarter, beating analysts’ consensus EPS estimates and issuing full-year EBITDA guidance above Wall Street’s consensus. Those were key positives in the results. Shares rose 3.3% to $18.19 immediately after the release.
Bausch + Lomb had a solid quarter, but the broader picture matters when assessing the stock. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. For more on Bausch + Lomb, read the full research report here (it’s free).