U.S. Bancorp has followed the market’s trajectory closely, rising in tandem with the S&P 500 over the past six months. The stock has climbed by 6.8% to $59.79 per share while the index has gained 6.3%.
Is there a buying opportunity in U.S. Bancorp, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why is U.S. Bancorp not exciting?
We’re cautious about U.S. Bancorp. Here are three reasons why there are better opportunities than USB, plus one stock we’d rather own.
1. Net interest income points to soft demand
Our experience and research show the market cares primarily about a bank’s net interest income growth as one-time fees are considered a lower-quality and non-recurring revenue source.
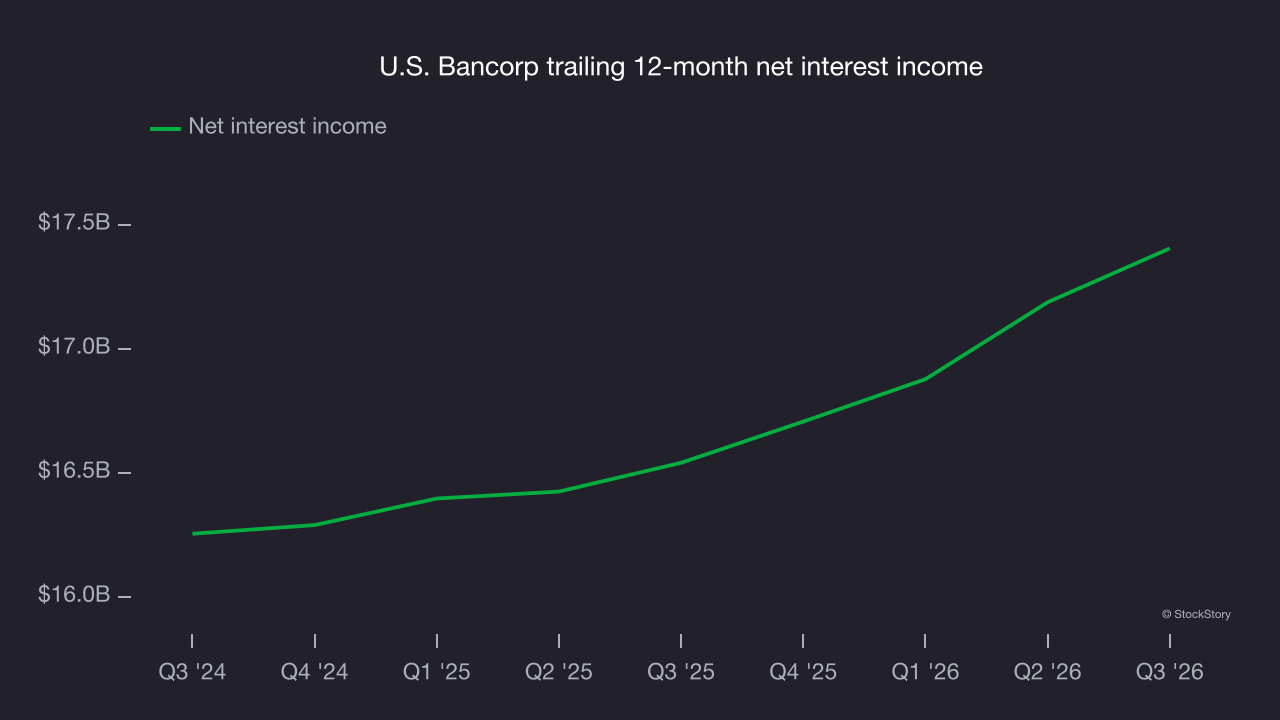
U.S. Bancorp’s net interest income has grown at a 6.8% annualized rate over the last five years, worse than the broader banking industry and in line with its total revenue. Its growth was driven by both an increase in its outstanding loans and net interest margin, which represents how much a bank earns in relation to its outstanding loan book.
2. Low net interest margin reveals weak loan book profitability
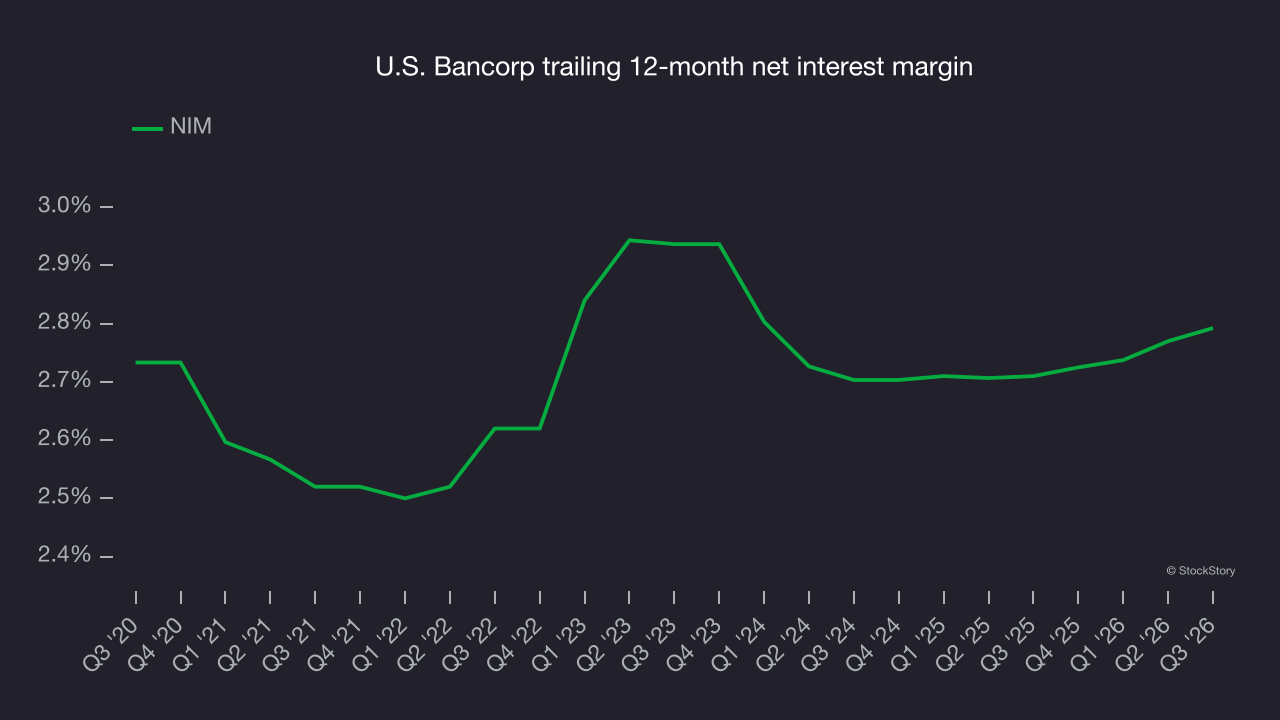
The net interest margin (NIM) is a key profitability indicator that measures the difference between what a bank earns on its loans and what it pays on its deposits. This metric measures how efficiently it can generate income from its core lending activities.
Over the past two years, we can see that U.S. Bancorp’s net interest margin averaged a weak 2.8%, indicating the company has weak loan book economics.
3. EPS growth has stalled
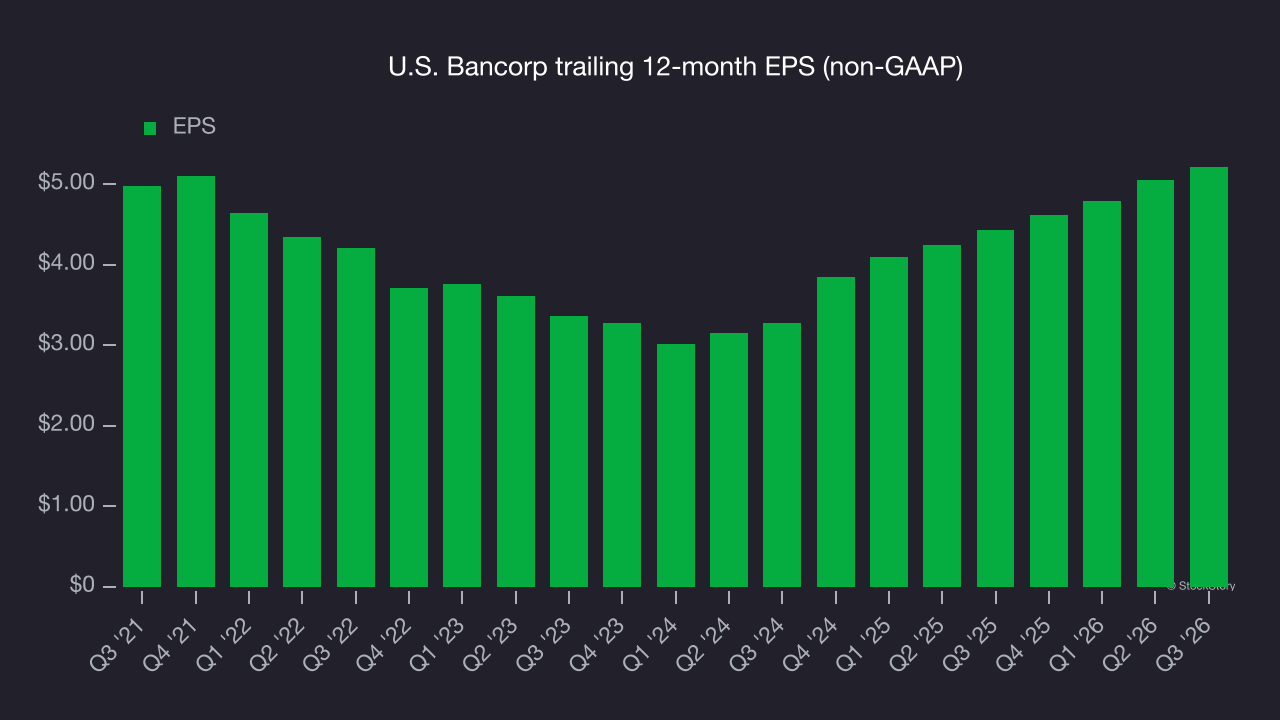
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
U.S. Bancorp’s flat EPS over the last five years was below its 6% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
Final judgment
U.S. Bancorp isn’t a terrible business, but it doesn’t pass our bar. That said, the stock currently trades at 1.5× forward P/B (or $59.79 per share). Investors with a higher risk tolerance might like the company, but we think the potential downside is too great. We’re pretty confident there are superior stocks to buy right now. We’d suggest looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks we like more than U.S. Bancorp
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.