Looking back on construction and maintenance services stocks’ Q2 earnings, we examine this quarter’s best and worst performers, including Limbach (NASDAQ: LMB) and its peers.
Construction and maintenance services companies not only boast technical know-how in specialized areas but also may hold special licenses and permits. Those who work in more regulated areas can enjoy more predictable revenue streams - for example, fire escapes need to be inspected every five years. More recently, services to address energy efficiency and labor availability are also creating incremental demand. But like the broader industrials sector, construction and maintenance services companies are at the whim of economic cycles as external factors like interest rates can greatly impact the new construction that drives incremental demand for these companies’ offerings.
The 11 construction and maintenance services stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 3.6% while next quarter’s revenue guidance was 6.2% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 14.5% since the latest earnings results.
Limbach (NASDAQ: LMB)
Established in 1901, Limbach (NASDAQ: LMB) provides integrated building systems solutions, including mechanical, electrical, and plumbing services.
Limbach reported revenues of $173.5 million, up 21.9% year on year. This print fell short of analysts’ expectations by 2.1%. Overall, it was a softer quarter for the company with full-year EBITDA guidance missing analysts’ expectations significantly and a significant miss of analysts’ EBITDA estimates.
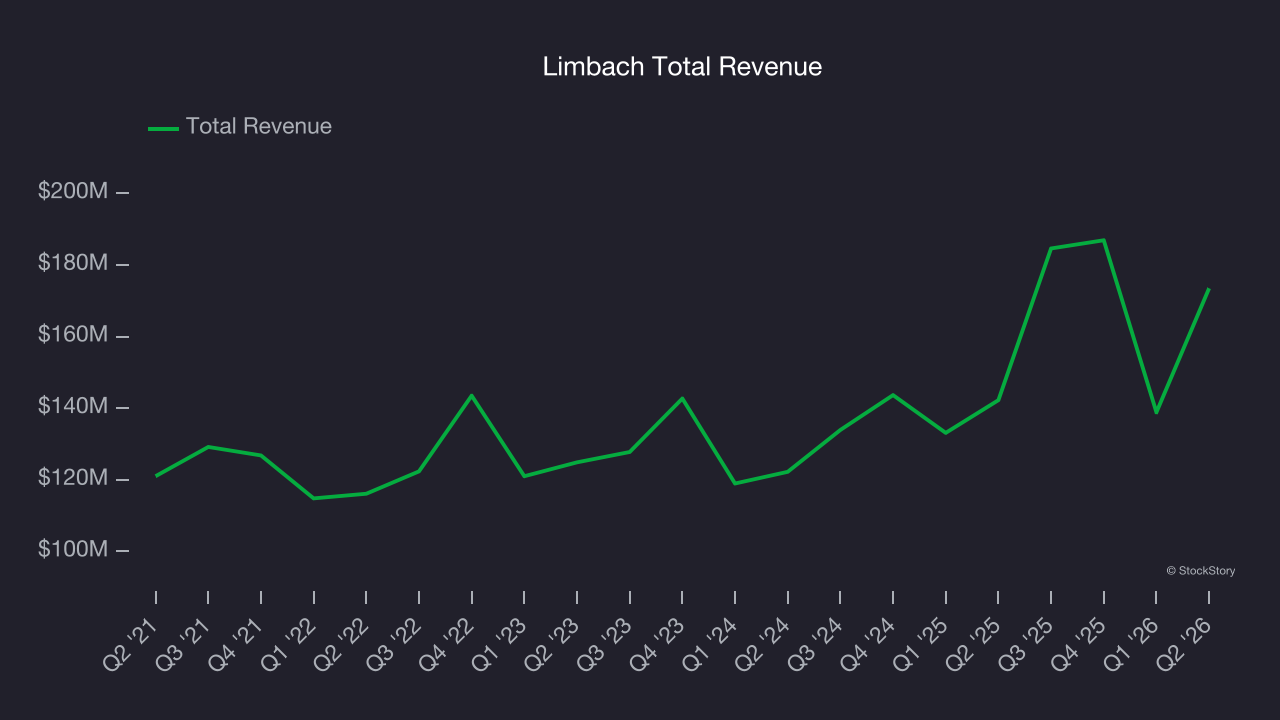
Limbach achieved the highest full-year guidance raise among its peers. Still, the market seems discontent with the results. The stock is down 38.1% since reporting and currently trades at $47.71.
Is now the time to buy Limbach? Access our full analysis of the earnings results here, it’s free.
Best Q2: Tutor Perini (NYSE: TPC)
Known for constructing the Philadelphia Eagles’ Stadium, Tutor Perini (NYSE: TPC) is a civil and building construction company offering diversified general contracting and design-build services.
Tutor Perini reported revenues of $1.64 billion, up 19.2% year on year, outperforming analysts’ expectations by 4.4%. The business had an incredible quarter with a beat of analysts’ EPS estimates and full-year EPS guidance exceeding analysts’ expectations.
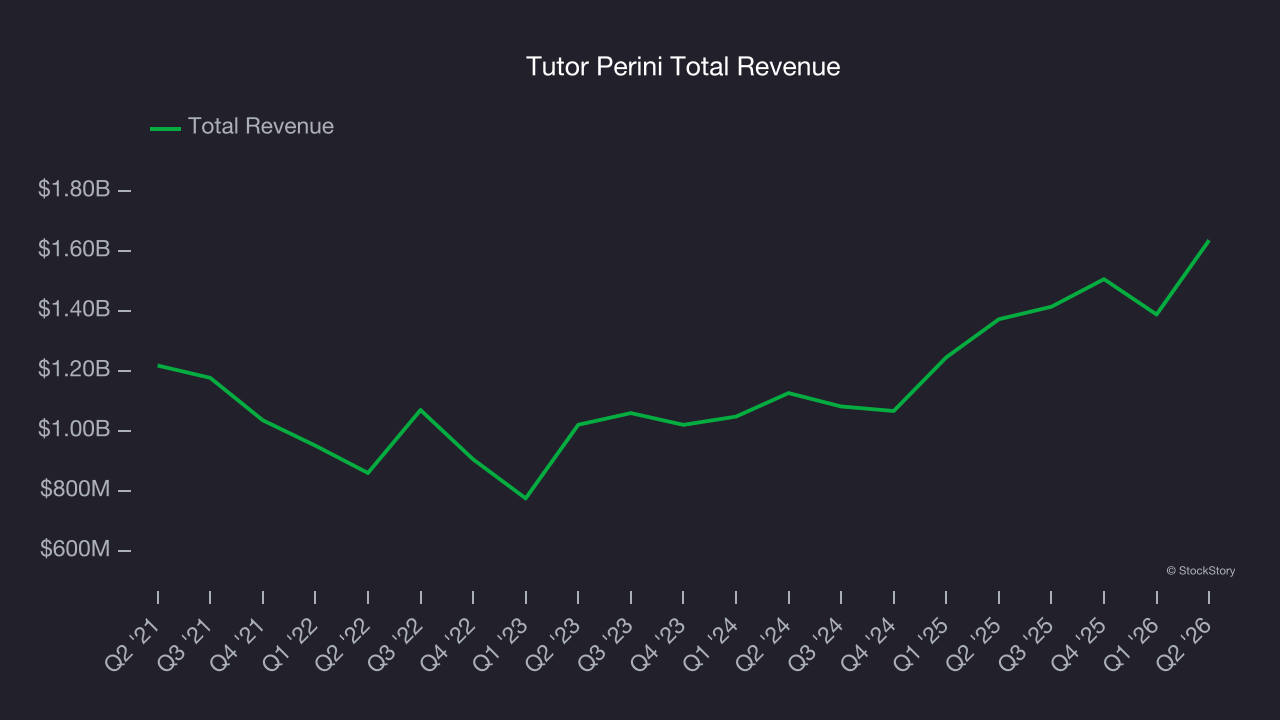
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 7% since reporting. It currently trades at $78.67.
Is now the time to buy Tutor Perini? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Matrix Service (NASDAQ: MTRX)
Founded in Oklahoma, Matrix Service (NASDAQ: MTRX) provides engineering, fabrication, construction, and maintenance services primarily to the energy and industrial markets.
Matrix Service reported revenues of $244.5 million, up 13% year on year, falling short of analysts’ expectations by 1%. It was a disappointing quarter as it posted a significant miss of analysts’ EBITDA estimates and a significant miss of analysts’ EPS estimates.
As expected, the stock is down 6.6% since the results and currently trades at $10.15.
Read our full analysis of Matrix Service’s results here.
Primoris (NYSE: PRIM)
Listed on the NASDAQ in 2008, Primoris (NYSE: PRIM) builds, maintains, and upgrades infrastructure in the utility, energy, and civil construction industries.
Primoris reported revenues of $1.69 billion, down 10.7% year on year. This number came in 3.3% below analysts’ expectations. In spite of that, it was a very strong quarter as it put up a solid beat of analysts’ EBITDA estimates and full-year EBITDA guidance exceeding analysts’ expectations.
Primoris had the weakest performance against analyst estimates and slowest revenue growth of the whole group. The stock is down 20.3% since reporting and currently trades at $72.43.
Read our full, actionable report on Primoris here, it’s free.
Construction Partners (NASDAQ: ROAD)
Founded in 2001, Construction Partners (NASDAQ: ROAD) is a civil infrastructure company that builds and maintains roads, highways, and other infrastructure projects.
Construction Partners reported revenues of $999.4 million, up 28.2% year on year. This print surpassed analysts’ expectations by 5.5%. It was a very strong quarter as it also recorded full-year EBITDA guidance beating analysts’ expectations and full-year revenue guidance slightly topping analysts’ expectations.
Construction Partners had the weakest full-year guidance update among its peers. The stock is down 16.8% since reporting and currently trades at $83.31.
Read our full, actionable report on Construction Partners here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.