Professional services firm Marsh (NYSE: MRSH) will be reporting results this Thursday morning. Here’s what to look for.
Marsh beat analysts’ revenue expectations last quarter, reporting revenues of $7.40 billion, up 6.2% year on year. It was a strong quarter for the company, with an impressive beat of analysts’ organic revenue estimates and a beat of analysts’ EPS estimates.
Is Marsh a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Marsh’s revenue to grow 4.5% year on year, slowing from the 11.5% increase it recorded in the same quarter last year.
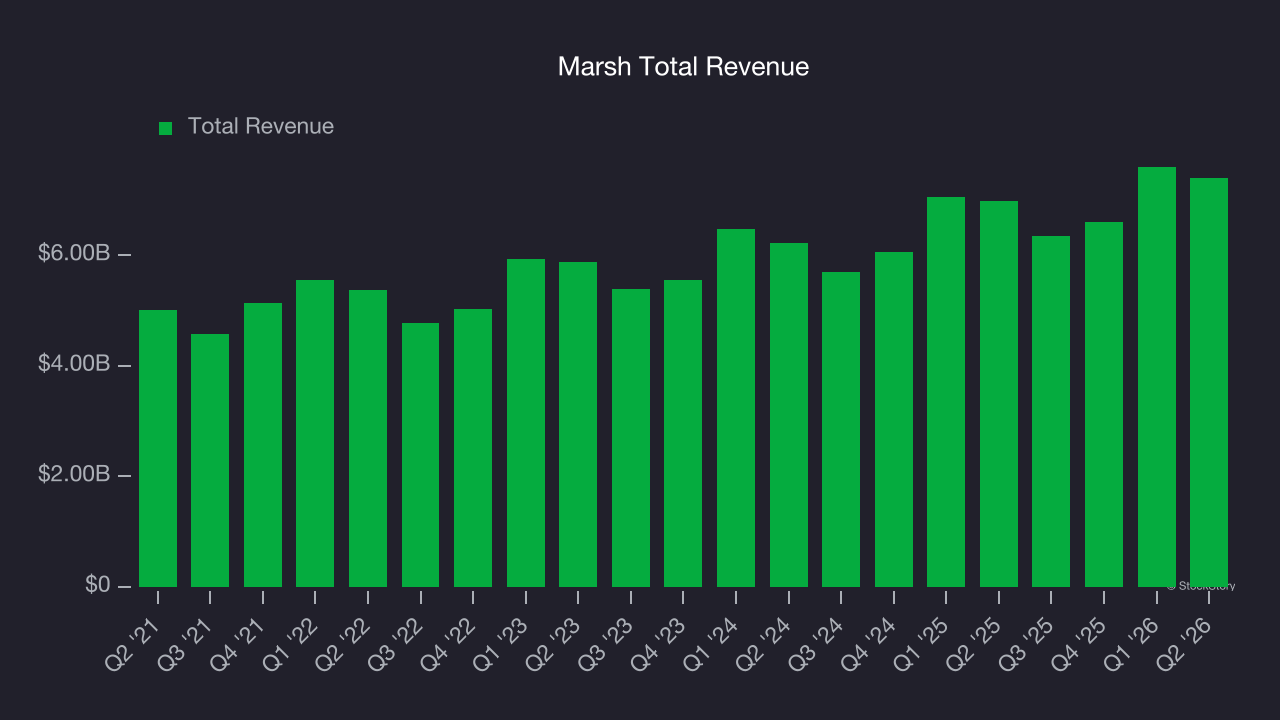
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Marsh has missed Wall Street’s revenue estimates multiple times over the last two years.
Looking at Marsh’s peers in the professional services segment, only Concentrix has reported results so far. It missed analysts’ revenue estimates, posting year-on-year sales declines of 1.2%. The stock price was unchanged following the results.
Read our full analysis of Concentrix’s earnings results here.Investors in the professional services segment have had fairly steady hands going into earnings, with share prices down 1.1% on average over the last month. Marsh is down 2% during the same time and is heading into earnings with an average analyst price target of $202.67 (compared to the current share price of $176.88).
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.