Hewlett Packard Enterprise has been on fire lately. In the past six months alone, the company’s stock price has rocketed 197%, setting a new 52-week high of $73.68 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Following the strength, is HPE a buy right now? Or is the market overestimating its value? Find out in our full research report, it’s free.
Why Is Hewlett Packard Enterprise a Good Business?
Born from the 2015 split of the iconic Silicon Valley pioneer Hewlett-Packard, Hewlett Packard Enterprise (NYSE: HPE) provides edge-to-cloud technology solutions that help businesses capture, analyze, and act upon their data across hybrid IT environments.
1. ARR Surges as Recurring Revenue Flows In
In addition to reported revenue, ARR (annual recurring revenue) is a useful data point for analyzing Hardware & Infrastructure companies. This metric shows how much Hewlett Packard Enterprise expects to collect from its existing customer base in the next 12 months, giving visibility into its future revenue streams.
Hewlett Packard Enterprise’s ARR punched in at $3.64 billion in the latest quarter, and over the last two years, its year-on-year growth averaged 48.5%. This performance was fantastic and shows that customers are willing to take multi-year bets on the company’s product offerings. Its growth also makes Hewlett Packard Enterprise a more predictable business, a tailwind for its valuation as investors typically prefer businesses with recurring revenue. 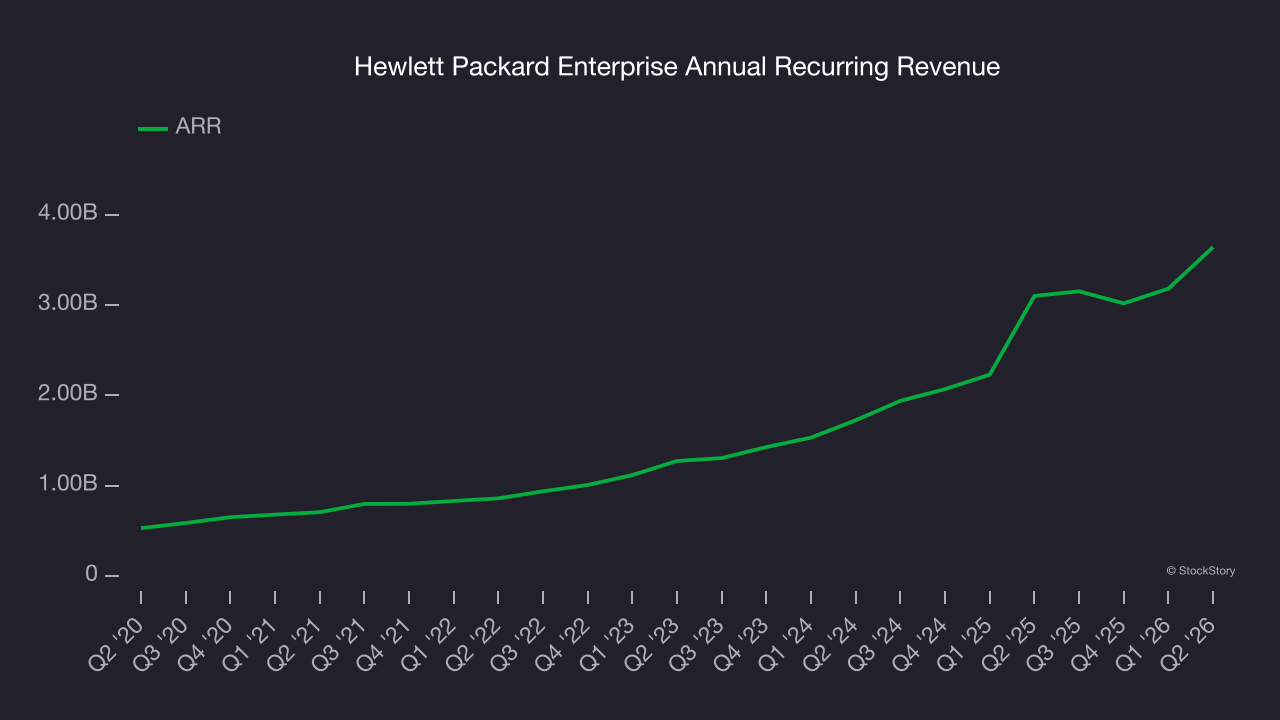
2. Economies of Scale Give It Negotiating Leverage with Suppliers
With $41.87 billion in revenue over the past 12 months, Hewlett Packard Enterprise is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices.
3. Outstanding Long-Term EPS Growth
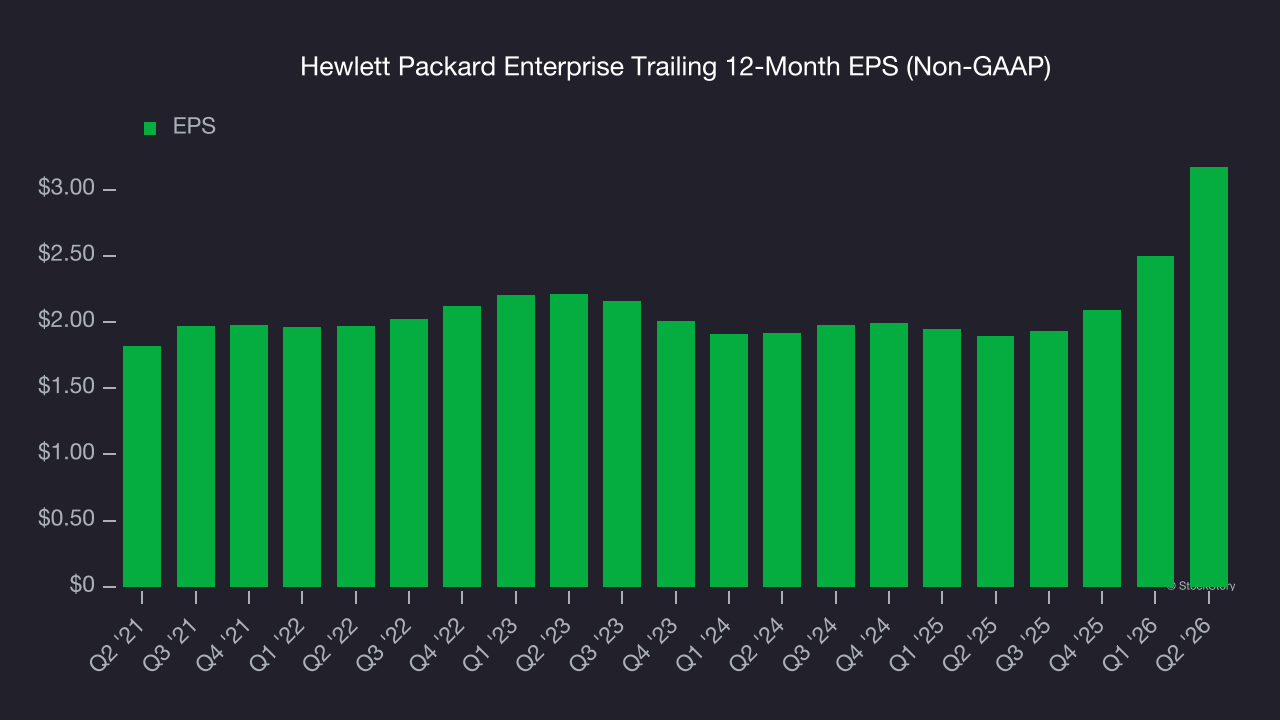
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Hewlett Packard Enterprise’s EPS grew at 11.7% compounded annual growth rate over the last five years, higher than its 8.7% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
Final Judgment
These are just a few reasons why we think Hewlett Packard Enterprise is one of the best business services companies out there, and with the recent rally, the stock trades at 15.3× forward P/E (or $73.68 per share). Is now a good time to buy despite the apparent froth? See for yourself in our full research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.