ServisFirst Bancshares trades at $41.28 and has moved in lockstep with the market. Its shares have returned 12.4% over the last six months while the S&P 500 has gained 12.9%.
Is now a good time to buy SFBS? Find out in our full research report, it’s free.
Why Is ServisFirst Bancshares a Good Business?
Founded in 2005 with a focus on serving underserved mid-sized businesses, ServisFirst Bancshares (NYSE: SFBS) is a bank holding company that provides commercial banking services to businesses and professionals through its subsidiary ServisFirst Bank.
1. Skyrocketing Revenue Shows Strong Momentum
Long-term growth is the most important, but within financials, a stretched historical view may miss recent interest rate changes and market returns. ServisFirst Bancshares’s annualized revenue growth of 19.5% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 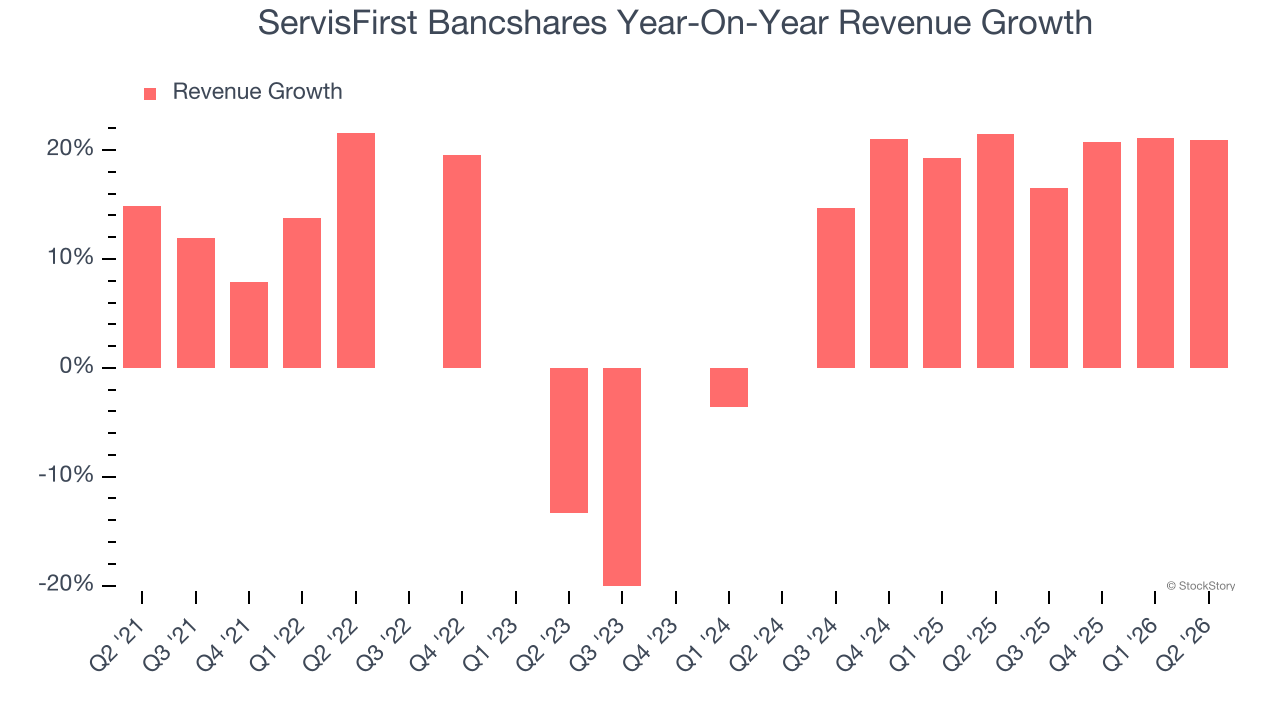 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
2. Increasing Net Interest Margin Juices Financials
Net interest margin (NIM) serves as a critical gauge of a bank’s fundamental profitability by showing the spread between interest income and interest expenses. It’s essential for understanding whether a firm can sustainably generate returns from its lending operations.
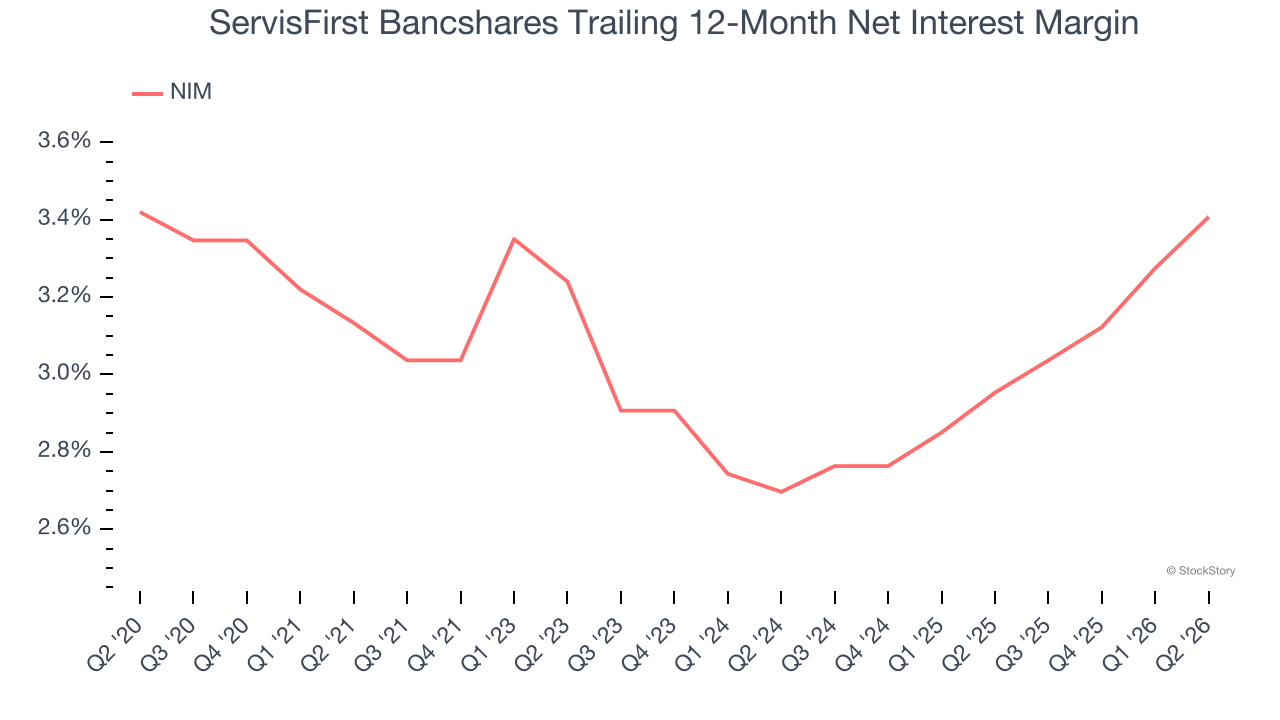
Over the past two years, ServisFirst Bancshares’s net interest margin averaged 3.2%. On the bright side, it climbed by 71.1 basis points (100 basis points = 1 percentage point) over that period.
This expansion was a tailwind for its net interest income, and while prevailing interest rates matter the most for industry net interest margins, banks that consistently increase this figure generally boast higher-earning loan books (all else equal such as the risk of those loans) or provide differentiated services that give them the ability to charge higher rates (pricing power).
3. EPS Moving Up Steadily
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
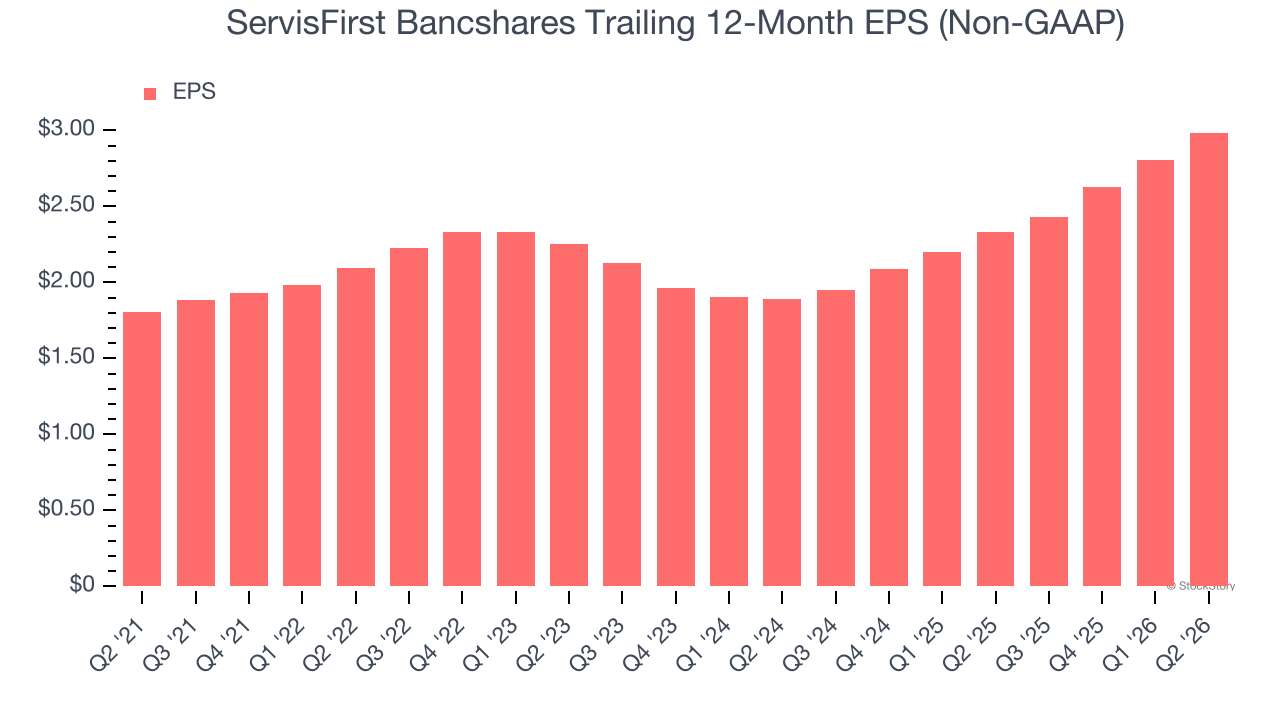
ServisFirst Bancshares’s decent 10.6% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
Final Judgment
These are just a few reasons ServisFirst Bancshares is a high-quality business worth owning. At $41.28 per share (or 2.2× forward P/B), is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.