Insurance holding company Kemper (NYSE: KMPR) met Wall Street’s revenue expectations in Q3 2026, but revenue fell by 12.1% year on year to $1.09 billion. Its non-GAAP profit of $1.01 per share was 30.2% above analysts’ consensus estimates.
For more on Kemper, read our free full research report.
Kemper (KMPR) Q3 2026 highlights:
- Net premiums earned $983.4 million vs analysts' consensus estimates of $988.3 million (13.2% year-on-year decline, in line)
- Revenue $1.09 billion vs analysts' consensus estimates of $1.09 billion, according to S&P (12.1% year-on-year decline, in line)
- Combined ratio 99.2% vs analysts' consensus estimates of 101% (225 basis point beat)
- Adjusted EPS $1.01 vs analysts' consensus estimates of $0.78, according to S&P (30.2% beat)
- Book value per share $36.20 vs analysts' consensus estimates of $40.88 (20.2% year-on-year decline, 11.4% miss)
- Market capitalization $1.97 billion
“Our third-quarter results demonstrate continued progress as the actions we’ve taken to improve profitability are taking hold,” said Stephen J. McAnena, President and Chief Executive Officer. “While there is more work ahead, we are moving in the right direction and remain focused on restoring profitability and building capabilities to position Kemper for durable, profitable growth.”
Revenue growth
Insurance companies generate revenue three ways. The first is the core insurance business itself, represented in the income statement as premiums earned. The second source is investment income from investing the “float” (premiums collected but not yet paid out as claims) in assets such as fixed-income assets and equities. The third is fees from policy administration, annuities and other value-added services. Kemper’s demand was weak over the last five years as its revenue fell at a 4.1% annual rate. That decline suggests poor business quality.
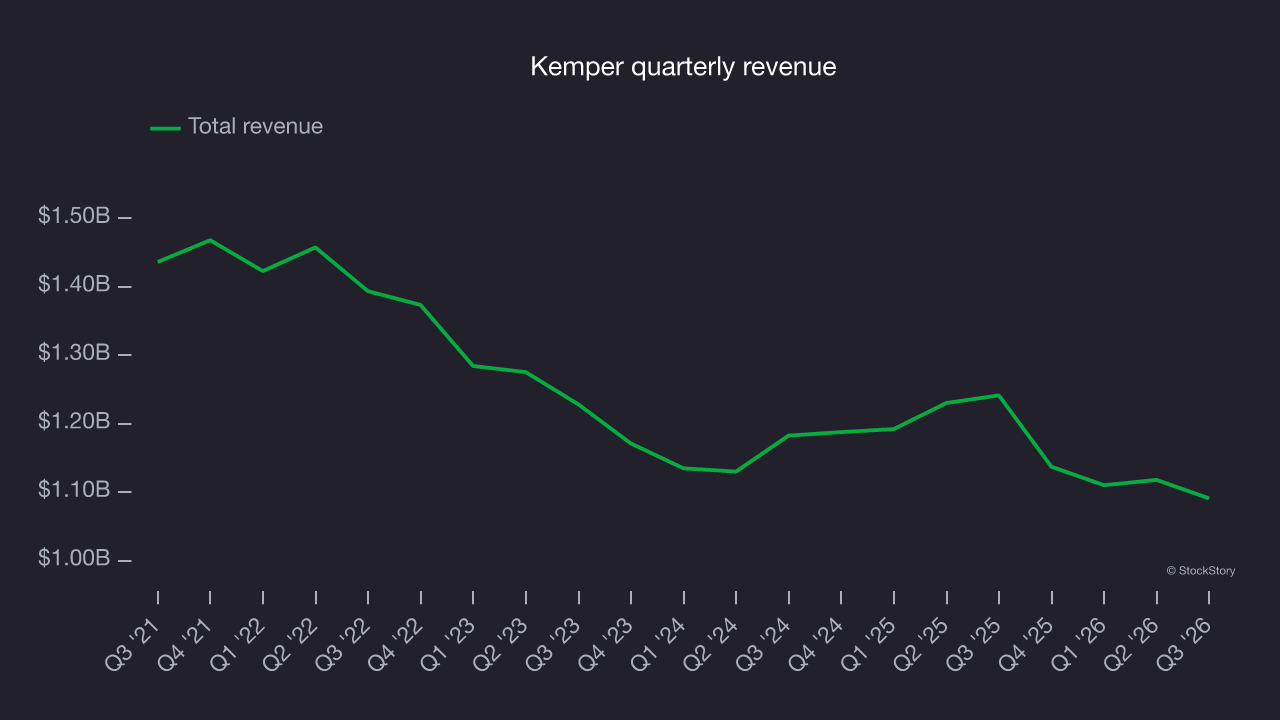
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Kemper’s annualized revenue declines of 1.8% over the last two years suggest its demand continued shrinking. 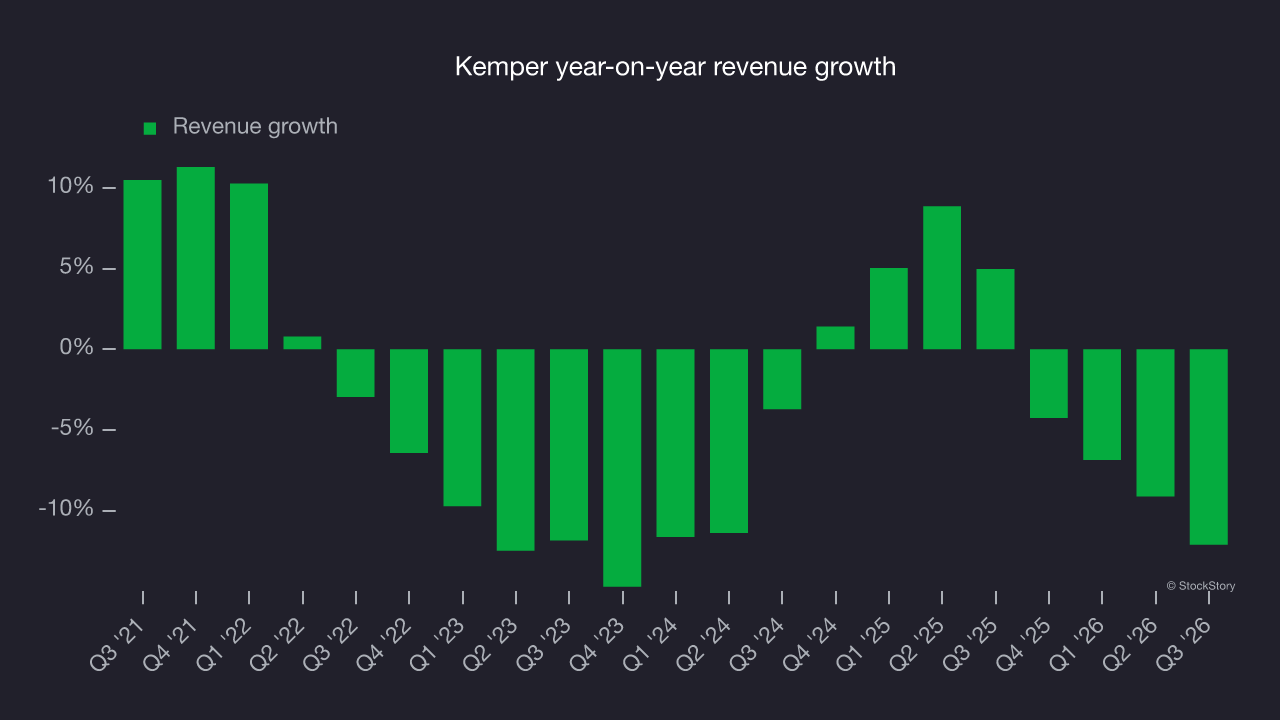
This quarter, Kemper reported an uninspiring 12.1% year-on-year revenue decline to $1.09 billion, in line with Wall Street’s consensus estimates.
Net premiums earned made up 91.5% of the company’s total revenue during the last five years, meaning Kemper depends heavily on its underwriting activities because non-insurance operations contribute little.
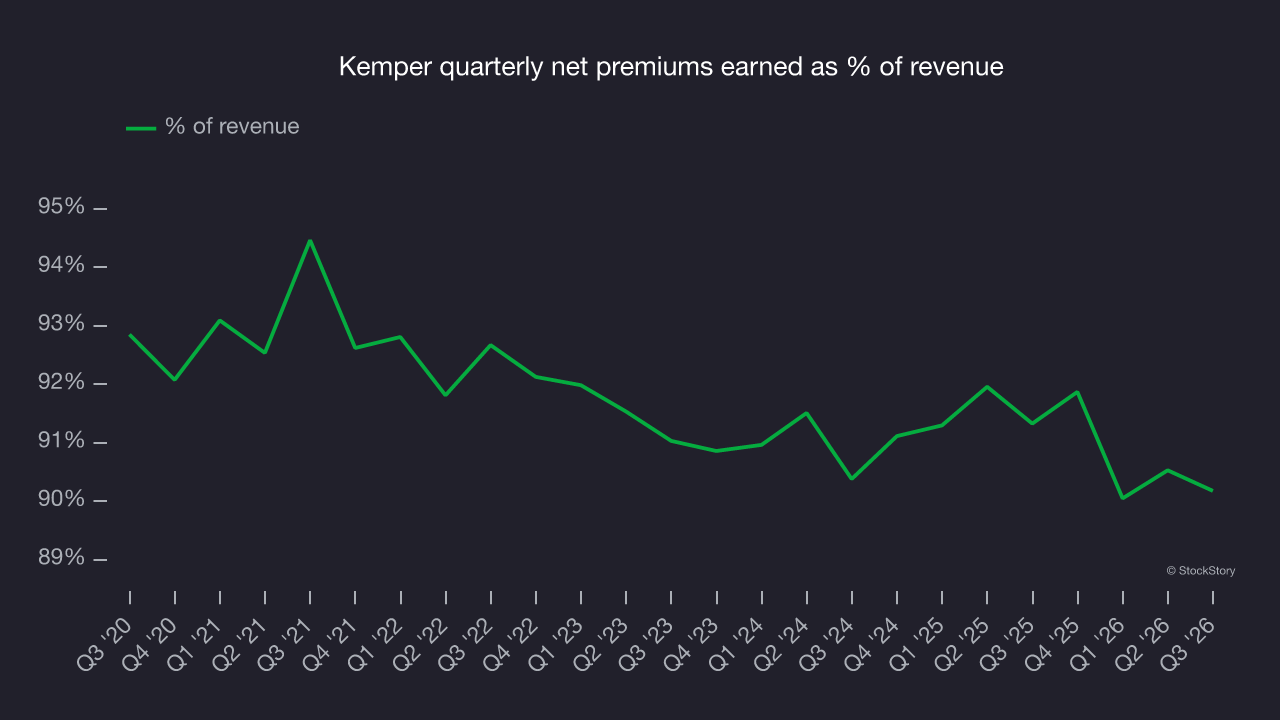
The market cares primarily about an insurer’s net premiums earned growth, as investment and fee income are considered more susceptible to market volatility and economic cycles.
Book value per share (BVPS)
Insurance companies are balance sheet businesses, collecting premiums upfront and paying out claims over time. The float (premiums collected but not yet paid out) is invested, creating an asset base supported by a liability structure. Book value per share, or BVPS, captures this dynamic by measuring these assets (investment portfolio, cash and reinsurance recoverables) less liabilities (claim reserves, debt and future policy benefits). BVPS is essentially the residual value for shareholders.
BVPS is therefore a key metric to track for insurers and sheds light on business quality because it reflects long-term capital growth and is harder to manipulate than more commonly used metrics like earnings per share.
Kemper’s BVPS declined at an 11.1% annual rate over the last five years. On a two-year basis, BVPS fell at a slower pace, dropping by 8.6% annually from $43.30 to $36.20 per share.
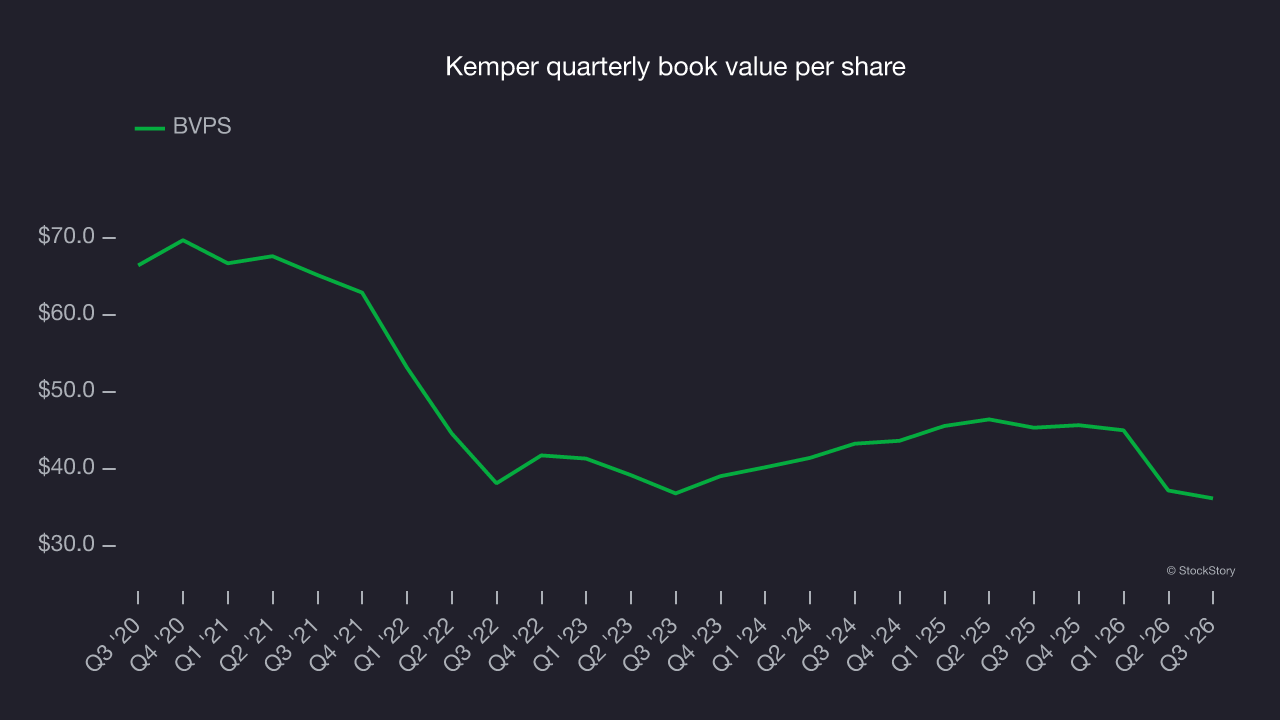
Over the next 12 months, consensus estimates call for Kemper’s BVPS to grow by 18% to $40.88, a strong growth rate.
Key takeaways from Kemper’s Q3 results
Kemper’s Q3 results were mixed: EPS beat analysts’ consensus estimates, but book value per share fell short of expectations. Net premiums earned came in line with Wall Street’s consensus estimates. Shares remained flat at $33.17 immediately after the release.
The latest quarter is only one part of Kemper’s longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here (it’s free).