Fashion brand Ralph Lauren (NYSE: RL) beat Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q2 2027), with revenue rising 9.1% year on year to $2.19 billion. Its non-GAAP profit of $4.64 per share was 9% above analysts’ consensus estimates.
For more on Ralph Lauren, read our free full research report.
Ralph Lauren (RL) Q3 CY2026 highlights:
- Revenue $2.19 billion vs S&P analysts’ consensus estimates of $2.12 billion (9.1% year-on-year growth, 3.3% beat)
- Adjusted EPS $4.64 vs S&P analysts’ consensus estimates of $4.26 (9% beat)
- Raised full-year guidance for constant currency revenue growth (due to this quarter's beat) and operating margin expansion (due to higher gross margins)
- Operating margin 16.6%, up from 12.2% in the same quarter last year
- Free cash flow $218.1 million, up from -$40.6 million in the same quarter last year
- Constant currency revenue rose 9.6% year on year (14% in the same quarter last year)
- Market capitalization $24.55 billion
"We delivered strong second quarter performance, enabling us to raise our Fiscal 2027 outlook once again," said Patrice Louvet, President and Chief Executive Officer. "Through a dynamic global operating environment, we continue to invest in the strategic priorities that are bringing our Next Great Chapter: Drive plan to life — strengthening our brand desirability and delighting multi-generational customers in every geography around the world to drive sustainable long-term growth and value creation. We remain confident in the strength of our brand, our teams and our diversified engines of growth through this fiscal year and beyond."
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Ralph Lauren’s revenue grew at a weak 8.8% annualized rate over the last five years, falling short of the consumer discretionary sector benchmark.
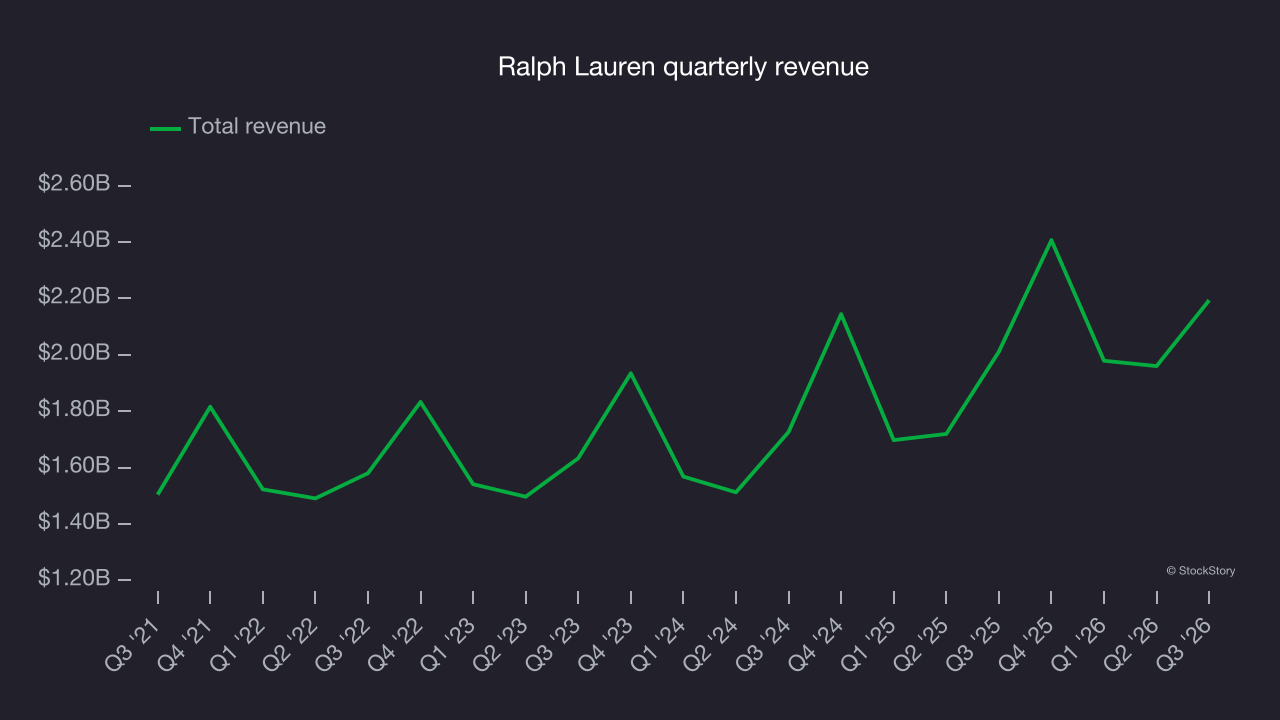
Long-term growth matters the most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. Ralph Lauren’s annualized revenue growth of 12.5% over the last two years is above its five-year trend, a positive sign.
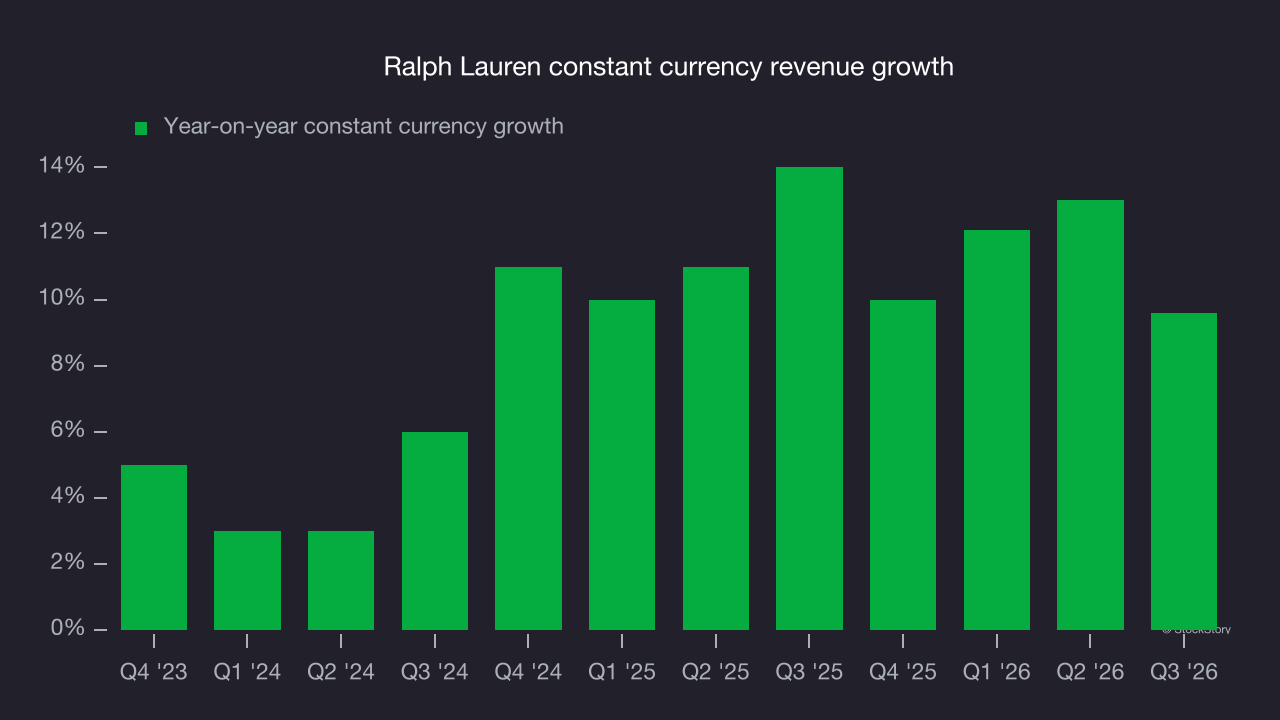
Constant currency revenue helps explain the company’s revenue dynamics by excluding currency movements that are outside its control and not indicative of demand. Over the last two years, its constant currency revenue averaged 11.3% year-on-year growth. This was in line with reported revenue growth, indicating that foreign exchange has not had a meaningful impact on revenue.
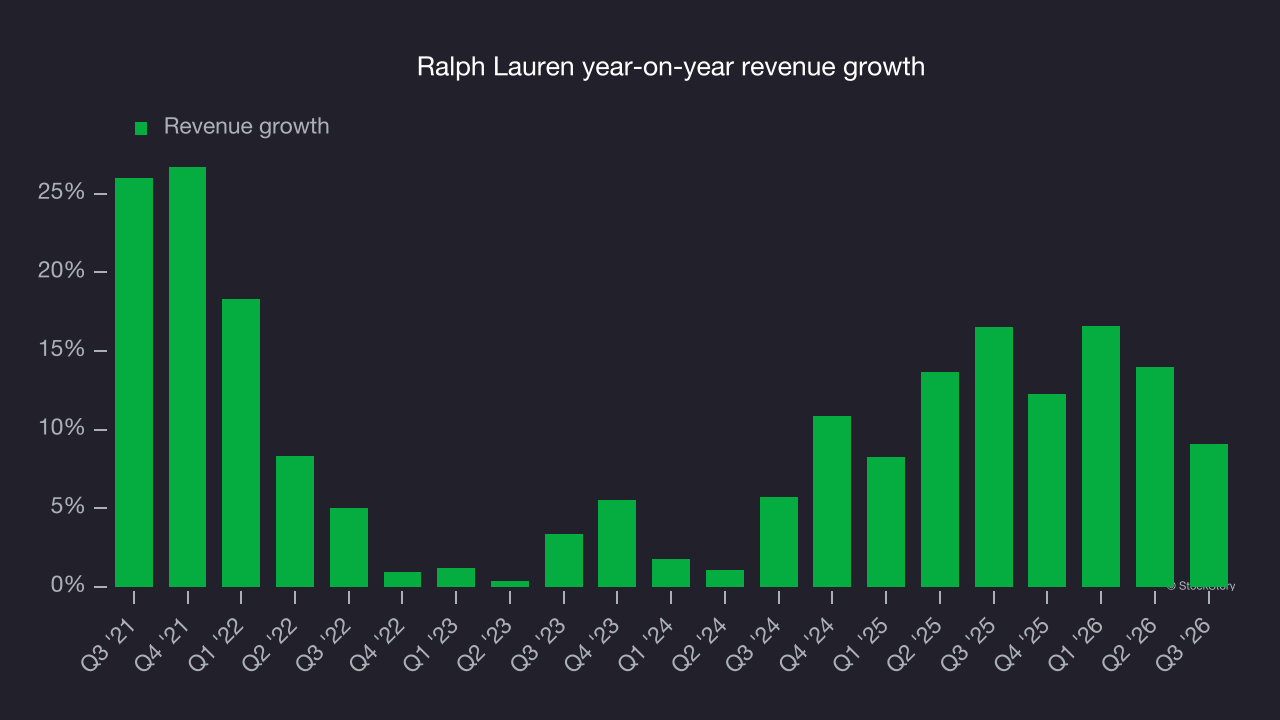
This quarter, Ralph Lauren reported year-on-year revenue growth of 9.1%, and its $2.19 billion of revenue exceeded Wall Street’s consensus estimates by 3.3%.
Looking ahead, sell-side analysts expect revenue to grow 4.6% over the next 12 months, according to S&P, a deceleration versus the last two years. That uninspiring outlook implies its products and services will face some demand headwinds.
Operating margin
Ralph Lauren’s operating margin has been trending up over the last 12 months and averaged 15.7% over the last two years. The company’s improved efficiency is a positive, but its suboptimal cost structure means profitability remains inadequate for a consumer discretionary business.
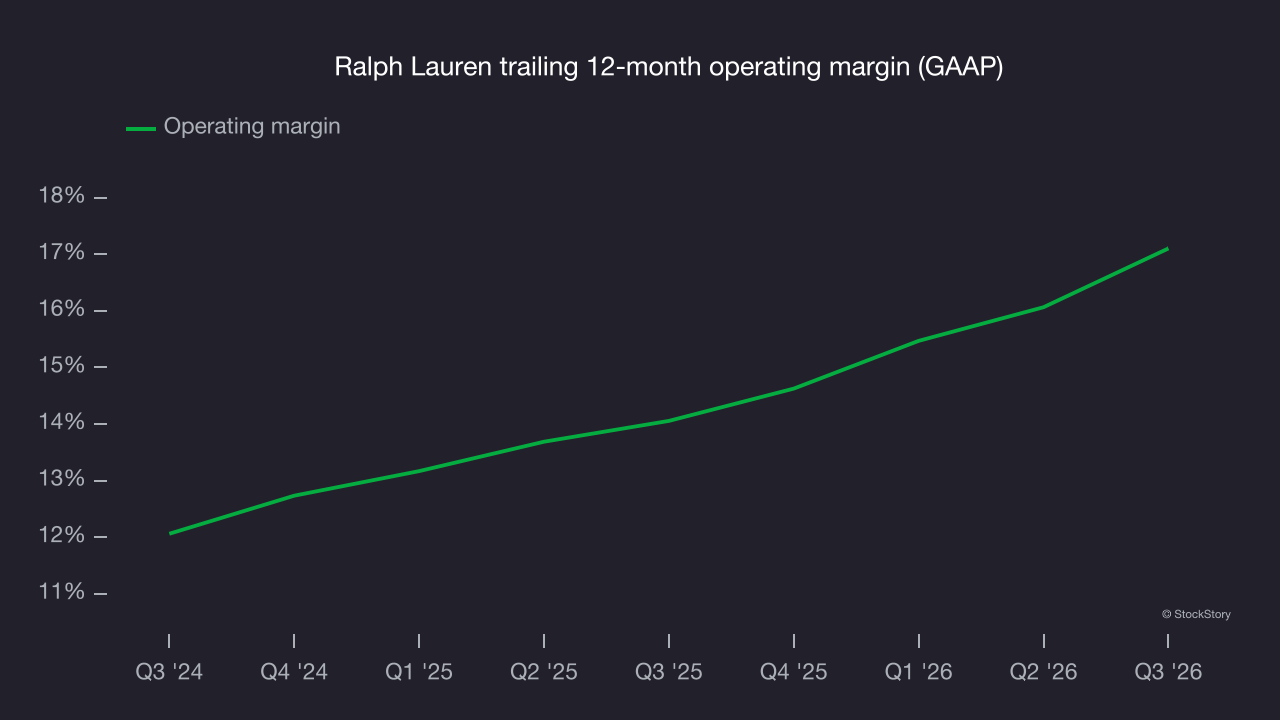
This quarter, Ralph Lauren generated an operating margin of 16.6%, up 4.4 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Ralph Lauren’s EPS grew at a 21.3% compounded annual growth rate over the last five years. This performance was better than its revenue growth but doesn’t tell us much about its business quality because its operating margin improvement was smaller than its peers’.
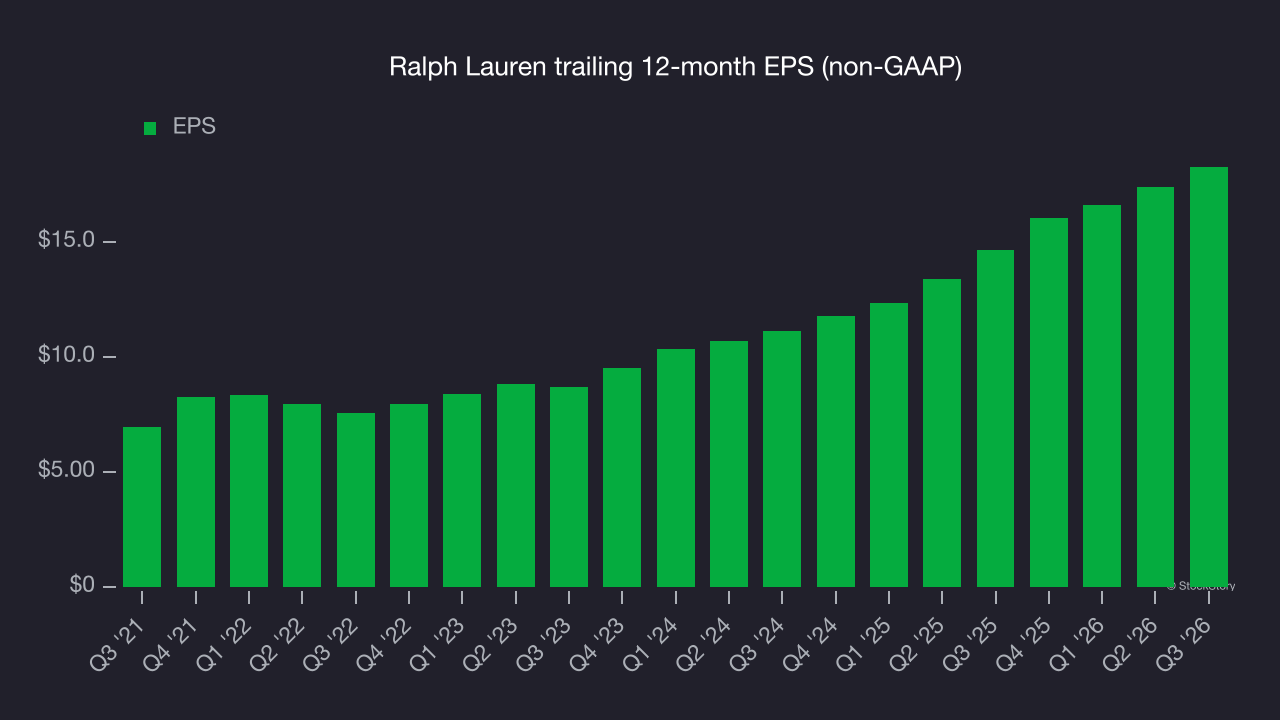
In Q3, Ralph Lauren reported adjusted EPS of $4.64, up from $3.79 in the same quarter last year. This result beat analysts’ consensus estimates by 9%. Over the next 12 months, Wall Street expects Ralph Lauren’s full-year EPS to grow 10.2% from $18.25 to $20.11, according to S&P.
Key takeaways from Ralph Lauren’s Q3 results
Revenue and EPS both topped Wall Street’s consensus estimates, giving Ralph Lauren a decent Q3. Full-year guidance was also raised for constant currency revenue growth and operating margin expansion. Investors were likely hoping for more, as shares tumbled 5.5% to $390.00 immediately after the results were released.
The latest quarter matters when deciding whether to invest in Ralph Lauren at its current price, but longer-term fundamentals and valuation matter much more. Read the full research report here (it’s free).