Technology real estate company Opendoor (NASDAQ: OPEN) missed Wall Street’s revenue expectations in Q3 2026, but revenue rose 11.7% year on year to $1.02 billion. Next quarter’s revenue guidance of $1.03 billion underwhelmed, coming in 6.8% below analysts’ consensus estimates. Its GAAP loss of $0.23 per share was 39.3% below analysts’ consensus estimates.
For more on Opendoor, read our free full research report.
Opendoor (OPEN) Q3 2026 highlights:
- Revenue $1.02 billion vs S&P analysts’ consensus estimates of $1.07 billion (11.7% year-on-year growth, 4.5% miss)
- EPS (GAAP) -$0.23 vs analysts’ consensus estimates of -$0.17 (39.3% miss)
- Adjusted EBITDA -$31 million (-3% margin, 6.1% year-on-year growth)
- Revenue guidance $1.03 billion for Q4 2026, below analysts’ consensus estimates of $1.11 billion
- EBITDA guidance $77.5 million at the midpoint for Q4 2026, above analysts’ consensus estimates of -$16.66 million
- Operating margin -18.3%, down from -7.4% in the same quarter last year
- Free cash flow -$836 million, down from $432 million in the same quarter last year
- Homes sold rose by 160 year on year
- Market capitalization $1.92 billion
“We’re earning more sellers’ business. Broader product choices, less friction and better customer education give homeowners more reasons to choose Opendoor. We’re seeing dramatically higher true seller conversion at comparable spreads than we have in years. We more than quadrupled homes purchased year-over-year, and Cash Now, More Later, which requires less capital upfront per home, accounted for more acquisitions than all products combined in Q3 2025.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years. Opendoor’s demand was weak over the last five years as its revenue fell at a 5.4% annual rate, falling below our standards and pointing to poor business quality.
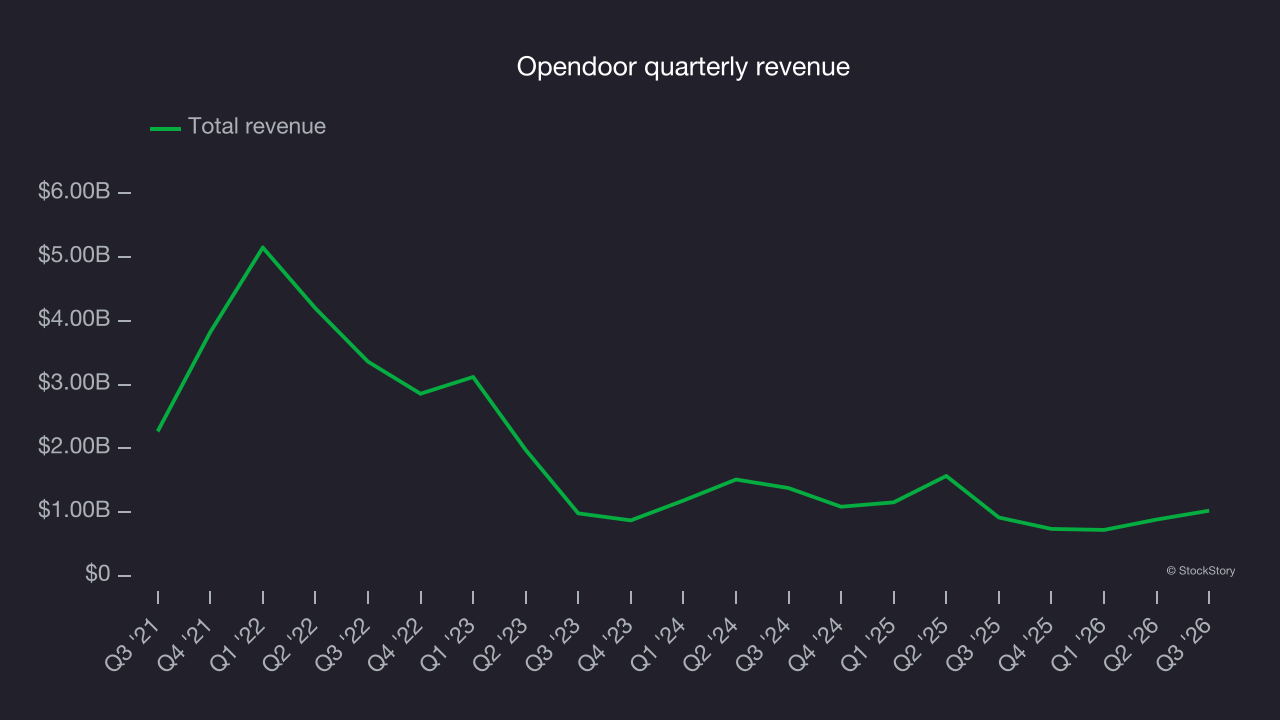
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. Opendoor’s recent performance shows its demand remained suppressed as its revenue has declined by 17.5% annually over the last two years.
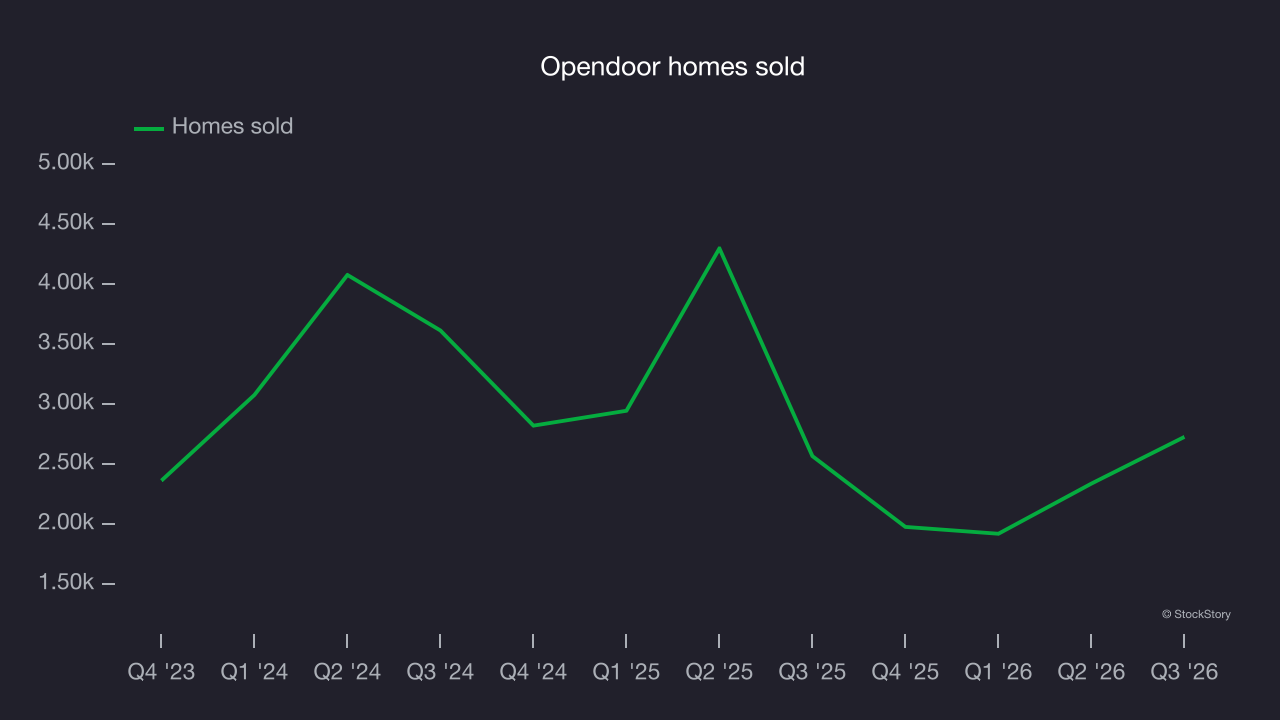
The number of homes sold offers more detail on the company’s revenue dynamics and reached 2,728 in the latest quarter. Over the last two years, Opendoor’s homes sold averaged 14.1% year-on-year declines. Growth in homes sold outpaced revenue growth during the same period, indicating that the company’s monetization has fallen.
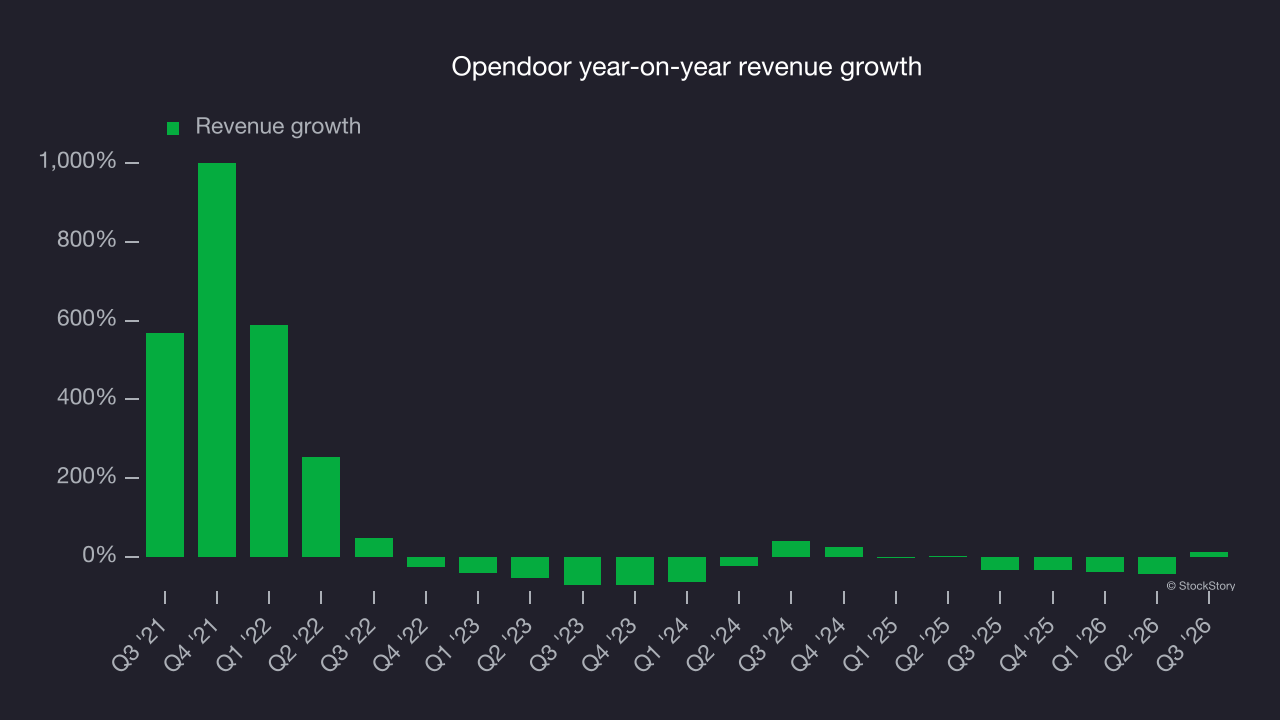
This quarter, Opendoor’s revenue grew by 11.7% year on year to $1.02 billion but fell short of Wall Street’s consensus estimates. Management is guiding for a 40% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 89.6% over the next 12 months, according to S&P, an improvement versus the last two years. This substantial projected increase suggests its newer products and services will fuel better top-line performance.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Opendoor’s operating margin has been trending down over the last 12 months and averaged negative 10.8% over the last two years. Unprofitable consumer discretionary companies with falling margins deserve extra scrutiny because they’re spending heavily to stay relevant, an unsustainable practice.
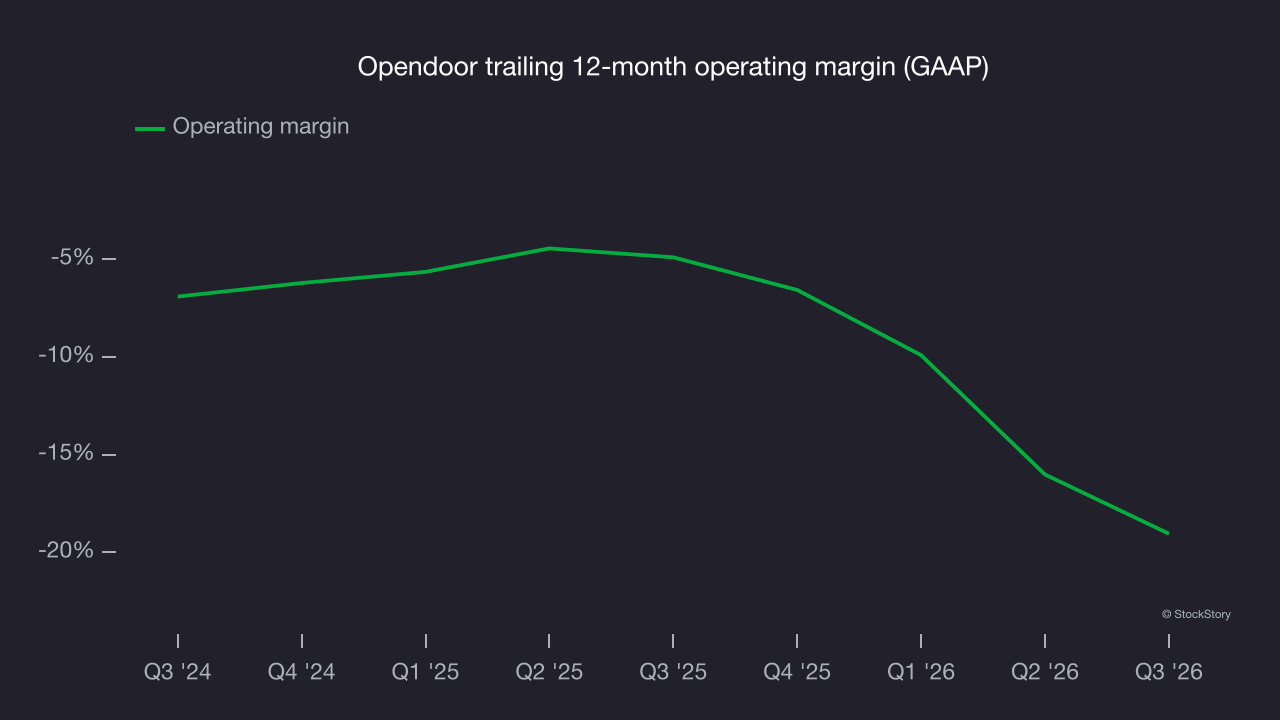
This quarter, Opendoor generated a negative 18.3% operating margin. The company’s persistent lack of profits is a concern.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Opendoor’s losses deepened over the last five years as its EPS dropped 10.6% annually. Companies with falling EPS warrant caution, as diminishing earnings could imply changing secular trends and preferences. Consumer discretionary companies are particularly exposed to this, and if those trends shift unexpectedly, Opendoor’s low margin of safety could leave its stock price susceptible to large declines.
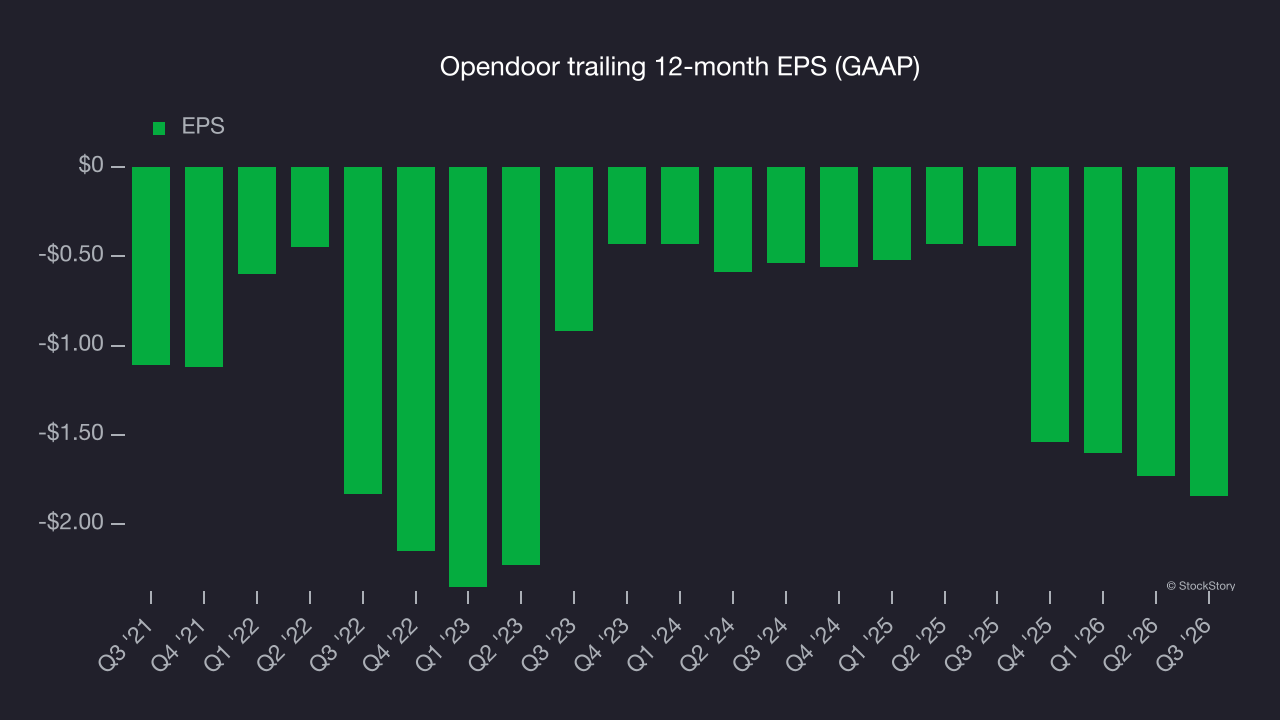
In Q3, Opendoor reported EPS of negative $0.23, down from negative $0.12 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Opendoor to narrow its losses. Analysts forecast its full-year EPS will improve from negative $1.84 to negative $0.51, according to S&P.
Key takeaways from Opendoor’s Q3 results
Opendoor’s next-quarter EBITDA guidance was a clear positive, coming in well above analysts’ consensus estimates. But Q3 was softer overall, with both revenue and EBITDA missing Wall Street’s consensus estimates. Shares remained flat at $1.78 immediately after the release.
Opendoor underperformed this quarter. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. For more on Opendoor, read our full research report here (it’s free).