As the Q3 earnings season wraps, let’s dig into this quarter’s best and worst performers in the diversified financial services industry, including Donnelley Financial Solutions (NYSE: DFIN) and its peers.
Diversified financial services encompass specialized offerings outside traditional categories. These firms benefit from identifying niche market opportunities, developing tailored financial products, and often facing less direct competition. Challenges include scale limitations, regulatory classification uncertainties, and the need to continuously innovate to maintain market differentiation against larger competitors expanding their offerings.
The 10 diversified financial services stocks we track reported a satisfactory Q3. As a group, revenues beat analysts’ consensus estimates by 0.7% while next quarter’s revenue guidance was 2.2% above.
In light of this news, share prices of the companies have held steady as they are up 2.5% on average since the latest earnings results.
Best Q3: Donnelley Financial Solutions (NYSE: DFIN)
Born from the need to navigate increasingly complex financial regulations in the digital age, Donnelley Financial Solutions (NYSE: DFIN) provides software and technology-enabled services that help companies comply with SEC regulations and manage financial transactions and reporting requirements.
Donnelley Financial Solutions reported revenues of $185 million, up 5.5% year on year. This print exceeded analysts’ expectations by 2.8%. Overall, it was a very strong quarter for the company with a beat of analysts’ EPS estimates.
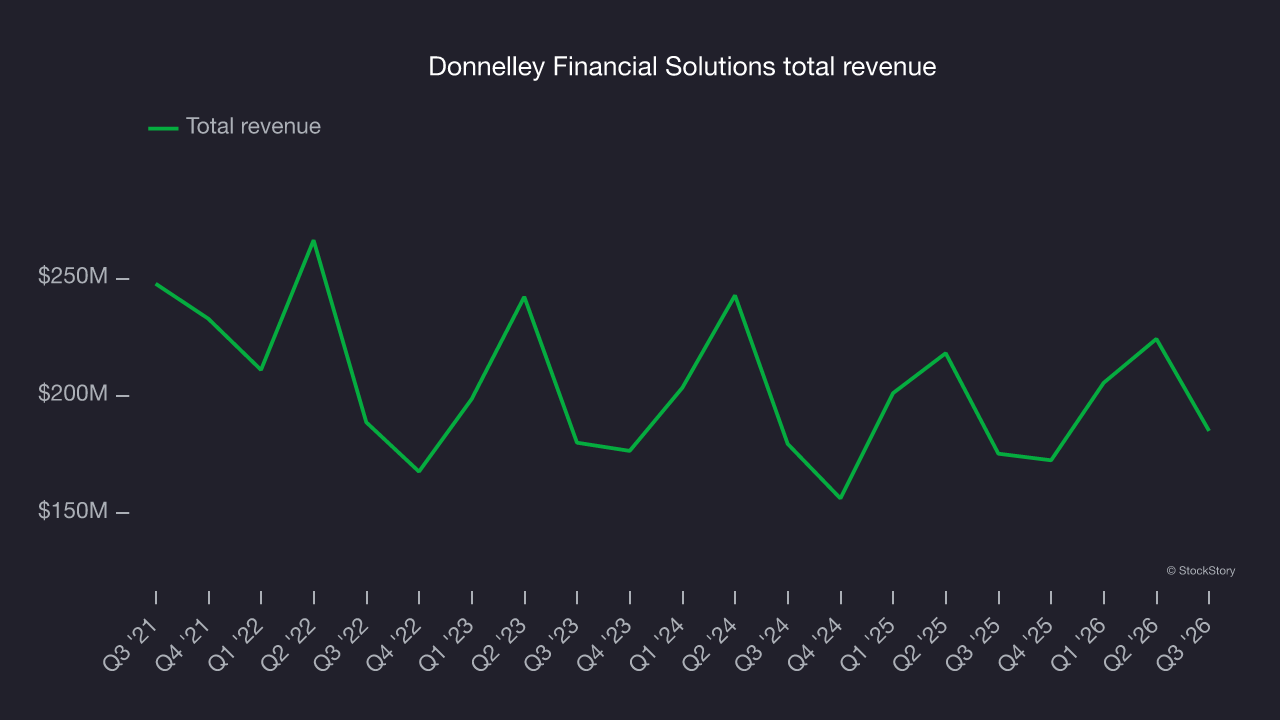
Donnelley Financial Solutions scored the highest guidance raise among its peers. Unsurprisingly, the stock is up 27.4% since reporting and currently trades at $67.65.
Is now the time to buy Donnelley Financial Solutions? Access our full analysis of the earnings results here, it’s free.
WEX (NYSE: WEX)
Originally founded in 1983 as Wright Express to serve the fleet card market, WEX (NYSE: WEX) provides payment processing and business solutions across fleet management, employee benefits, and corporate payments sectors.
WEX reported revenues of $780.1 million, up 12.8% year on year, outperforming analysts’ expectations by 3.2%. The business had a favorable quarter with full-year EPS guidance exceeding analysts’ expectations and a solid beat of analysts’ EBITDA estimates.
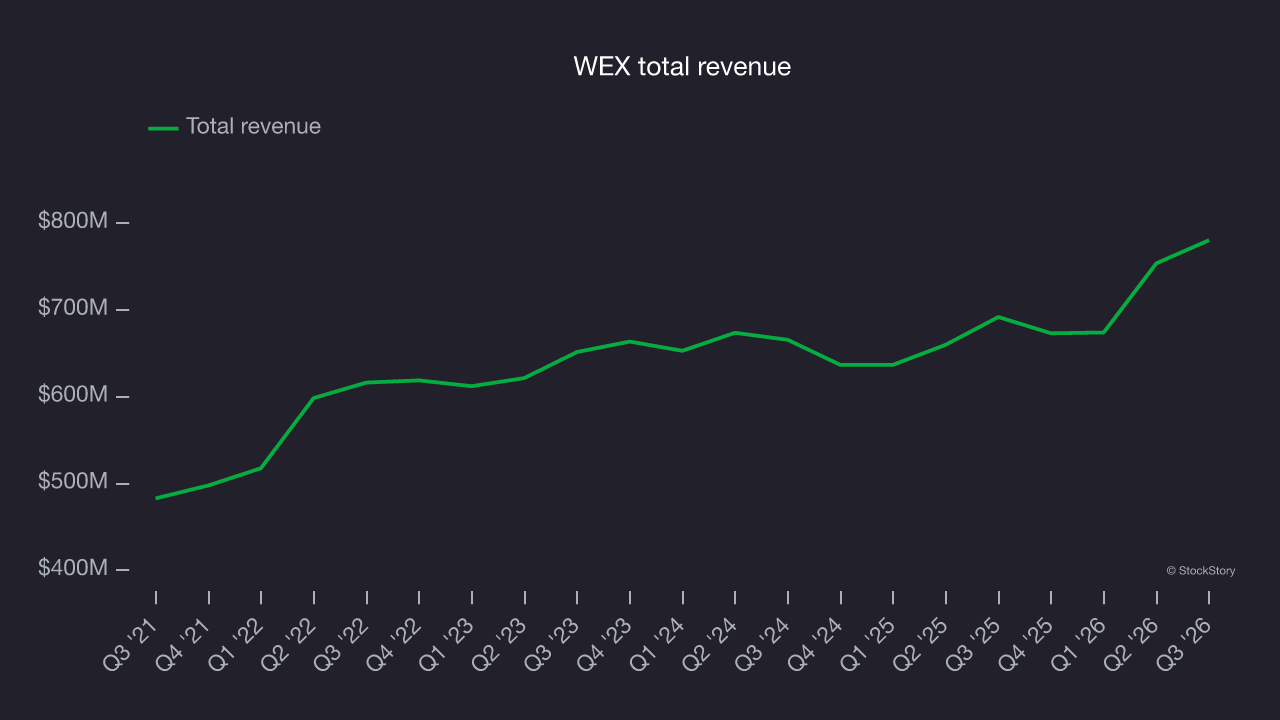
WEX delivered the highest full-year guidance raise in the group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 3.6% since reporting. It currently trades at $182.55.
Is now the time to buy WEX? Access our full analysis of the earnings results here, it’s free.
Weakest Q3: Payoneer (NASDAQ: PAYO)
Founded during the early days of global e-commerce in 2005 to solve international payment challenges, Payoneer (NASDAQ: PAYO) provides financial technology services that enable small and medium-sized businesses to send and receive payments globally across borders.
Payoneer reported revenues of $276.9 million, up 2.2% year on year, falling short of analysts’ expectations by 2.8%. It was an underwhelming quarter as it posted a significant miss of analysts’ EBITDA estimates and a miss of analysts’ yield estimates.
The stock is flat since the results and currently trades at $7.16.
Read our full analysis of Payoneer’s results here.
NCR Atleos (NYSE: NATL)
Spun off from NCR Voyix in 2023 to focus exclusively on self-service banking technology, NCR Atleos (NYSE: NATL) provides self-directed banking solutions including ATM and interactive teller machine technology, software, services, and a surcharge-free ATM network for financial institutions and retailers.
NCR Atleos reported revenues of $1.10 billion, down 2% year on year. This result came in 3.3% below analysts’ expectations. All in all, it was a mixed quarter for the company.
NCR Atleos had the weakest performance against analyst estimates of the whole group. The stock is up 2.7% since reporting and currently trades at $47.91.
Read our full, actionable report on NCR Atleos here, it’s free.
Corpay (NYSE: CPAY)
Formerly known as FLEETCOR until its 2024 rebrand, Corpay (NYSE: CPAY) provides specialized payment solutions for businesses to manage vehicle expenses, corporate payments, and lodging costs with enhanced control and reporting capabilities.
Corpay reported revenues of $1.38 billion, up 17.9% year on year. This number beat analysts’ expectations by 1.7%. It was a solid quarter as it also recorded full-year EPS guidance topping analysts’ expectations and a decent beat of analysts’ EBITDA estimates.
Corpay had the weakest full-year guidance update in the group. The stock is up 8.6% since reporting and currently trades at $454.44.
Read our full, actionable report on Corpay here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 6 Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.