Looking back on specialty equipment distributors stocks’ Q2 earnings, we examine this quarter’s best and worst performers, including SiteOne (NYSE: SITE) and its peers.
Historically, specialty equipment distributors have boasted deep selection and expertise in sometimes narrow areas like single-use packaging or unique lighting equipment. Additionally, the industry has evolved to include more automated industrial equipment and machinery over the last decade, driving efficiencies and enabling valuable data collection. Specialty equipment distributors whose offerings keep up with these trends can take share in a still-fragmented market, but like the broader industrials sector, this space is at the whim of economic cycles that impact the capital spending and manufacturing propelling industry volumes.
The 8 specialty equipment distributors stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 5.1%.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 6.5% since the latest earnings results.
Weakest Q2: SiteOne (NYSE: SITE)
Known for distributing John Deere tractors and LESCO turf care products, SiteOne Landscape Supply (NYSE: SITE) provides landscaping products and services to professionals, including irrigation, lighting, and nursery supplies.
SiteOne reported revenues of $1.53 billion, up 4.7% year on year. This print fell short of analysts’ expectations by 0.7%. Overall, it was a softer quarter for the company with a significant miss of analysts’ EPS estimates and a miss of analysts’ EBITDA estimates.
“We delivered a solid second quarter performance with 5% growth in Net sales and Adjusted EBITDA despite softer end markets,” said Doug Black, Chairman and CEO of SiteOne.
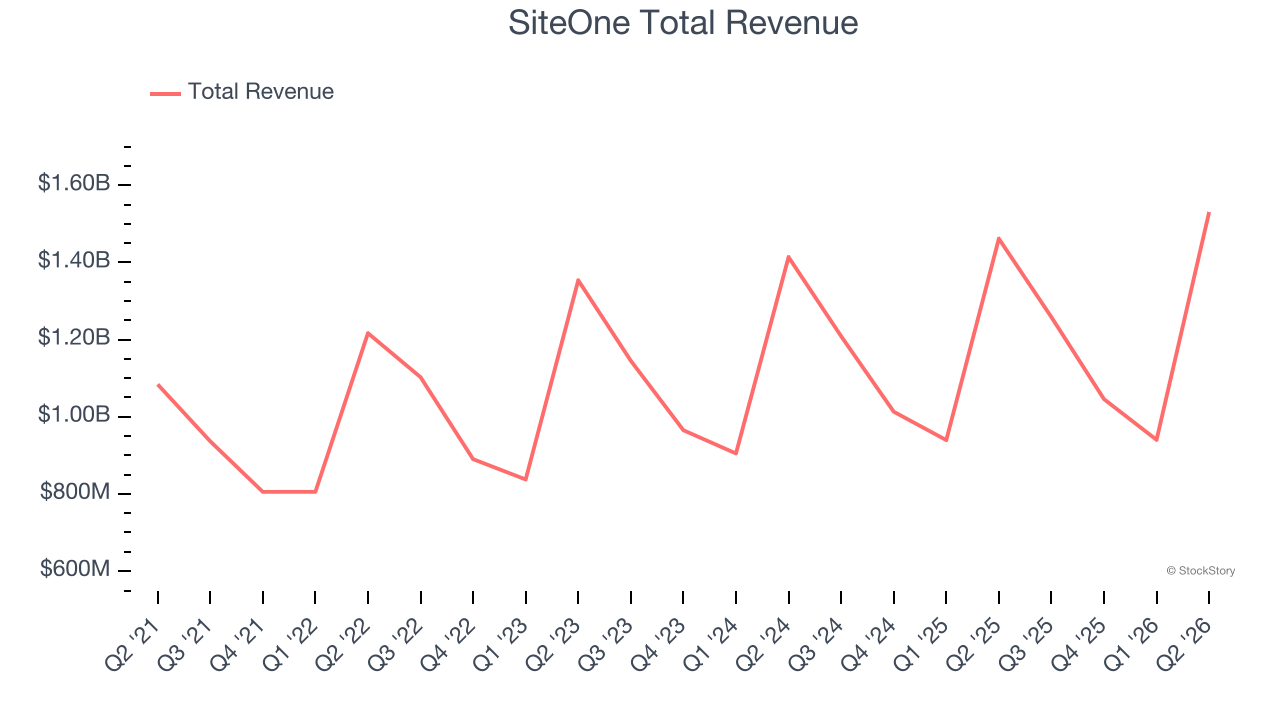
The market seems disappointed with the results as the stock is down 9.4% since reporting and currently trades at $93.79.
Read our full report on SiteOne here, it’s free.
Best Q2: Richardson Electronics (NASDAQ: RELL)
Founded in 1947, Richardson Electronics (NASDAQ: RELL) is a distributor of power grid and microwave tubes as well as consumables related to those products.
Richardson Electronics reported revenues of $66.2 million, up 27.6% year on year, outperforming analysts’ expectations by 19.6%. The business had an incredible quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
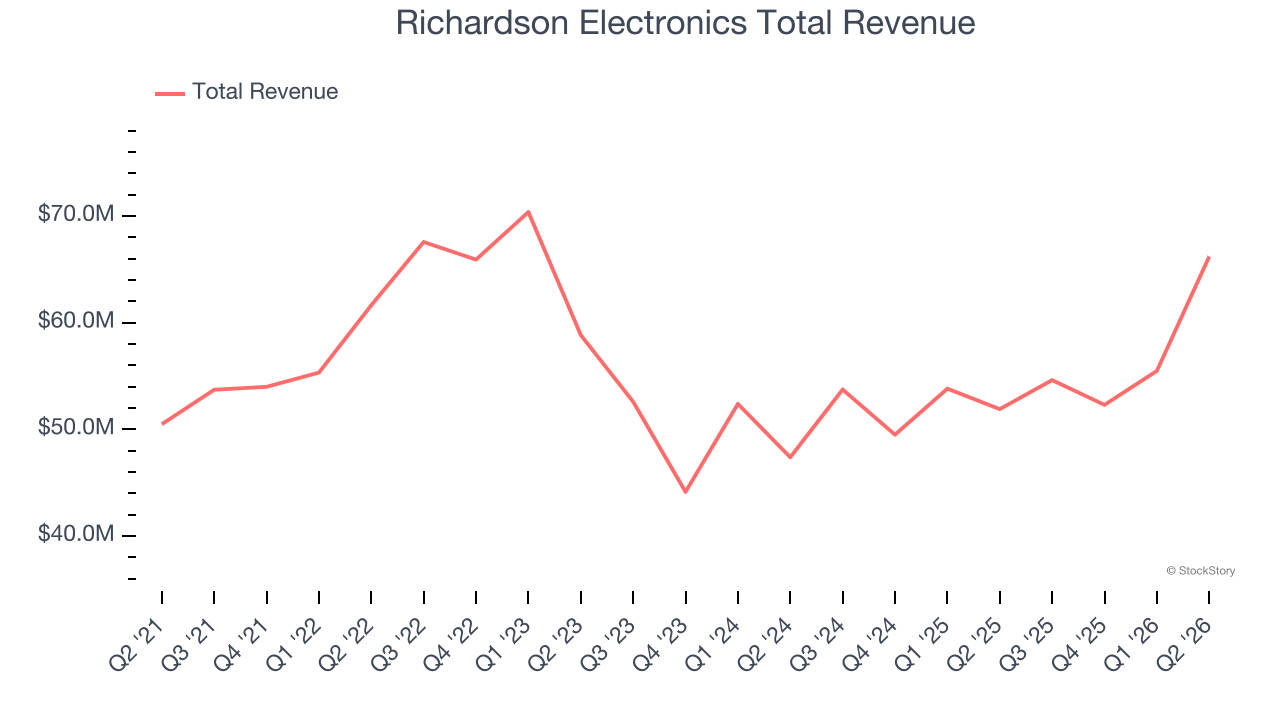
Richardson Electronics delivered the biggest analyst estimate beat and fastest revenue growth among its peers. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 6.2% since reporting. It currently trades at $16.90.
Is now the time to buy Richardson Electronics? Access our full analysis of the earnings results here, it’s free.
Hudson Technologies (NASDAQ: HDSN)
Founded in 1991, Hudson Technologies (NASDAQ: HDSN) specializes in refrigerant services and solutions, providing refrigerant sales, reclamation, and recycling.
Hudson Technologies reported revenues of $78.35 million, up 7.5% year on year, exceeding analysts’ expectations by 5.6%. Still, it was a mixed quarter as it posted a significant miss of analysts’ EPS estimates.
As expected, the stock is down 16.7% since the results and currently trades at $5.18.
Read our full analysis of Hudson Technologies’s results here.
Karat Packaging (NASDAQ: KRT)
Founded as Lollicup, Karat Packaging (NASDAQ: KRT) distributes and manufactures environmentally-friendly disposable foodservice packaging solutions.
Karat Packaging reported revenues of $136.3 million, up 9.9% year on year. This result surpassed analysts’ expectations by 0.6%. Overall, it was an exceptional quarter as it also recorded a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
The stock is up 25.2% since reporting and currently trades at $53.03.
Read our full, actionable report on Karat Packaging here, it’s free.
Alta (NYSE: ALTG)
Founded in 1984, Alta Equipment Group (NYSE: ALTG) is a provider of industrial and construction equipment and services across the Midwest and Northeast United States.
Alta reported revenues of $475.5 million, down 1.2% year on year. This print came in 3.1% below analysts’ expectations. In spite of that, it was a strong quarter as it produced a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
Alta had the weakest performance against analyst estimates and slowest revenue growth of the whole group. The stock is down 18.2% since reporting and currently trades at $6.03.
Read our full, actionable report on Alta here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.