The end of an earnings season can be a great time to discover new stocks and assess how companies are handling the current business environment. Let’s take a look at how Waste Management (NYSE: WM) and the rest of the waste management stocks fared in Q2.
Waste management companies can possess licenses permitting them to handle hazardous materials. Furthermore, many services are performed through contracts and statutorily mandated, non-discretionary, or recurring, leading to more predictable revenue streams. However, regulation can be a headwind, rendering existing services obsolete or forcing companies to invest precious capital to comply with new, more environmentally-friendly rules. Lastly, waste management companies are at the whim of economic cycles. Interest rates, for example, can greatly impact industrial production or commercial projects that create waste and byproducts.
The 8 waste management stocks we track reported a mixed Q2. As a group, revenues beat analysts’ consensus estimates by 0.8%.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 5.8% since the latest earnings results.
Waste Management (NYSE: WM)
Headquartered in Houston, Waste Management (NYSE: WM) is a provider of comprehensive waste management services in North America.
Waste Management reported revenues of $6.68 billion, up 4% year on year. This print was in line with analysts’ expectations, but overall, it was a mixed quarter for the company with a decent beat of analysts’ EBITDA estimates but full-year revenue guidance slightly missing analysts’ expectations.
“Second quarter earnings growth, margin expansion, and cash flow generation reflect the strength of our business model and consistent execution from the WM team,” said Jim Fish, WM’s CEO.
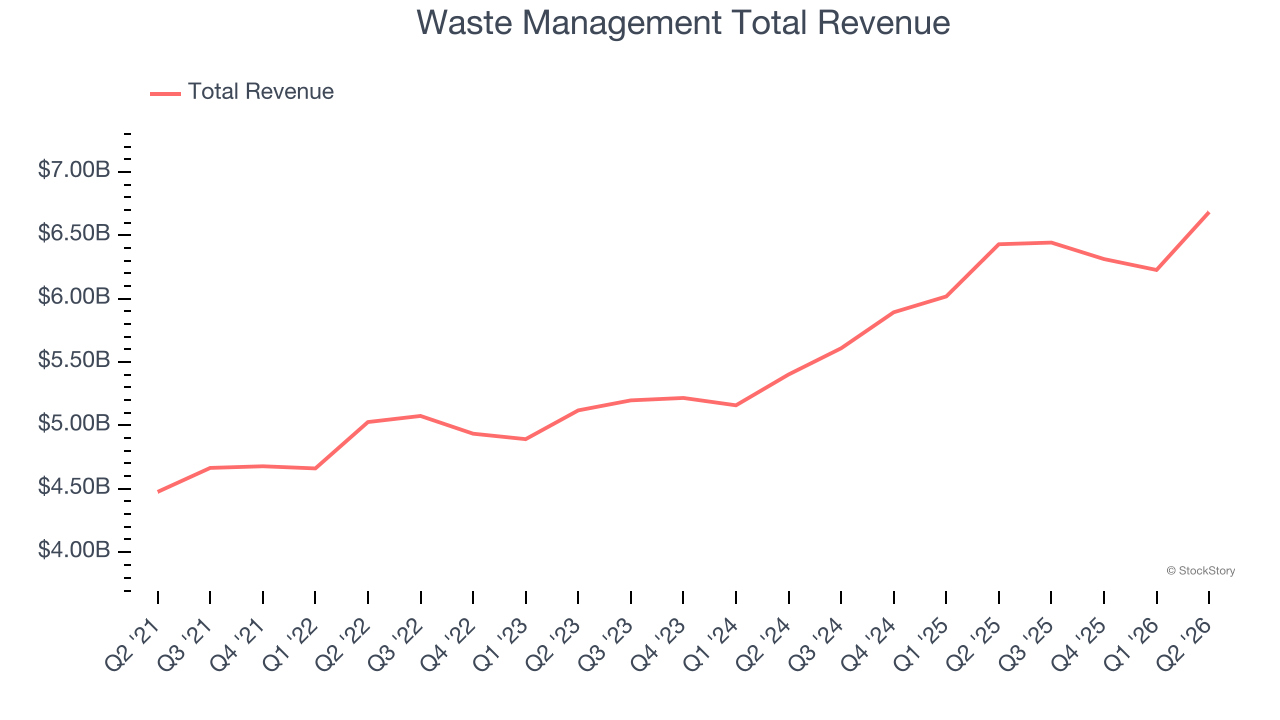
The market seems disappointed with the results as the stock is down 13.3% since reporting and currently trades at $207.53.
Is now the time to buy Waste Management? Access our full analysis of the earnings results here, it’s free.
Best Q2: Clean Harbors (NYSE: CLH)
Established in 1980, Clean Harbors (NYSE: CLH) provides environmental and industrial services like hazardous and non-hazardous waste disposal and emergency spill cleanups.
Clean Harbors reported revenues of $1.74 billion, up 11.9% year on year, outperforming analysts’ expectations by 6.1%. The business had a stunning quarter with EBITDA guidance for next quarter exceeding analysts’ expectations.
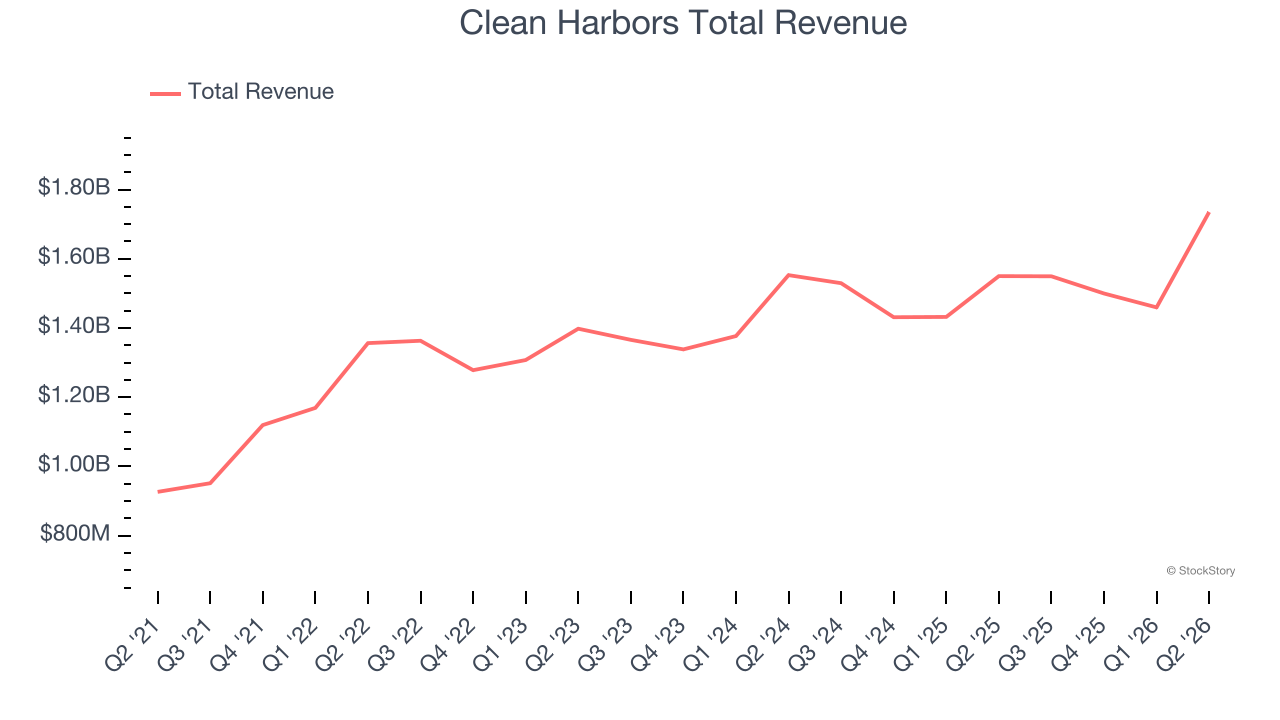
Clean Harbors achieved the biggest analyst estimate beat in the group. The market seems content with the results as the stock is up 2.6% since reporting. It currently trades at $311.49.
Is now the time to buy Clean Harbors? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Perma-Fix (NASDAQ: PESI)
Tackling hazardous waste challenges since 1990, Perma-Fix (NASDAQ: PESI) provides environmental waste treatment services.
Perma-Fix reported revenues of $12.89 million, down 11.7% year on year, in line with analysts’ expectations. It was a softer quarter as it posted a significant miss of analysts’ EBITDA estimates and a significant miss of analysts’ EPS estimates.
As expected, the stock is down 10.8% since the results and currently trades at $17.34.
Read our full analysis of Perma-Fix’s results here.
Casella Waste Systems (NASDAQ: CWST)
Starting with the founder picking up garbage with a pickup truck he purchased using savings from high school, Casella (NASDAQ: CWST) offers waste management services for businesses, residents, and the government.
Casella Waste Systems reported revenues of $543.7 million, up 16.9% year on year. This number topped analysts’ expectations by 3.5%. Overall, it was a strong quarter as it also recorded a beat of analysts’ EPS estimates and full-year revenue guidance slightly topping analysts’ expectations.
Casella Waste Systems scored the fastest revenue growth and highest full-year guidance raise of the whole group. The stock is down 5.6% since reporting and currently trades at $85.41.
Read our full, actionable report on Casella Waste Systems here, it’s free.
Waste Connections (NYSE: WCN)
Operating a network of municipal solid waste landfills in the U.S. and Canada, Waste Connections (NYSE: WCN) is North America's third-largest waste management company providing collection, disposal, and recycling services.
Waste Connections reported revenues of $2.56 billion, up 6.4% year on year. This print beat analysts’ expectations by 0.9%. It was a strong quarter as it also logged a beat of analysts’ EPS and EBITDA estimates.
The stock is down 7.4% since reporting and currently trades at $155.55.
Read our full, actionable report on Waste Connections here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.