
Earnings results often indicate what direction a company will take in the months ahead. With Q3 behind us, let’s have a look at Xylem (NYSE: XYL) and its peers.
Trends towards conservation and reducing groundwater depletion are putting water infrastructure and treatment products front and center. Companies that can innovate and create solutions–especially automated or connected solutions–to address these thematic trends will create incremental demand and speed up replacement cycles. On the other hand, water infrastructure and treatment companies are at the whim of economic cycles. Consumer spending and interest rates, for example, can greatly impact the industrial production that drives demand for these companies’ offerings.
The 5 water infrastructure stocks we track reported a satisfactory Q3. As a group, revenues missed analysts’ consensus estimates by 6.2%.
While some water infrastructure stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 2.6% since the latest earnings results.
Weakest Q3: Xylem (NYSE: XYL)
Formed through a spinoff, Xylem (NYSE: XYL) manufactures and services engineered products across a wide variety of applications primarily in the water sector.
Xylem reported revenues of $2.20 billion, down 3% year on year. This print fell short of analysts’ expectations by 3.5%. Overall, it was a softer quarter for the company with full-year EPS guidance missing analysts’ expectations significantly and a significant miss of analysts’ organic revenue estimates.
“We’re moving with urgency to shape Xylem around the markets where our capabilities can deliver the greatest customer value and strongest long-term growth," said Matthew Pine, president and CEO of Xylem. "The resilience we’ve built, evident this quarter, allows us to make those choices deliberately and from a position of strength.”
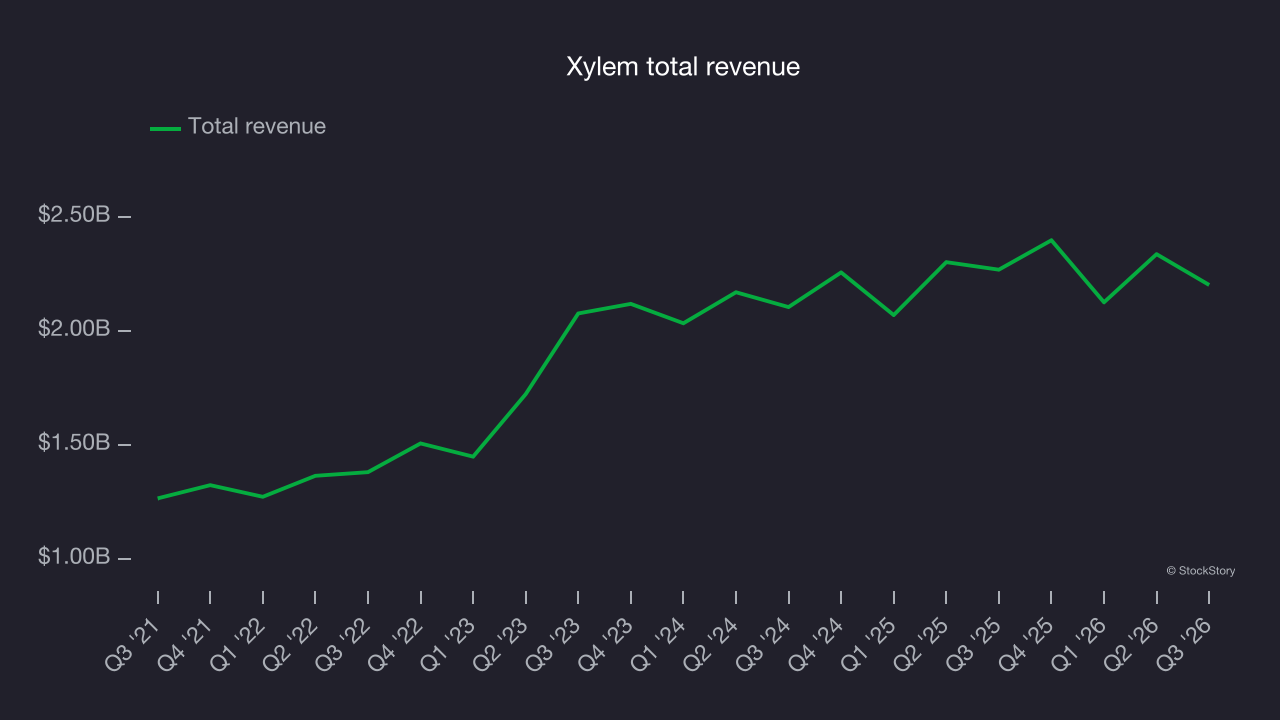
The market seems disappointed with the results as the stock is down 9.6% since reporting and currently trades at $97.82.
Is now the time to buy Xylem? Access our full analysis of the earnings results here, it’s free.
Best Q3: Watts Water Technologies (NYSE: WTS)
Founded in 1874, Watts Water (NYSE: WTS) specializes in manufacturing water products and systems for residential, commercial, and industrial applications globally.
Watts Water Technologies reported revenues of $728 million, up 19% year on year, outperforming analysts’ expectations by 5.2%. The business had a stunning quarter with an impressive beat of analysts’ organic revenue estimates and a beat of analysts’ EPS estimates.
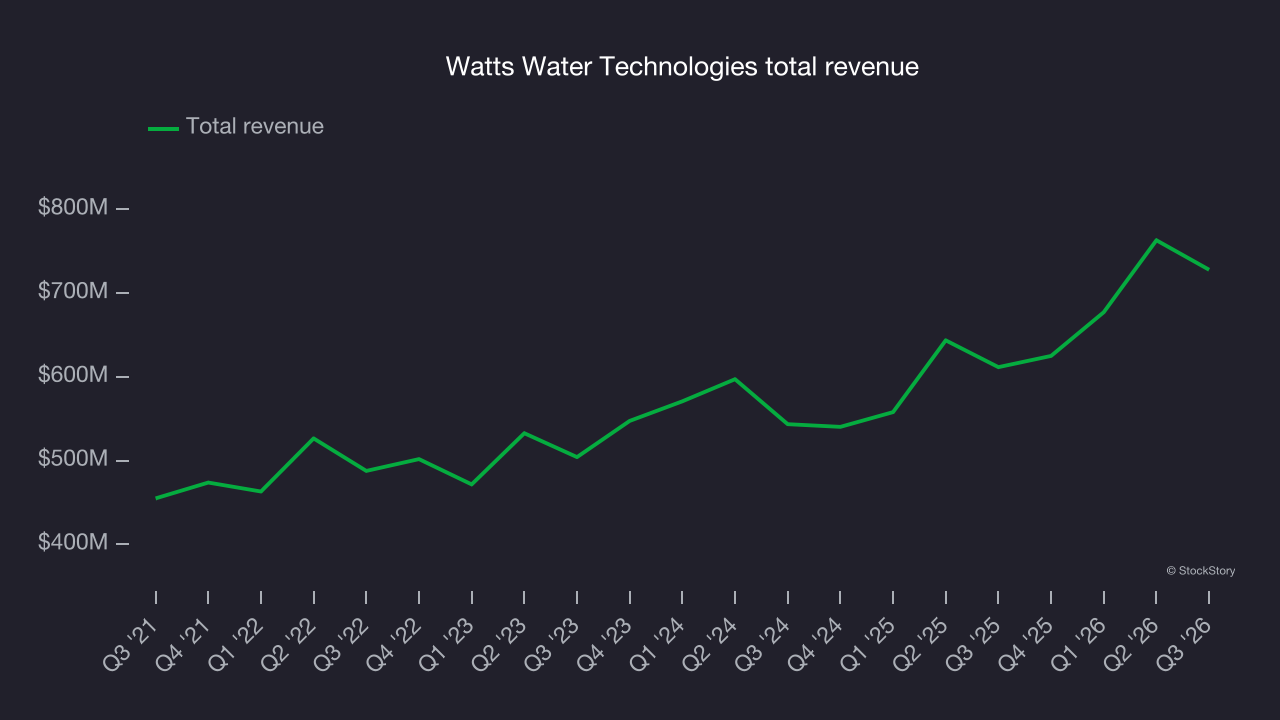
Watts Water Technologies pulled off the biggest analyst estimate beat and fastest revenue growth among its peers. However, the results were likely priced into the stock as it’s traded sideways since reporting. Shares currently sit at $350.12.
Is now the time to buy Watts Water Technologies? Access our full analysis of the earnings results here, it’s free.
Mueller Water Products (NYSE: MWA)
As one of the oldest companies in the water infrastructure industry, Mueller (NYSE: MWA) is a provider of water infrastructure products and flow control systems for various sectors.
Mueller Water Products reported revenues of $376.5 million, down 1.1% year on year, exceeding analysts’ expectations by 0.6%. Still, it was a slower quarter as it posted full-year revenue guidance missing analysts’ expectations significantly.
Mueller Water Products delivered the weakest full-year guidance update of the whole group. Interestingly, the stock is up 1.4% since the results and currently trades at $24.39.
Read our full analysis of Mueller Water Products’s results here.
Tennant (NYSE: TNC)
As the world’s largest manufacturer of autonomous mobile robots, Tennant (NYSE: TNC) designs, manufactures, and sells cleaning products to various sectors.
Tennant reported revenues of $322.3 million, up 6.3% year on year. This result missed analysts’ expectations by 2.6%. In spite of that, it was a strong quarter as it produced a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
Tennant delivered the highest full-year guidance raise in the group. The stock is up 3.1% since reporting and currently trades at $70.86.
Read our full, actionable report on Tennant here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.




