
Food distribution giant US Foods (NYSE: USFD) missed Wall Street’s revenue expectations in Q3 2026 as revenue rose 2.1% year on year to $10.4 billion. Its non-GAAP profit of $1.26 per share was 1.1% above analysts’ consensus estimates.
For more on US Foods, read the full research report for free.
US Foods (USFD) Q3 2026 highlights:
- Revenue $10.4 billion vs S&P analysts’ consensus estimates of $10.59 billion (2.1% year-on-year growth, 1.8% miss)
- Adjusted EPS $1.26 vs S&P analysts’ consensus estimates of $1.25 (1.1% beat)
- Adjusted EBITDA $555 million vs analysts’ consensus estimates of $548.9 million (5.3% margin, 1.1% beat)
- Operating margin 3.6%, in line with the same quarter last year
- Sales volumes rose 1.3% year on year, in line with the same quarter last year
- Market capitalization $23.78 billion
“Our third quarter results reflect the strength of our strategy and disciplined execution, with continued market share gains and strong earnings growth,” said Dave Flitman, Chair of the Board and CEO. “We again delivered 5% Independent Restaurant case growth and extended our track record of share gains to 22 consecutive quarters with Independent Restaurants and 24 consecutive quarters with Healthcare. Building on the progress we have made over the past several years, our team continues to demonstrate the impact of our self-help initiatives and laser focus on execution, driving 10% Adjusted EBITDA growth and 18% Adjusted Diluted EPS growth.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can report a good quarter or two, but the best consistently grow over the long haul. US Foods’s revenue grew at a weak 7.6% annualized rate over the last five years, falling short of the consumer discretionary sector benchmark.
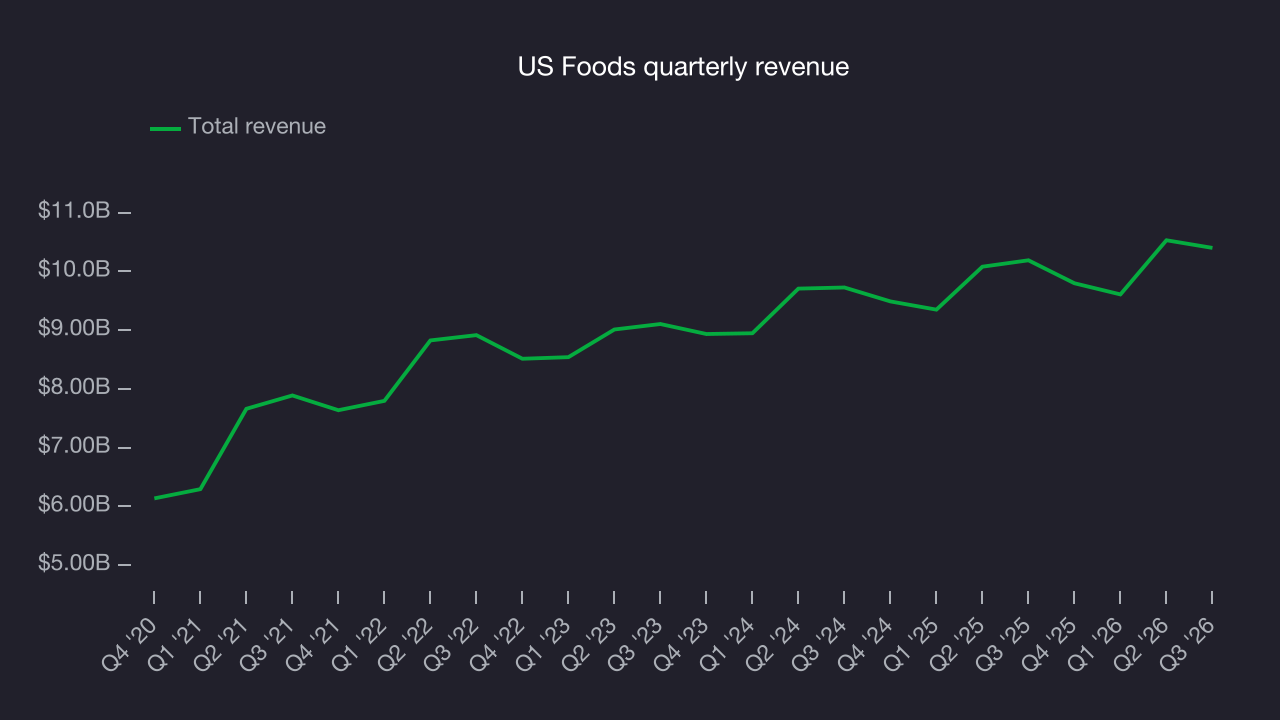
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. US Foods’s recent performance shows its demand has slowed as its annualized revenue growth of 4% over the last two years was below its five-year trend. Decelerating revenue growth is a concern in this sector, as it could signal changing consumer tastes aided by low switching costs. 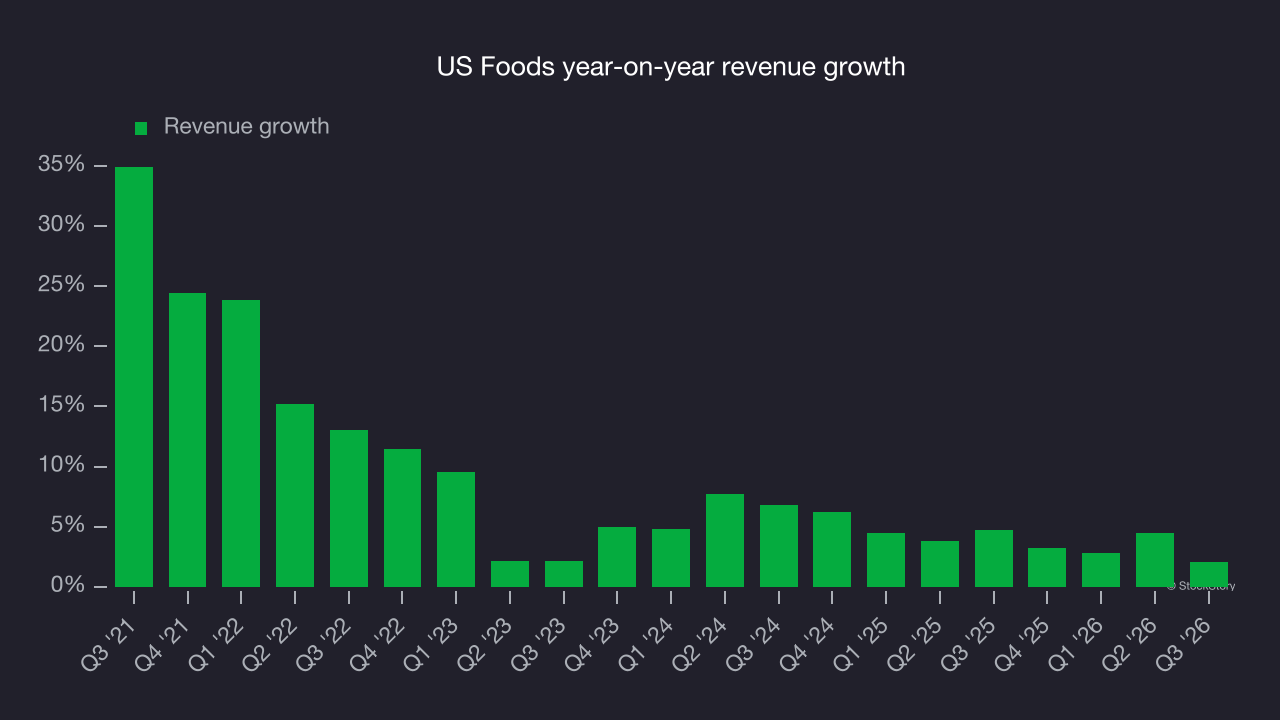
Unit sales offer a closer look at the company’s revenue dynamics. Over the last two years, US Foods’s units sold averaged 1.6% year-on-year growth. Revenue growth outpaced unit growth, indicating that price increases contributed to growth. 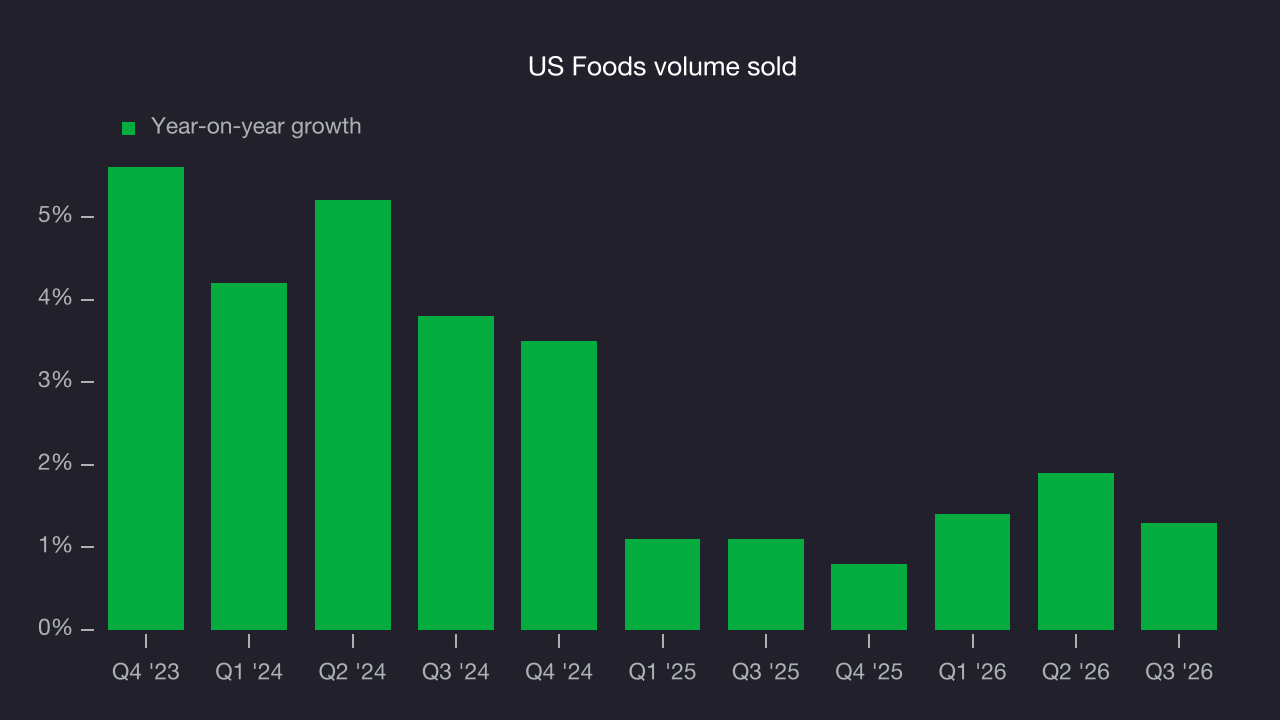
This quarter, US Foods’s revenue grew by 2.1% year on year to $10.4 billion, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 6.9% over the next 12 months, according to S&P. While this projection indicates its newer products and services will spur better top-line performance, it is still below average for the sector.
Operating margin
US Foods’ operating margin has been largely unchanged over the last 12 months, but margin increases from economies of scale and cost efficiencies over time would be preferable.
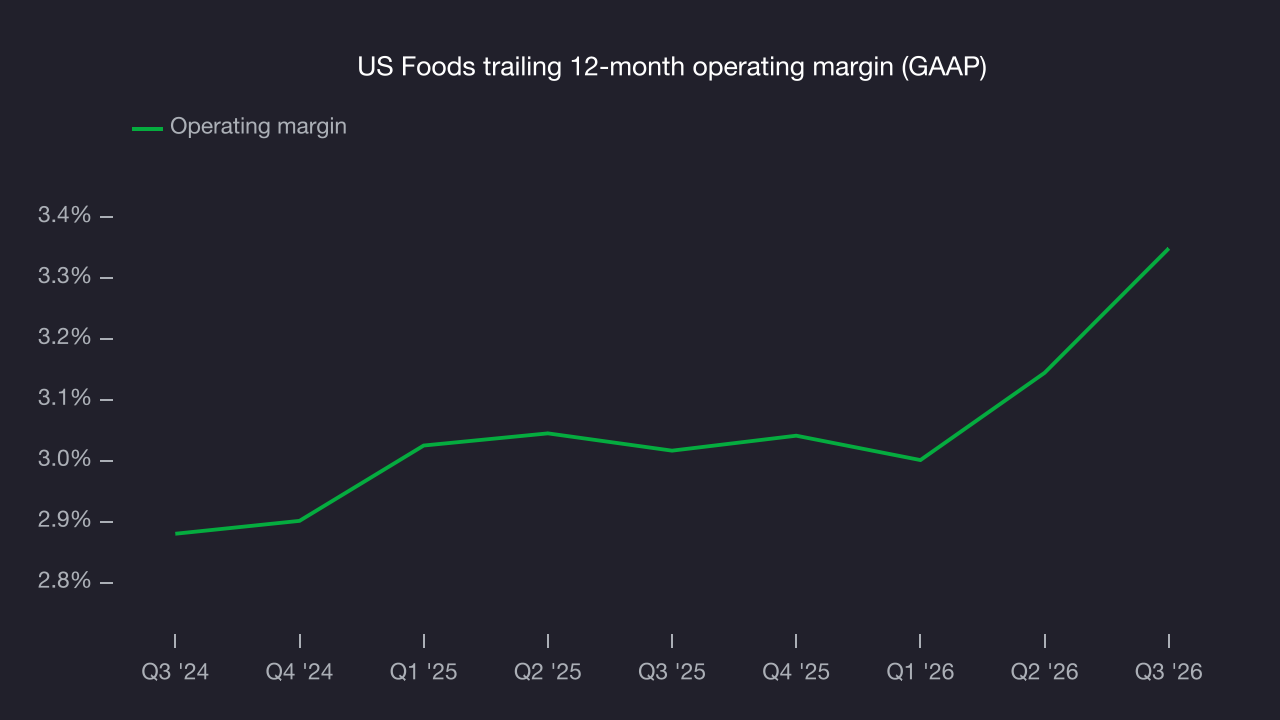
In Q3, US Foods generated an operating margin of 3.6%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
US Foods’s EPS grew at a 29.7% compounded annual growth rate over the last five years. On the positive side, this outpaced its 7.6% annualized revenue growth, indicating the company became more profitable on a per-share basis as it expanded.
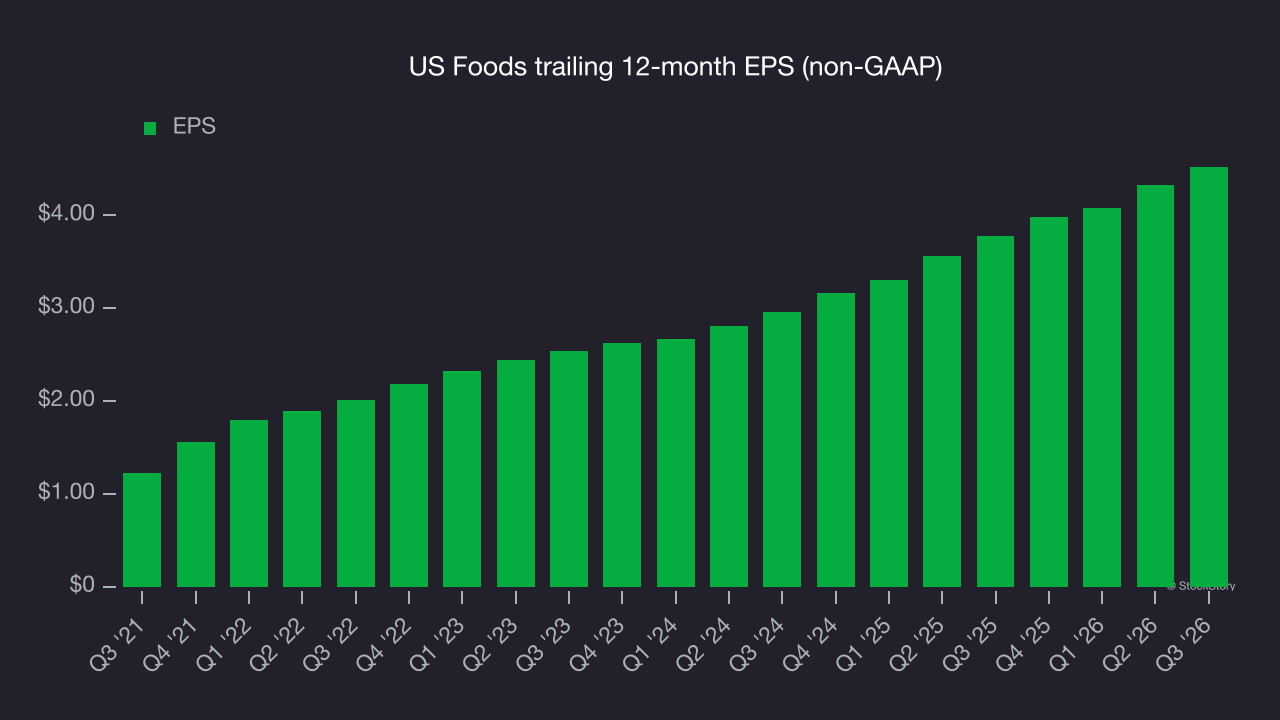
In Q3, US Foods reported adjusted EPS of $1.26, up from $1.07 in the same quarter last year. This result beat analysts’ consensus estimates by 1.1%. Over the next 12 months, Wall Street expects US Foods’s full-year EPS to grow 19.4% from $4.52 to $5.40, according to S&P.
Key takeaways from US Foods’s Q3 results
US Foods delivered a weaker quarter with few positives in the results. Shares surged 5% to $115.40 immediately after the release.
To assess whether US Foods is a buy, consider its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).




