
Medical device company Artivion (NYSE: AORT) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 9.2% year on year to $123.8 million. On the other hand, the company’s full-year revenue guidance of $488 million at the midpoint came in 0.5% below analysts’ consensus estimates. Its non-GAAP profit of $0.08 per share was 21.2% above analysts’ consensus estimates.
For more on Artivion, read our free full research report.
Artivion (AORT) Q3 2026 highlights:
- Revenue $123.8 million vs S&P analysts’ consensus estimates of $121.1 million (9.2% year-on-year growth, 2.2% beat)
- Adjusted EPS $0.08 vs S&P analysts’ consensus estimates of $0.07 (21.2% beat)
- Adjusted EBITDA $22.49 million vs analysts’ consensus estimates of $22.06 million (18.2% margin, 2% beat)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $488 million at the midpoint
- EBITDA guidance $95.5 million at the midpoint for the full year, in line with analysts’ consensus expectations
- Operating margin 2.4%, down from 11.1% in the same quarter last year
- Free cash flow -$17.57 million, down from $17.65 million in the same quarter last year
- Market capitalization $1.29 billion
"In the third quarter of 2026, we delivered 9% constant currency revenue growth, reflecting continued execution of our strategy to drive long-term, profitable growth through an expanding and clinically differentiated product portfolio. Revenue growth was led by On-X, which grew 13% on a constant currency basis compared to the third quarter of 2025. Stent grafts revenue grew 12% for the second consecutive quarter, despite a tougher AMDS prior year comparison," said Pat Mackin, Chairman, President, and Chief Executive Officer.
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Artivion’s revenue grew at a decent 10.9% compounded annual growth rate over the last five years. Its growth slightly outpaced that of the average healthcare company and shows its offerings resonate with customers.
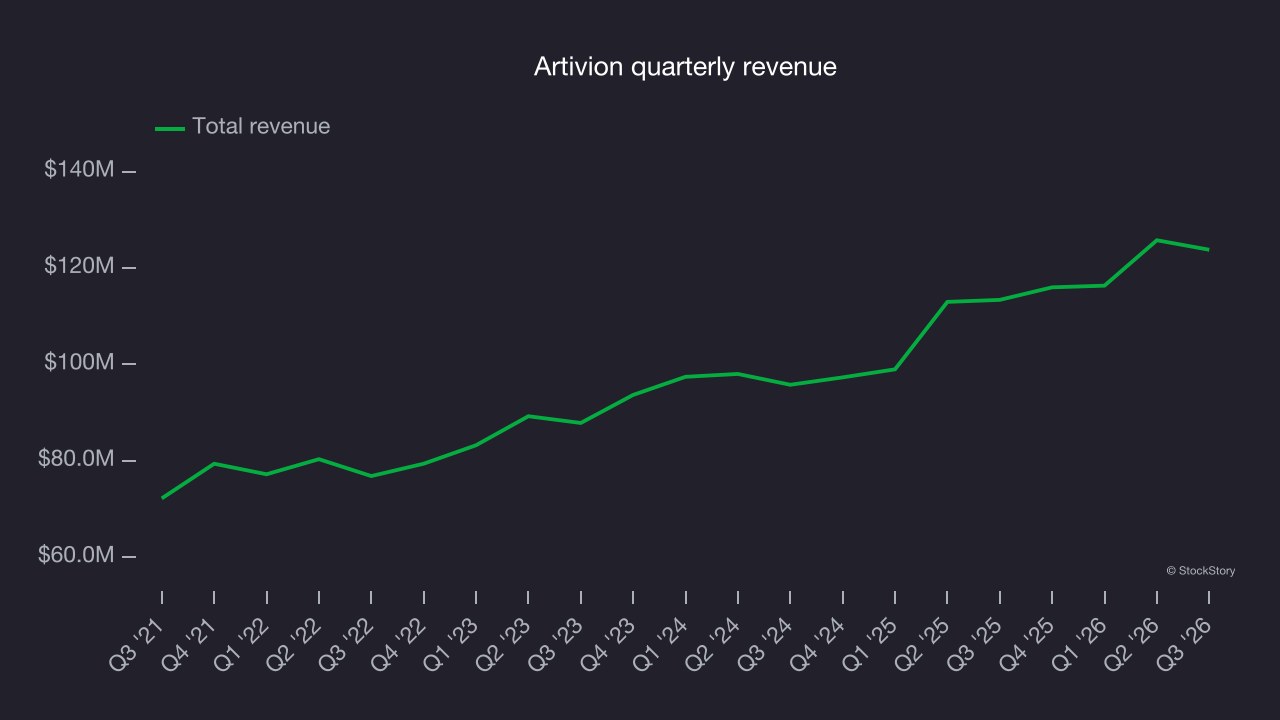
Long-term growth matters most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. Artivion’s annualized revenue growth of 11.9% over the last two years aligns with its five-year trend, suggesting its demand was stable. 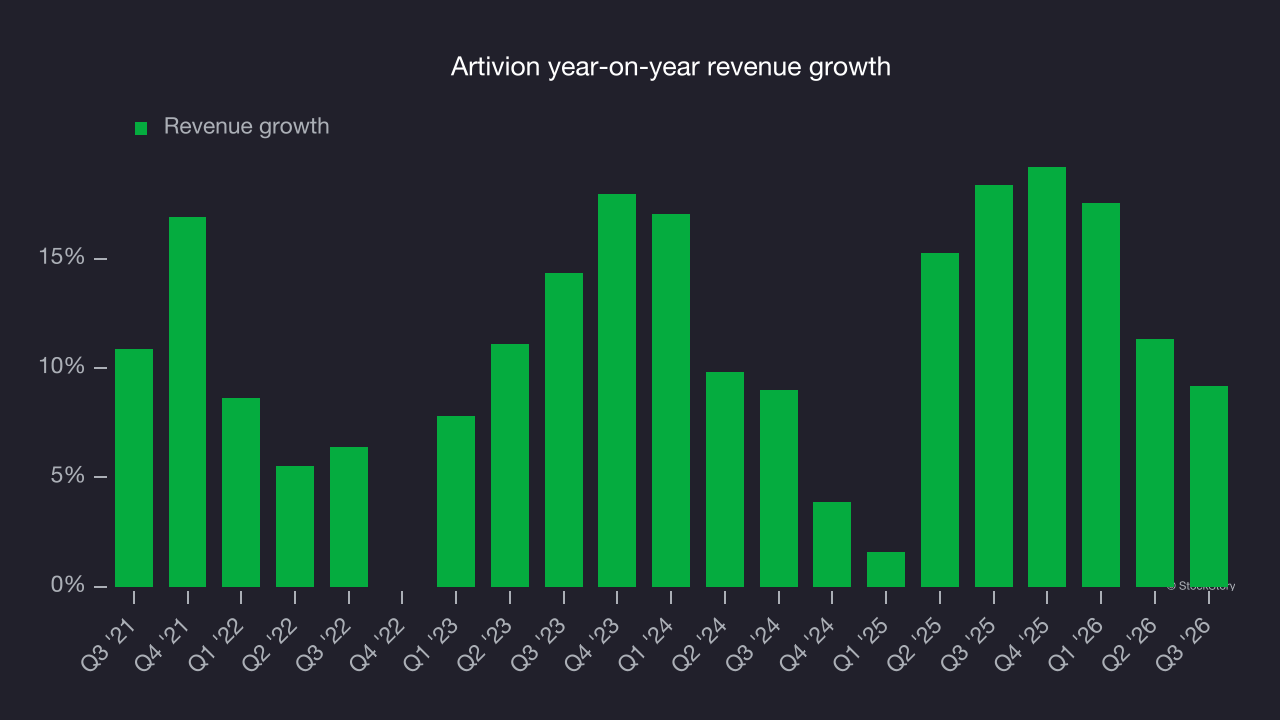
This quarter, Artivion reported year-on-year revenue growth of 9.2%, and its $123.8 million of revenue exceeded Wall Street’s consensus estimates by 2.2%.
Looking ahead, sell-side analysts expect revenue to grow 9.8% over the next 12 months, according to S&P, a slight deceleration versus the last two years. Despite the slowdown, this projection is strong and suggests the market is forecasting success for its products and services.
Adjusted operating margin
Adjusted operating margin is one of the best measures of profitability because it shows how much money a company retains after subtracting all core expenses, such as marketing and research and development. It also removes various one-time costs to give a clearer picture of normalized profits.
Artivion has done a decent job managing its cost base over the last five years. The company has produced an average adjusted operating margin of 10.6%, higher than the broader healthcare sector.
Looking at the trend in its profitability, Artivion’s adjusted operating margin rose by 3.7 percentage points over the last five years, as its revenue growth provided operating leverage. More recently, however, the company’s margin has decreased by 1.8 percentage points on a two-year basis. To meet our standard, Artivion must prove it can expand its profitability consistently.
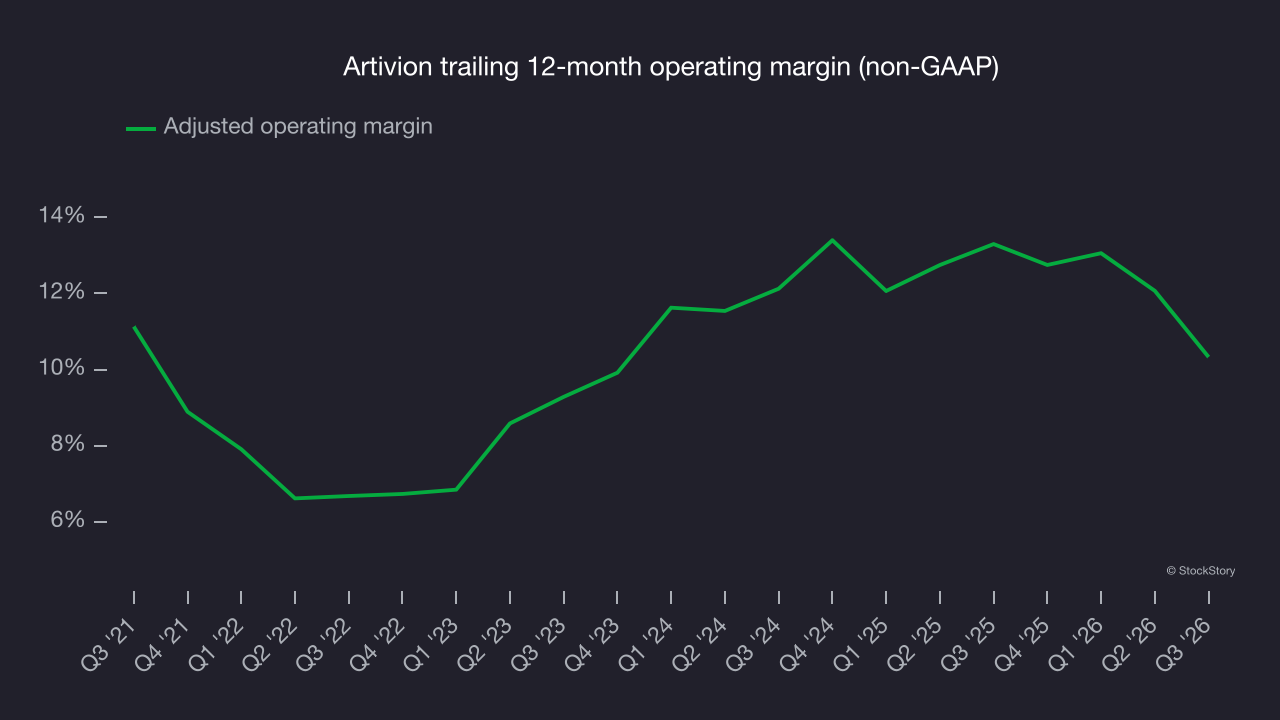
In Q3, Artivion generated an adjusted operating margin of 7.4%, down 7 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Long-term growth in earnings per share, or EPS, matters for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Artivion’s EPS grew at a solid 7.5% compounded annual growth rate over the last five years. Despite its adjusted operating margin improvement during that time, this performance was lower than its 10.9% annualized revenue growth, indicating that non-fundamental factors such as interest and taxes affected its ultimate earnings.
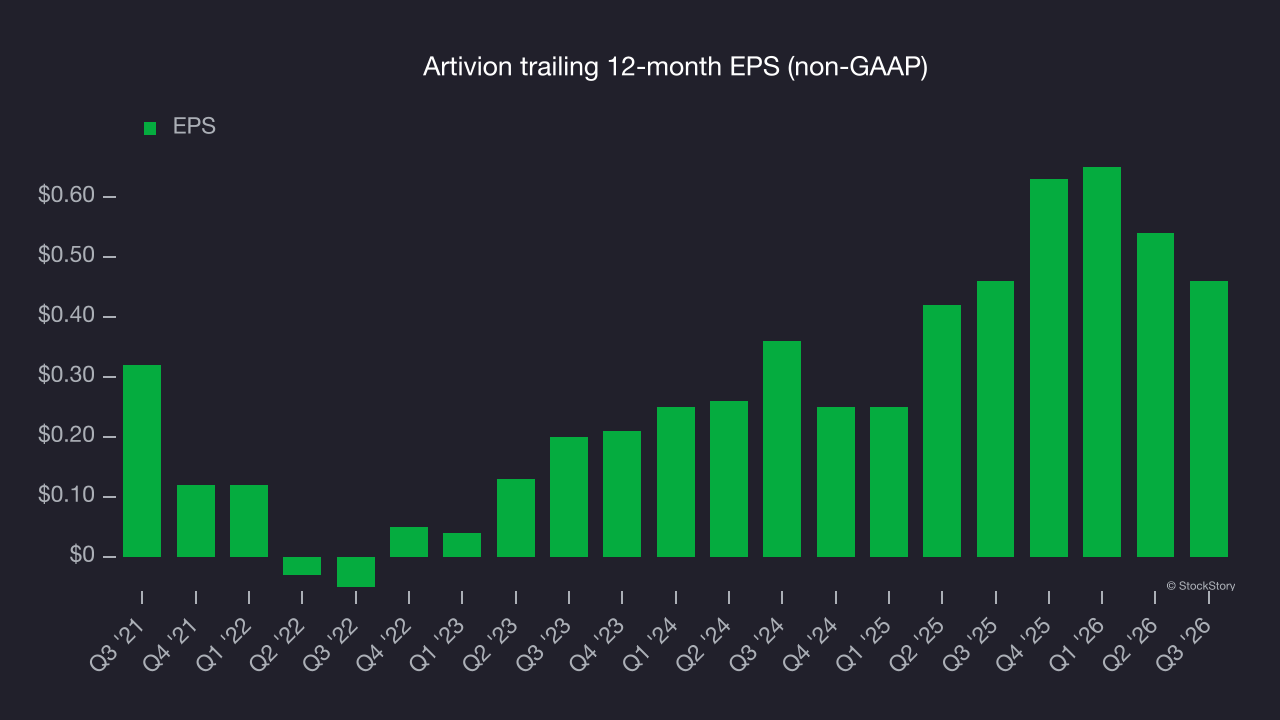
A closer look at Artivion’s earnings quality helps explain the drivers of its performance. A five-year view shows Artivion has diluted its shareholders, growing its share count by 9.6%. This dilution overshadowed its increased operational efficiency and has led to lower per share earnings. Taxes and interest expenses can also affect EPS but don’t tell us as much about a company’s fundamentals. 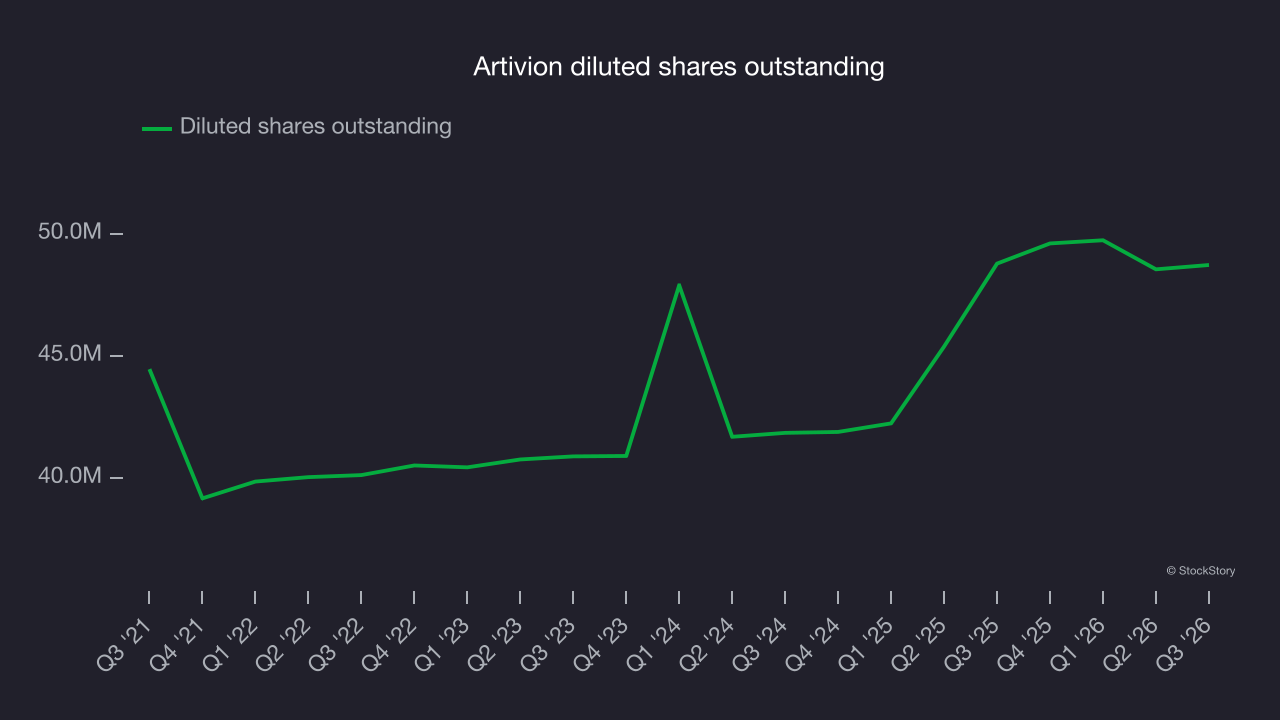
In Q3, Artivion reported adjusted EPS of $0.08, down from $0.16 in the same quarter last year. Despite falling year on year, the result came in well above analysts’ consensus estimates. Over the next 12 months, Wall Street expects Artivion’s full-year EPS to grow 39.1% from $0.46 to $0.64, according to S&P.
Key takeaways from Artivion’s Q3 results
Artivion’s Q3 results had some key positives, with EPS and revenue both topping analysts’ consensus estimates. But its full-year revenue guidance came in slightly below expectations. Shares remained flat at $25.23 immediately after the results.
Artivion had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. That decision also requires considering its valuation and business quality alongside the latest quarter. For more on Artivion, read the full research report here (it’s free).




