Flooring manufacturer Mohawk Industries (NYSE: MHK) missed Wall Street’s revenue expectations in Q3 2026 as revenue only rose 1% year on year to $2.79 billion. Its non-GAAP profit of $2.72 per share was 5.4% above analysts’ consensus estimates.
For more on Mohawk Industries, read our free full research report.
Mohawk Industries (MHK) Q3 2026 highlights:
- Revenue $2.79 billion vs S&P analysts’ consensus estimates of $2.81 billion (1% year-on-year growth, 0.9% miss)
- Adjusted EPS $2.72 vs S&P analysts’ consensus estimates of $2.58 (5.4% beat)
- Adjusted EBITDA $353.4 million vs analysts’ consensus estimates of $363.5 million (12.7% margin, 2.8% miss)
- Adjusted EPS guidance $1.40 at the midpoint for Q4 2026, below analysts’ consensus estimates of $1.64
- Operating margin 6.7%, up from 5% in the same quarter last year
- Free cash flow margin 14%, up from 11.3% in the same quarter last year
- Market capitalization $7.72 billion
Chief Executive Officer Paul De Cock stated, “We delivered a solid third quarter in a weak demand environment. We grew net sales as we executed price increases in response to rising inflation, we offset inflation with price, mix and productivity, and we are efficiently converting our earnings to strong cash flow. We are returning cash to shareholders, and our share repurchases in the third quarter were more than double what we completed in the first half of the year. Although we expect demand conditions to remain challenging and higher costs to persist, our teams are focused on serving our customers and delivering solid fourth quarter results.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years. Mohawk Industries struggled to consistently increase demand as its $11.21 billion of revenue for the trailing 12 months was close to its revenue five years ago. That underwhelming result points to poor business quality.
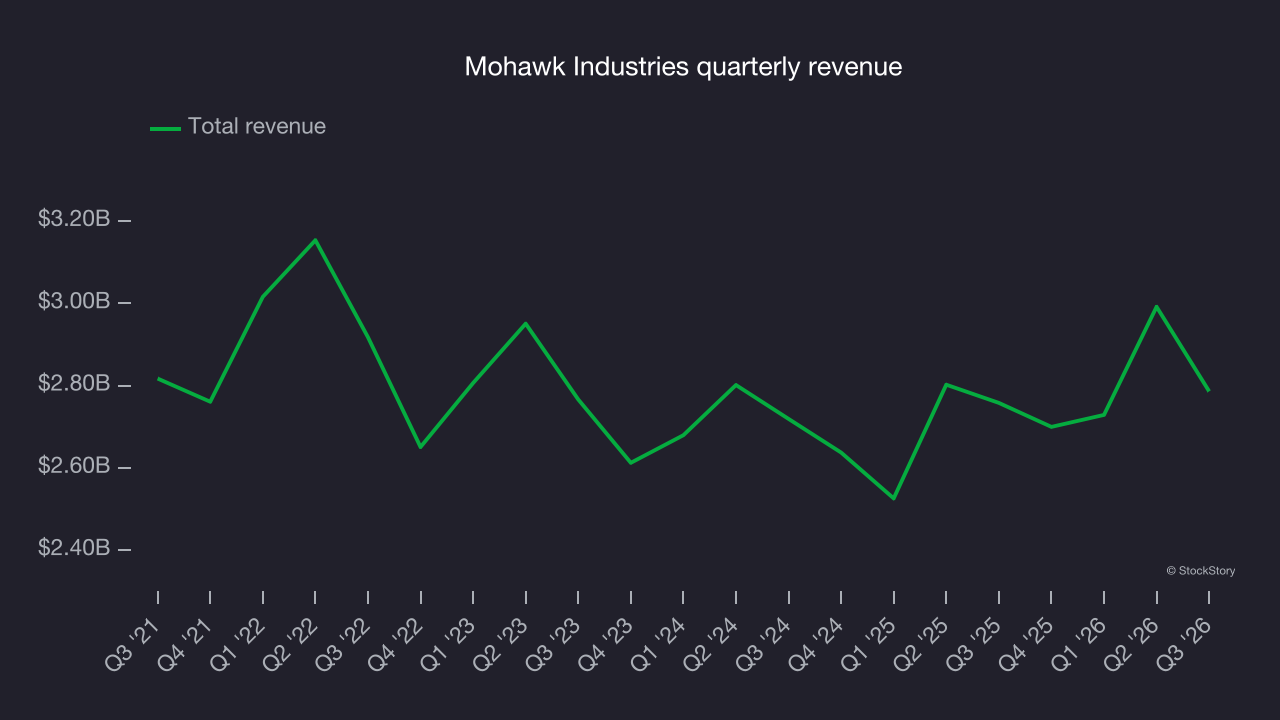
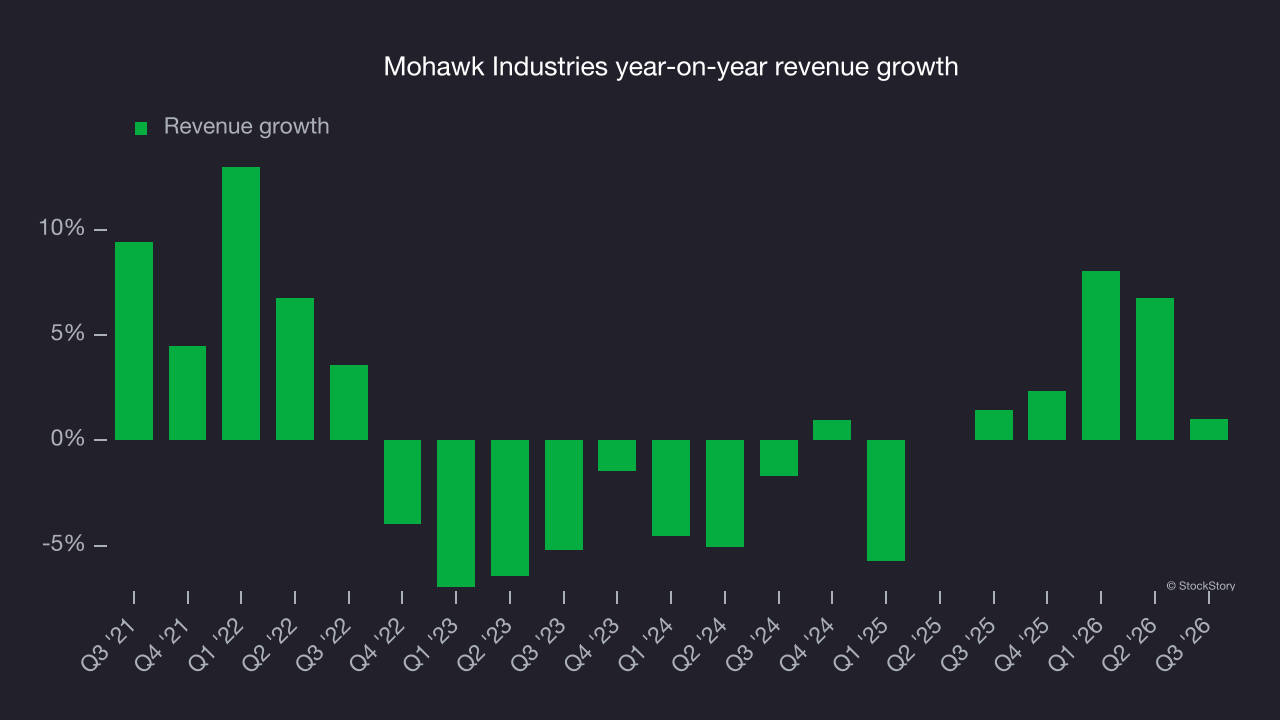
This quarter, Mohawk Industries’s revenue grew by 1% year on year to $2.79 billion, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. This uninspiring projection indicates its products and services will face some demand headwinds.
Operating margin
Mohawk Industries’s operating margin has generally stayed the same over the last 12 months, but ideally, economies of scale and cost efficiency would lift margins over time.
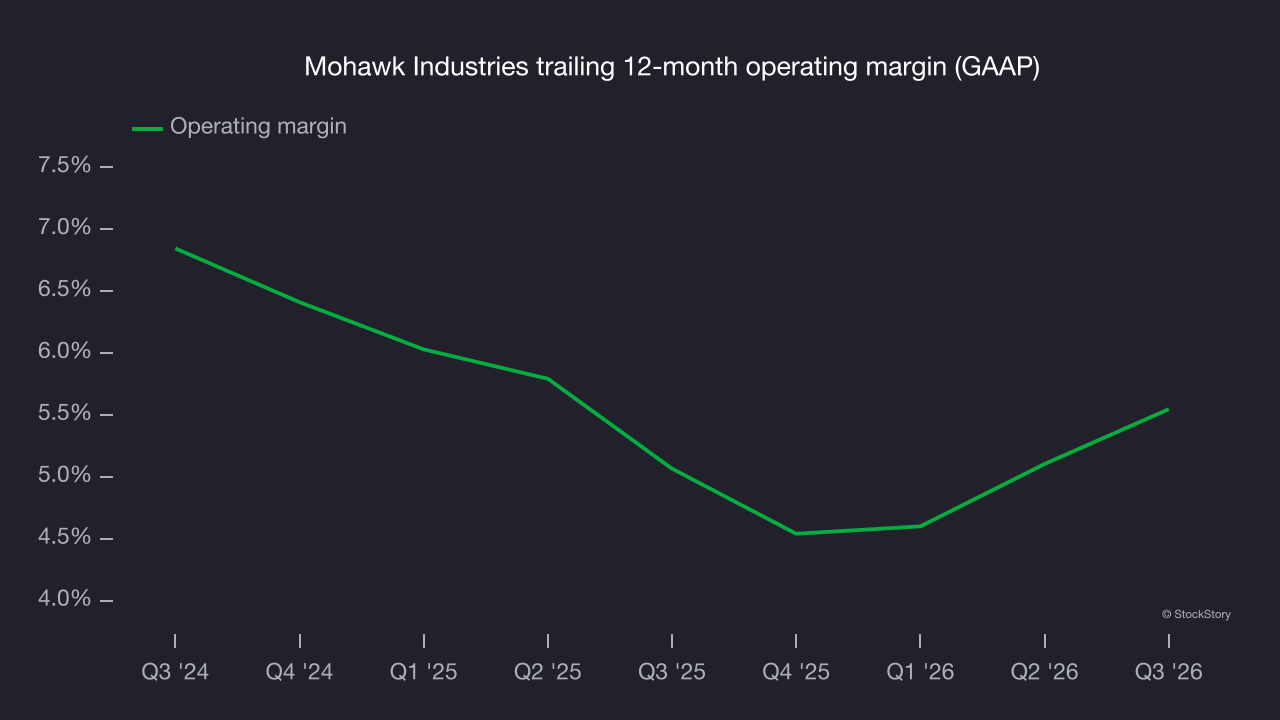
This quarter, Mohawk Industries generated an operating margin of 6.7%, up 1.8 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Mohawk Industries’ EPS declined by 7.8% annually over the last five years while its revenue was flat. The company struggled because its fixed cost base made it difficult to adjust to choppy demand.
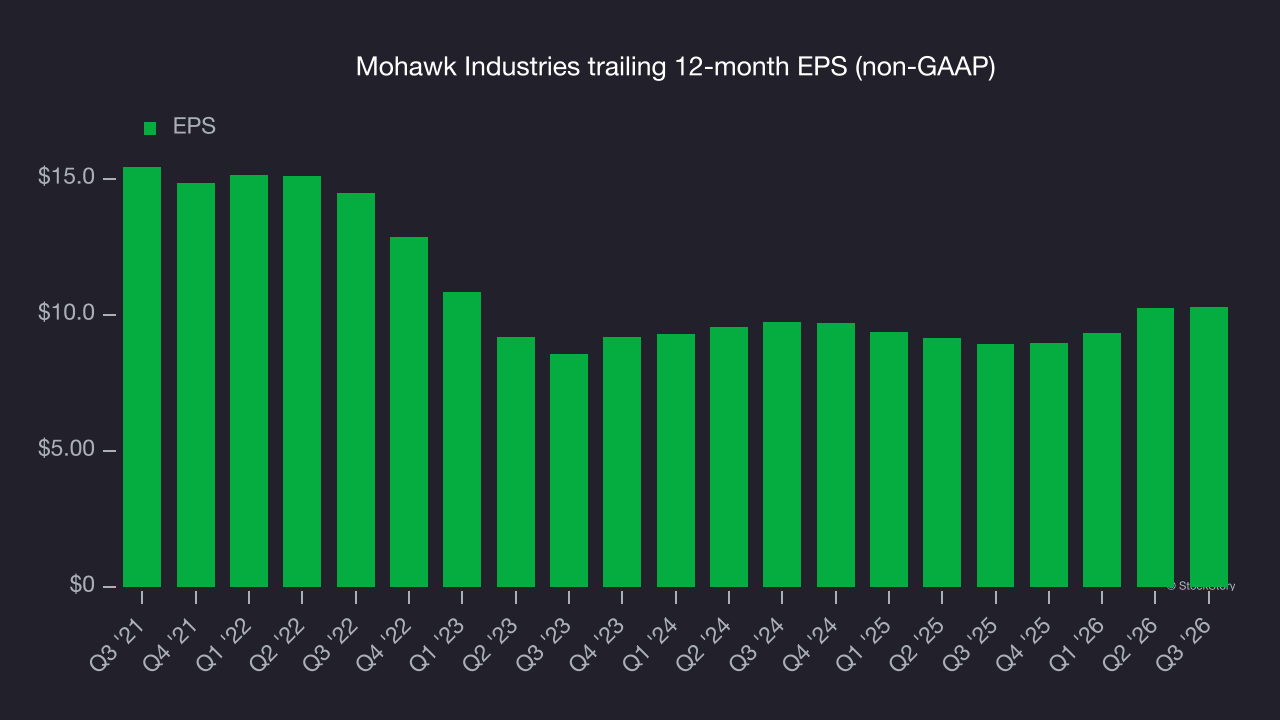
In Q3, Mohawk Industries reported adjusted EPS of $2.72, up from $2.67 in the same quarter last year. This result beat analysts’ consensus estimates by 5.4%. Over the next 12 months, Wall Street expects Mohawk Industries’ full-year EPS to shrink by 7.8% from $10.29 to $9.49, according to S&P.
Key takeaways from Mohawk Industries’s Q3 results
Mohawk Industries’ EPS beat was a positive, but revenue fell slightly short of Wall Street’s consensus estimates and next-quarter EPS guidance also missed. Those shortfalls made this a quarter that could have been better. Shares edged lower 1.3% to $128.50 immediately after the results.
Mohawk Industries underperformed this quarter. Whether that creates an investment opportunity requires a broader assessment. The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. For more on Mohawk Industries, read the full research report here (it’s free).