Chip designer Allegro MicroSystems (NASDAQ: ALGM) beat Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q2 2027), with revenue up 29.2% year on year to $276.9 million. Revenue guidance for next quarter was $283 million at the midpoint, 2.2% above analysts’ consensus estimates. Its non-GAAP profit of $0.26 per share was 6.3% above analysts’ consensus estimates.
For more on Allegro MicroSystems, read the full research report, available free.
Allegro MicroSystems (ALGM) Q3 CY2026 highlights:
- Revenue $276.9 million vs S&P analysts’ consensus estimates of $271.1 million (29.2% year-on-year growth, 2.1% beat)
- Adjusted EPS $0.26 vs S&P analysts’ consensus estimates of $0.24 (6.3% beat)
- Adjusted EBITDA $69.23 million vs analysts’ consensus estimates of $65.25 million (25% margin, 6.1% beat)
- Revenue guidance $283 million at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $276.9 million
- Adjusted EPS guidance $0.27 at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $0.26
- Operating margin 12.8%, up from 2.9% in the same quarter last year
- Free cash flow margin 11%, up from 6.5% in the same quarter last year
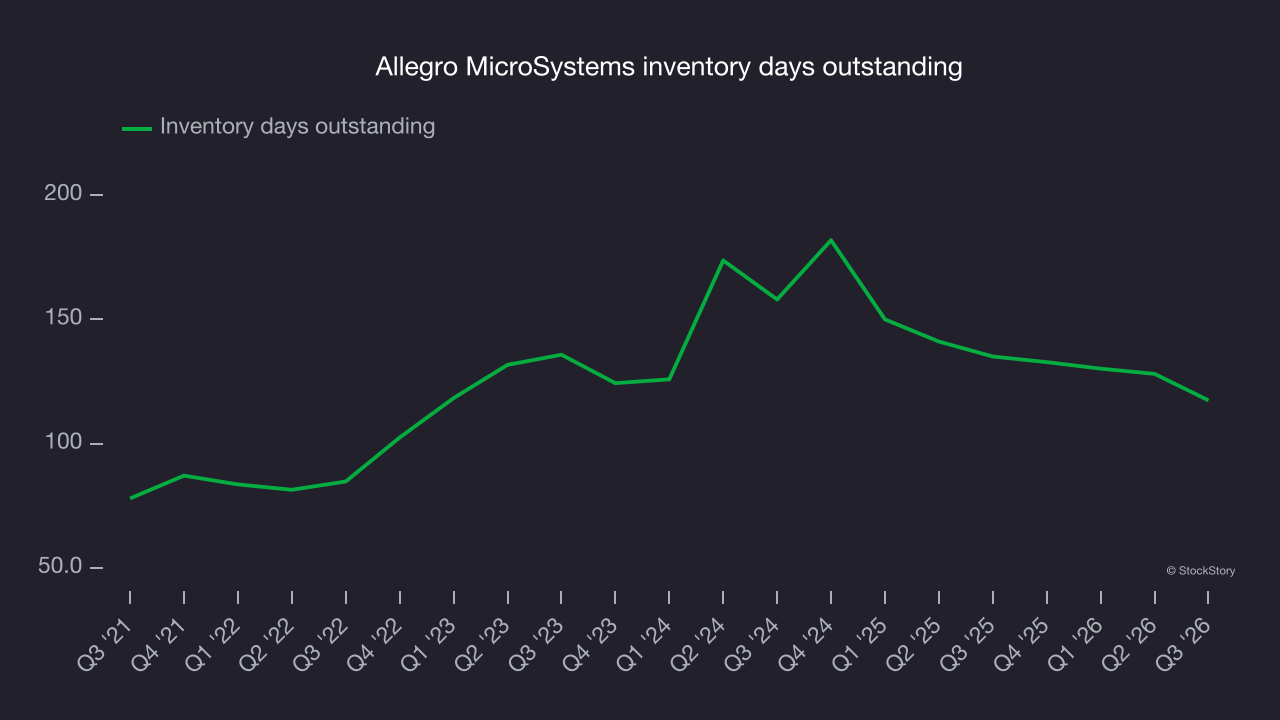
- Inventory days outstanding 117, down from 128 in the previous quarter
- Market capitalization $6.59 billion
“We saw continued strong momentum in our fiscal second quarter, delivering our seventh consecutive quarter of sequential sales growth. Sales were $277 million, representing a 29% increase year-over-year. GAAP earnings per share quadrupled from $0.03 per share in the fiscal second quarter of 2026 to $0.12. Non-GAAP EPS grew to $0.26, doubling over the second quarter of fiscal 2026. Broad year-over-year sales growth in Automotive and Industrial end markets drove this strong performance, led by data center, which established a new record,” said Mike Doogue, President and CEO of Allegro. “Our forward demand signals strengthened significantly this quarter. We delivered our highest quarterly design-win performance since our 2020 IPO—up nearly 40% year-over-year—and bookings increased for the eighth consecutive quarter. With record design wins, a robust backlog, and expanding content across our target Automotive and Industrial markets, the leading indicators across our business give us high confidence in our path to exceed our target model of mid-teens annual sales growth.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Allegro MicroSystems’s revenue grew at a decent 6.9% compounded annual growth rate over the last five years. Its growth was slightly above the average semiconductor company and shows its offerings resonate with customers. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
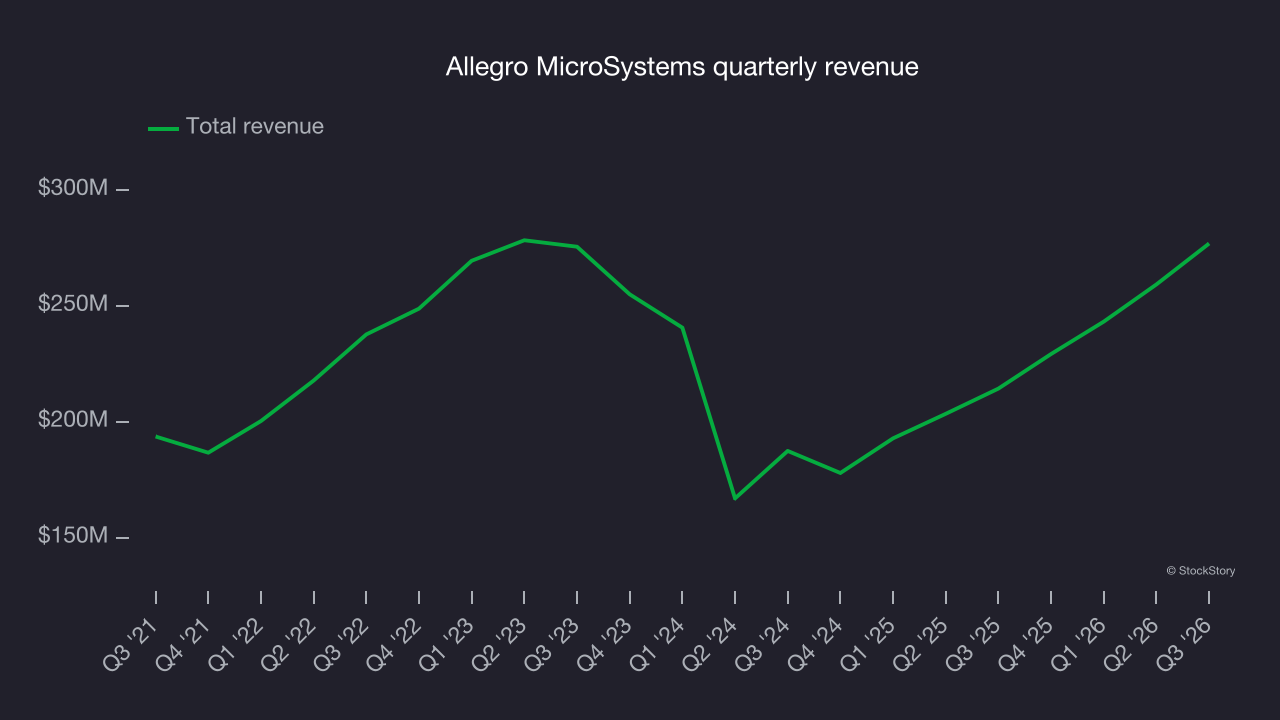
Long-term growth is the most important, but short-term results matter for semiconductors because the rapid pace of technological innovation (Moore’s Law) could make yesterday’s hit product obsolete today. Allegro MicroSystems’s annualized revenue growth of 8.9% over the last two years is above its five-year trend, which is encouraging. 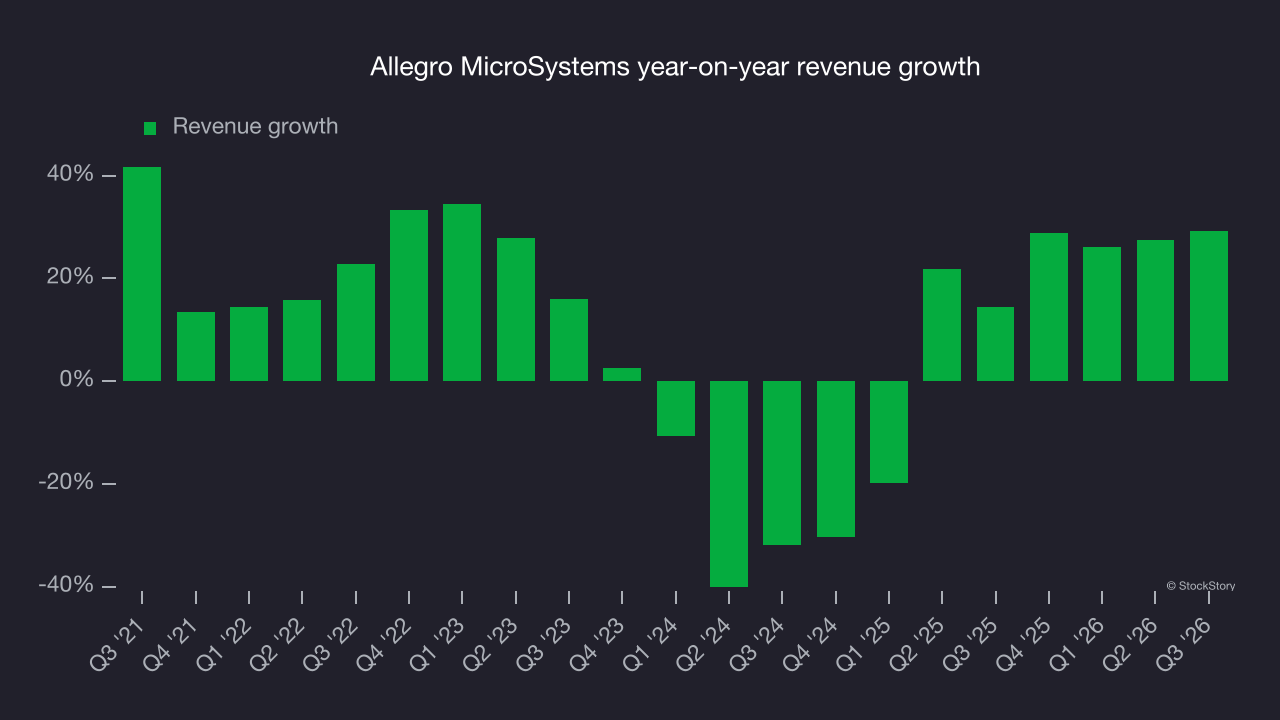
This quarter, Allegro MicroSystems reported strong year-on-year revenue growth of 29.2%, and its $276.9 million of revenue topped Wall Street’s consensus estimates by 2.1%. Beyond the beat, this marks 6 straight quarters of growth, showing that the current upcycle has had a sustained run; a typical upcycle lasts 8-10 quarters. Company management is currently guiding for a 23.5% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 17.6% over the next 12 months, according to S&P. Although this projection suggests its newer products and services will catalyze better top-line performance, it is still below the sector average.
Product demand & outstanding inventory
Days Inventory Outstanding (DIO) is an important metric for chipmakers, as it reflects a business’s capital intensity and the cyclical nature of semiconductor supply and demand. In a tight supply environment, inventories tend to be stable, allowing chipmakers to exert pricing power. Steadily increasing DIO can be a warning sign that demand is weak, and if inventories continue to rise, the company may have to downsize production.
This quarter, Allegro MicroSystems’s DIO came in at 117, which is 9 days below its five-year average. At the moment, these numbers show no indication of an excessive inventory buildup.
Key takeaways from Allegro MicroSystems’s Q3 results
A strong improvement in inventory levels and EPS above Wall Street’s consensus estimates made this a solid quarter for Allegro MicroSystems. Shares remained flat at $35.54 immediately after the results.
Allegro MicroSystems reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. That decision requires a broader look at valuation, business quality and the latest earnings. For more on those factors, read our full research report here (it’s free).