Goodyear’s stock price has taken a beating over the past six months, shedding 40.8% of its value and falling to $4.23 per share. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Goodyear, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Goodyear Will Underperform?
Despite the more favorable entry price, we don’t have much confidence in Goodyear. Here are three reasons you should be careful with GT, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
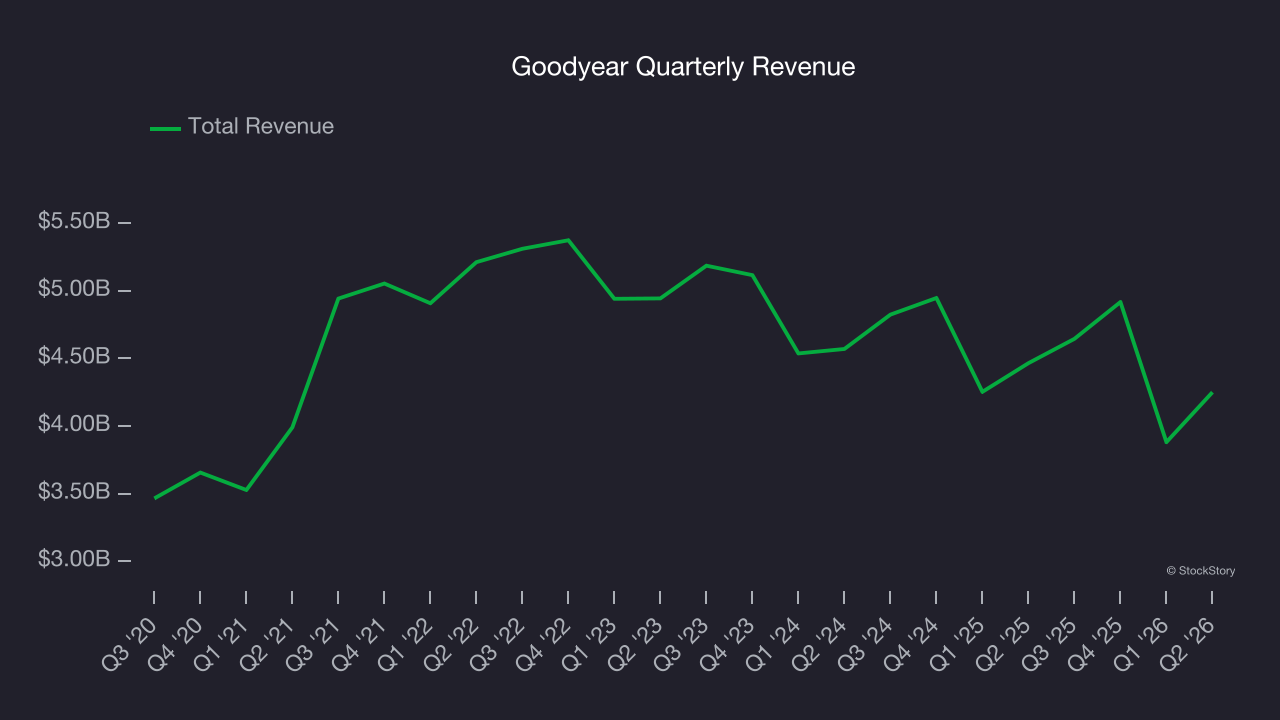
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Goodyear grew its sales at a sluggish 3.9% compounded annual growth rate. This was below our standard for the industrials sector.
2. EPS Trending Down
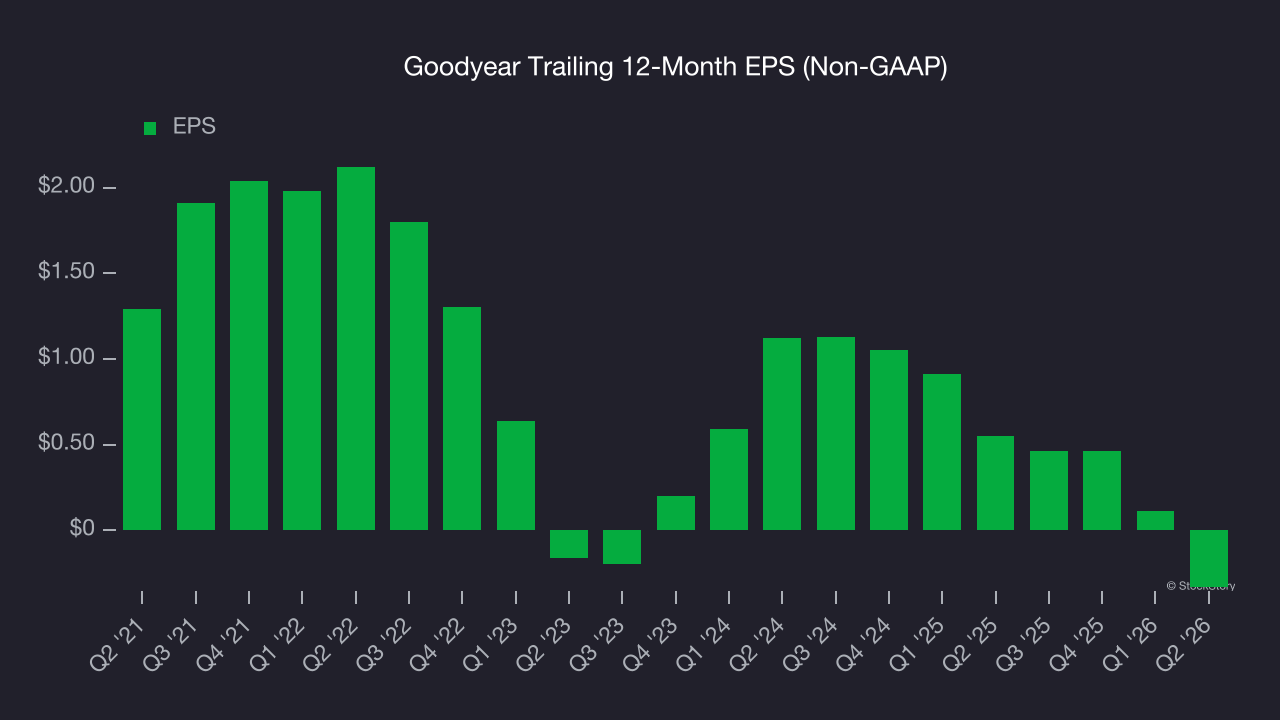
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for Goodyear, its EPS declined by 17.7% annually over the last five years while its revenue grew by 3.9%. This tells us the company became less profitable on a per-share basis as it expanded.
3. Cash Burn Ignites Concerns
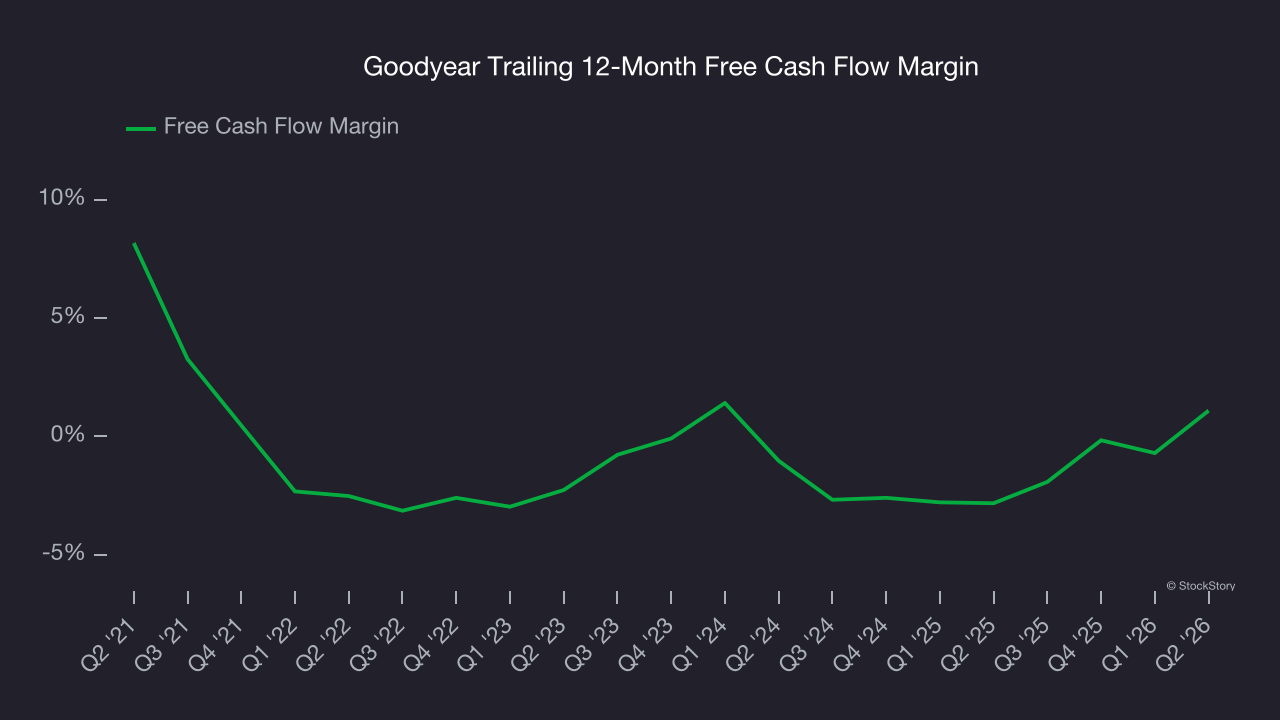
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Goodyear’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 1.6%, meaning it lit $1.56 of cash on fire for every $100 in revenue.
Final Judgment
Goodyear doesn’t pass our quality test. Following the recent decline, the stock trades at $4.23 per share (or a forward price-to-sales ratio of 0.1×). The market typically values companies like Goodyear based on their anticipated profits for the next 12 months, but it expects the business to lose money. We also think the upside isn’t great compared to the potential downside here - there are more exciting stocks to buy. Let us point you toward our favorite semiconductor picks and shovels play.
Stocks We Would Buy Instead of Goodyear
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.