As the Q2 earnings season comes to a close, it’s time to take stock of this quarter’s best and worst performers in the reinsurance industry, including Hamilton Insurance Group (NYSE: HG) and its peers.
This is a cyclical industry, and the sector benefits when there is a 'hard market', characterized by strong premium rate increases that outpace loss and cost inflation, resulting in robust underwriting margins. The opposite is true in a 'soft market'. Interest rates also matter, as they determine the yields earned on fixed-income portfolios. The primary headwind remains the immense and concentrated exposure to large-scale catastrophe losses, as the growing impact of climate change challenges traditional risk models and creates significant earnings volatility. Additionally, they face the risk of adverse prior-year reserve development, where claims prove more costly than anticipated, while the eventual influx of new capital from alternative sources threatens to soften the market and compress future returns.
The 5 reinsurance stocks we track reported a mixed Q2. As a group, revenues beat analysts’ consensus estimates by 3.8%.
In light of this news, share prices of the companies have held steady as they are up 1.8% on average since the latest earnings results.
Best Q2: Hamilton Insurance Group (NYSE: HG)
Founded in 2013 and operating through three distinct underwriting platforms across four countries, Hamilton Insurance Group (NYSE: HG) operates global specialty insurance and reinsurance platforms across Lloyd's, Ireland, Bermuda, and the United States.
Hamilton Insurance Group reported revenues of $839.6 million, up 13.3% year on year. This print exceeded analysts’ expectations by 19.9%. Overall, it was an incredible quarter for the company with a beat of analysts’ EPS estimates.
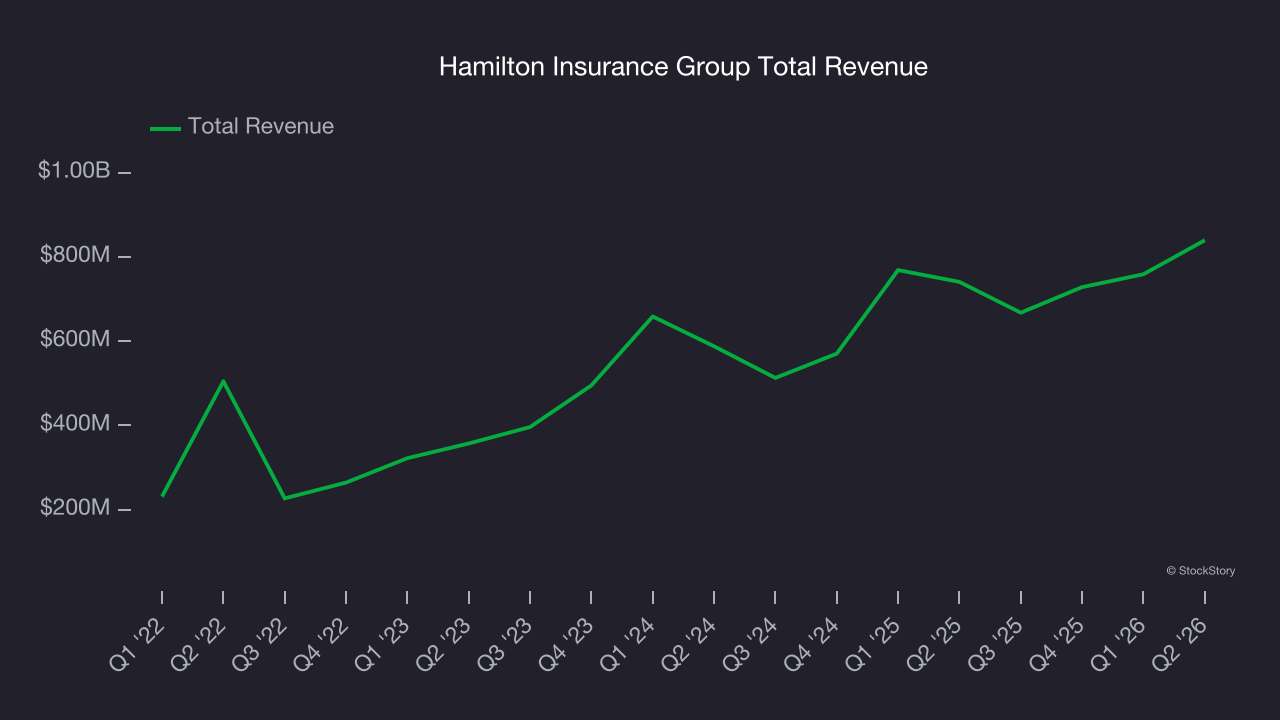
Hamilton Insurance Group scored the biggest analyst estimate beat in the group. Unsurprisingly, the stock is up 1.8% since reporting and currently trades at $36.19.
Is now the time to buy Hamilton Insurance Group? Access our full analysis of the earnings results here, it’s free.
Reinsurance Group of America (NYSE: RGA)
Operating behind the scenes of the insurance industry since 1973, Reinsurance Group of America (NYSE: RGA) provides life and health reinsurance services to insurance companies, helping them manage risk and meet regulatory requirements.
Reinsurance Group of America reported revenues of $6.83 billion, up 20.2% year on year, outperforming analysts’ expectations by 2.9%. The business had an exceptional quarter with a solid beat of analysts’ book value per share estimates and a beat of analysts’ EPS estimates.
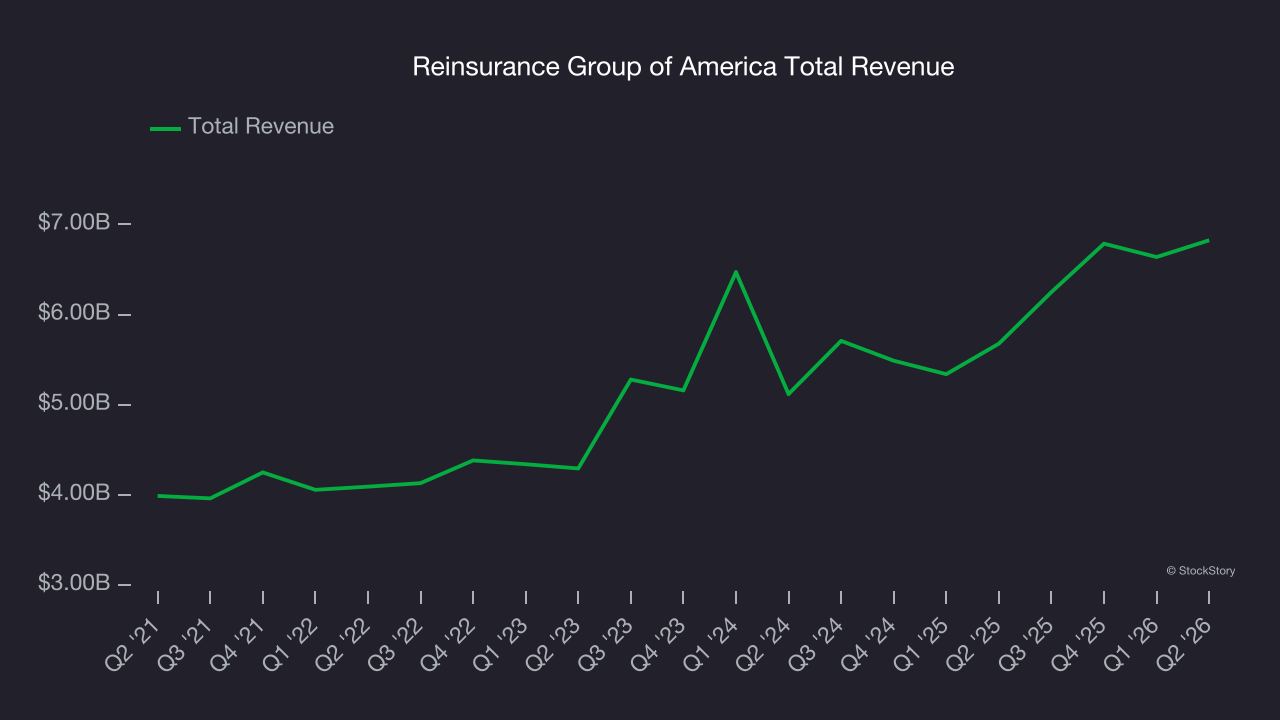
Reinsurance Group of America pulled off the fastest revenue growth of the whole group. The market seems happy with the results as the stock is up 13.1% since reporting. It currently trades at $267.16.
Is now the time to buy Reinsurance Group of America? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: AXIS Capital (NYSE: AXS)
Founded in the aftermath of the 9/11 attacks when insurance capacity was scarce, AXIS Capital Holdings Limited (NYSE: AXS) is a global specialty insurer and reinsurer that provides coverage for complex risks across property, liability, professional lines, cyber, and other specialty markets.
AXIS Capital reported revenues of $1.71 billion, up 7.3% year on year, falling short of analysts’ expectations by 3.6%. It was a disappointing quarter as it posted a significant miss of analysts’ net premiums earned estimates and a significant miss of analysts’ EPS estimates.
AXIS Capital delivered the weakest performance against analyst estimates in the group. As expected, the stock is down 17.4% since the results and currently trades at $98.48.
Read our full analysis of AXIS Capital’s results here.
Everest Group (NYSE: EG)
Rebranded from Everest Re in 2023 to reflect its evolution beyond just reinsurance, Everest Group (NYSE: EG) underwrites property and casualty reinsurance and insurance worldwide, serving insurance companies, corporations, and other clients across six continents.
Everest Group reported revenues of $3.96 billion, down 11.8% year on year. This result lagged analysts’ expectations by 1.8%. It was a softer quarter as it also produced a significant miss of analysts’ net premiums earned estimates and a miss of analysts’ book value per share estimates.
The stock is down 1.2% since reporting and currently trades at $388.98.
Read our full, actionable report on Everest Group here, it’s free.
RenaissanceRe (NYSE: RNR)
Born in Bermuda after the devastating Hurricane Andrew created a crisis in the catastrophe insurance market, RenaissanceRe (NYSE: RNR) provides property, casualty, and specialty reinsurance and insurance solutions to customers worldwide, primarily through intermediaries.
RenaissanceRe reported revenues of $2.77 billion, down 13.7% year on year. This print topped analysts’ expectations by 3.7%. Overall, it was a very strong quarter as it also produced a beat of analysts’ EPS estimates.
RenaissanceRe had the slowest revenue growth among its peers. The stock is up 10.3% since reporting and currently trades at $352.52.
Read our full, actionable report on RenaissanceRe here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.